
 …
7 September 2026
1. Introduction
On 24 July 2026, The Stock Exchange of Hong Kong Limited (the “Exchange”), a wholly-owned subsidiary of the Hong Kong Exchanges and Clearing Limited (“HKEX”), published the consultation conclusions (the “Consultation Conclusions”) on their consultation paper on the Listing Framework Competitiveness Review. This marks the initial phase of the Exchange’s competitiveness review of Hong Kong’s listing framework, seeking market feedback on targeted reforms aimed at broadening company diversity, expanding investment opportunities, and maintaining robust investor protections.
The proposals aim to reform the existing environment primarily by refining the existing listing framework in three vital areas:
- Expanding the Weighted Voting Rights (WVR) regime by lowering market capitalisation and financial eligibility thresholds and relaxing certain WVR restrictions to enhance market competitiveness.
- Altering the regime to support overseas-listed issuers, which includes introducing measures to facilitate overseas issuers’ listings in Hong Kong and lowering the eligibility thresholds for secondary listings. This lowers the barrier for overseas issuers to access the Hong Kong market and strengthens Hong Kong’s competitiveness as an international listing venue.
- Enhancing initial listing requirements and arrangements to streamline the listing process and improve the protection of commercially sensitive information. This is done by improving the listing pathway for commercialised biotech and specialist technology companies, expanding the scope of confidential filing of listing applications to cover all new applicants, and refining the return mechanism.
2. The key proposals to be adopted
| Subject | Current requirements | Key Proposals to be Adopted |
| WVR (Weighted Voting Rights) | ||
| Financial eligibility | The market capitalisation threshold:
– (Test A) at least HK$40 billion. – (Test B) HK$10 billion with revenue of at least HK$1 billion for the most recent audited financial year.
|
To lower the thresholds to market capitalisation: (A) ≥ HK$20 billion; or (B) ≥ HK$6 billion and revenue for the most recent audited financial year ≥ HK$600 million.
|
| Voting power and economic interest | Weighted voting ratio ≤ 10:1. | To allow a higher weighted voting ratio cap of 20:1 if market capitalisation at listing ≥ HK$40 billion.
|
| WVR shareholding percentage ≥ 10% at listing (a lower percentage may be accepted on a case-by-case basis). | To allow WVR shareholding percentage ≥ 5% only if it represents an amount of ≥ HK$4 billion at listing. | |
| Innovativeness and other suitability requirements | An applicant must demonstrate that it is an “innovative” company for listing with WVR.
|
To refine the “innovative” test to explicitly provide a path to listing, with WVR, for non-tech issuers applying a new business model. |
| Applicants that are biotech companies or specialist technology companies are presumed to be innovative. | To expand the scope of technology companies presumed to be innovative (including qualified biotech and specialist technology companies even if they do not seek to list under the Specialist Chapters). | |
| An applicant must have previously received meaningful third-party investment from at least one sophisticated investor. | To provide greater clarity on external validation requirements. | |
| Issuers listed overseas | ||
| Qualification requirements for secondary listings | WVR: Two-year compliant track record on a Qualifying Exchange with same financial eligibility thresholds as primary WVR listings. | WVR: To lower financial eligibility thresholds to match those for primary WVR listings. |
| Non-WVR: Market capitalisation: (A) ≥ HK$3 billion (for a five-year compliant track record on a Qualifying Exchange or Recognised Stock Exchange); or (B) ≥ HK$10 billion (for a two-year compliant track record on a Qualifying Exchange) | Non-WVR: To lower the HK$10 billion market capitalisation threshold under test (B) to HK$6 billion. | |
| Conversion to primary listing | Guidance is available to facilitate conversion from a secondary listing to a (dual) primary listing. | To publish streamlined guidance on secondary listed issuers’ conversion to primary listing and provide guidance on the typical steps required for compliance. |
| Further facilitative
measures for issuers listed overseas |
N/A | To continue to consider respondents’ suggestions on measures to further facilitate the listings of issuers listed overseas and conduct a public consultation if necessary. |
| Initial listing requirements and listing arrangements | ||
| Ownership continuity
and control |
An applicant must have
been operating as an integrated unit under the same shareholder that is able to exert substantial influence on the management in the relevant period |
To codify existing guidance: Clarify that an applicant
will be considered to have satisfied the ownership continuity and control requirement if it can demonstrate that there was no material change during the relevant period despite a change in ownership. |
| Financial reporting
standards |
An applicant listed / to be listed in the US seeking a dual primary or secondary listing in Hong Kong may apply for a waiver to adopt US GAAP. | To expand the allowance of US GAAP to subsidiaries of US listed parents and companies with substantial US business operations. |
| US GAAP reporters must revert to HKFRS or IFRS upon a US delisting. | To remove this requirement. | |
| A reconciliation statement for unaudited financial reports must be reviewed by auditors. | To remove this requirement. | |
| Commercialised Biotech
and Specialist Technology Applicants |
A Biotech Company or Specialist Technology Company must list under the ordinary route to listing, and not the specialist routes (Chapters 18A or 18C), if it can meet any financial eligibility test under Chapter 8 of the Main Board Listing Rules. | To permit such applicants to seek a listing as a biotech company or specialist technology company under the specialist routes even if they are financially eligible under the ordinary route to listing. |
| Confidential filing and enhanced Return Mechanism | Confidential filing is only
available to eligible secondary listing applicants, biotech companies, and specialist technology companies, or subject to case-by-case waivers for other applicants |
To expand the non-public filing option to all new applicants.
|
| An application that is not substantially complete may be returned, upon which the sponsor’s identity will be displayed on the Exchange’s website. | To enhance the Return Mechanism to display (in addition to the sponsor’s identity) the identities and roles of the professional parties involved in preparing the application materials upon a return of the listing application, and the reasons for return. | |
3.Conclusion
The relevant Listing Rule amendments became effective immediately upon publication of the Consultation Conclusions on 24 July 2026.
The reforms hold significant relevance to all companies considering applying for a listing on the Exchange, particularly those in biotech and technology sectors. Significantly, listing applicants are advised to take into account the following:
- The reduction in the market capitalisation thresholds for WVR companies will enable more mid-sized technology and innovative companies to list on the Exchange with a WVR structure.
- The formalisation of two pathways for satisfying the innovative company requirement, namely a technology-based route (Route A) and a business model-based route (Route B), provides greater certainty and a clearer pathway for different types of innovative companies seeking a WVR listing.
- Biotech and specialist technology companies that already meet the financial eligibility tests are given the option to list under the applicable specialist chapters, providing a wider range of choices to listing applicants.
- The expansion of the non-public filing regime to all new applicants, together with the enhanced Return Mechanism, is expected to provide greater flexibility during the IPO process while increasing accountability among professional advisers involved in listing applications.
The Exchange has indicated that these reforms represent the first phase of its competitiveness review, with further consultations and potential reforms to the listing framework expected in due course.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
HKEX Announces Major Change: Validity Period of New Listing Applications Extended from Six Months to Twelve Months
 …
7 September 2026
1. Introduction
On 21 August 2026, The Stock Exchange of Hong Kong Limited (the “Stock Exchange”), a wholly-owned subsidiary of Hong Kong Exchanges and Clearing Limited (the “HKEX”), announced the implementation of a temporary waiver under which the validity period of eligible new listing applications will be extended from six months to twelve months from the date of submission of the listing application form, subject to certain conditions and safeguards (the “Temporary Waiver”). The Temporary Waiver will apply for a period of three years from the date of the announcement, namely from 21 August 2026 to 20 August 2029.
2. Key Features of the New Measure
According to the Stock Exchange’s announcement, the Temporary Waiver applies to all new listing applications that satisfy the conditions set out in the announcement, including: (a) listing applications that remained valid as of 21 August 2026 (being the date of the announcement); and (b) listing applications submitted or re-submitted on or after 21 August 2026. To qualify for the Temporary Waiver, the following conditions must be met:
- the Stock Exchange must not have stated in its comment letter that the review of the applicant’s new listing application has been suspended; and
- the Securities and Futures Commission (the “SFC”) and/or the Stock Exchange must not have issued a direct request for information letter and/or a material comment letter to the applicant.
Where the concerns identified in such regulatory correspondence have been satisfactorily addressed and accepted by the relevant regulator before the expiry of the initial six-month validity period, the relevant listing application may still qualify for the Temporary Waiver.
Applicants benefiting from the extended validity period must continue to comply with all applicable Listing Rules and provide complete and up-to-date information, including updated business and financial information, to enable regulators to properly assess each application and investors to make informed decisions. The extension does not alter the Stock Exchange’s existing regulatory standards or investor protection measures. The Stock Exchange will monitor the implementation and effectiveness of the Temporary Waiver and may review the relevant requirements or conduct a public consultation if considered necessary and appropriate.
3. Enhancing Flexibility and Reducing Repetitive Work
The Temporary Waiver is designed to provide applicants, sponsors and their advisers with greater flexibility in managing listing timetables, while reducing the frequency of re-submissions and the associated burden of repeatedly updating application documents and supporting materials. This allows market participants to focus more effectively on maintaining the quality of listing application documents and prospectus disclosures.
Ms. Katherine Ng, Head of Listing at HKEX, commented: “HKEX is committed to continuously enhancing the efficiency and competitiveness of Hong Kong’s listing regime while maintaining rigorous regulatory standards and protecting the public interest. With the support of the SFC, this extension builds upon the enhanced listing application timetable introduced jointly by HKEX and the SFC in October 2024, providing applicants with greater flexibility in managing listing timelines and supporting a more focused and efficient application process.”
4. Continuing Listing Reforms and Strengthening Hong Kong’s Position as an International Financial Centre
The extension of the validity period for new listing applications represents another significant reform initiative following the enhanced timetable for new listing applications jointly announced by the SFC and the Stock Exchange in October 2024. The 2024 enhancements established clearer regulatory feedback timelines and review milestones, categorising listing applications into three different scenarios. The enhanced timetable was intended to enable most new listing applications to complete the regulatory review process within the existing six-month application validity period.
The latest measure doubles the validity period to twelve months, which is expected to reduce the need for re-submissions and extensive updating of application documents caused by application lapses. It also provides applicants with additional time to address regulatory comments and prepare listing documents.
Throughout the listing application process, applicants, sponsors and their advisers should continue to closely monitor the progress of their applications, promptly report material developments to regulators, and submit realistic timetables. Sponsors are expected to exercise due skill, care and diligence when establishing reasonable timelines, taking into account the time required by regulators to review and complete their assessments. Given the extended application validity period, the timing assumptions under the enhanced review timetable may be adjusted appropriately by reference to the latest progress updates and timetables provided by applicants and their sponsors.
5. Conclusion
The Stock Exchange’s decision to extend the validity period of new listing applications is a practical response to market demand. In today’s increasingly complex market environment, companies preparing for IPOs face greater uncertainty, and a longer application validity period will help alleviate timing pressures and avoid the need to re-submit substantial volumes of updated materials simply because an application has expired.
The new measure should also ease the workload of sponsors and professional advisers, enabling them to devote more attention to the quality of application materials and prospectus disclosures. Overall, the change reflects market realities and further enhances Hong Kong’s competitive position as an efficient, sophisticated and internationally recognised financial centre.
The introduction of the Temporary Waiver marks another important step by HKEX in refining its listing framework and strengthening market competitiveness. It is expected to have a positive and far-reaching impact on Hong Kong’s IPO market.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
Stevenson, Wong & Co. and Formex Financial Press Host Successful Joint Networking Drinks Evening in Central
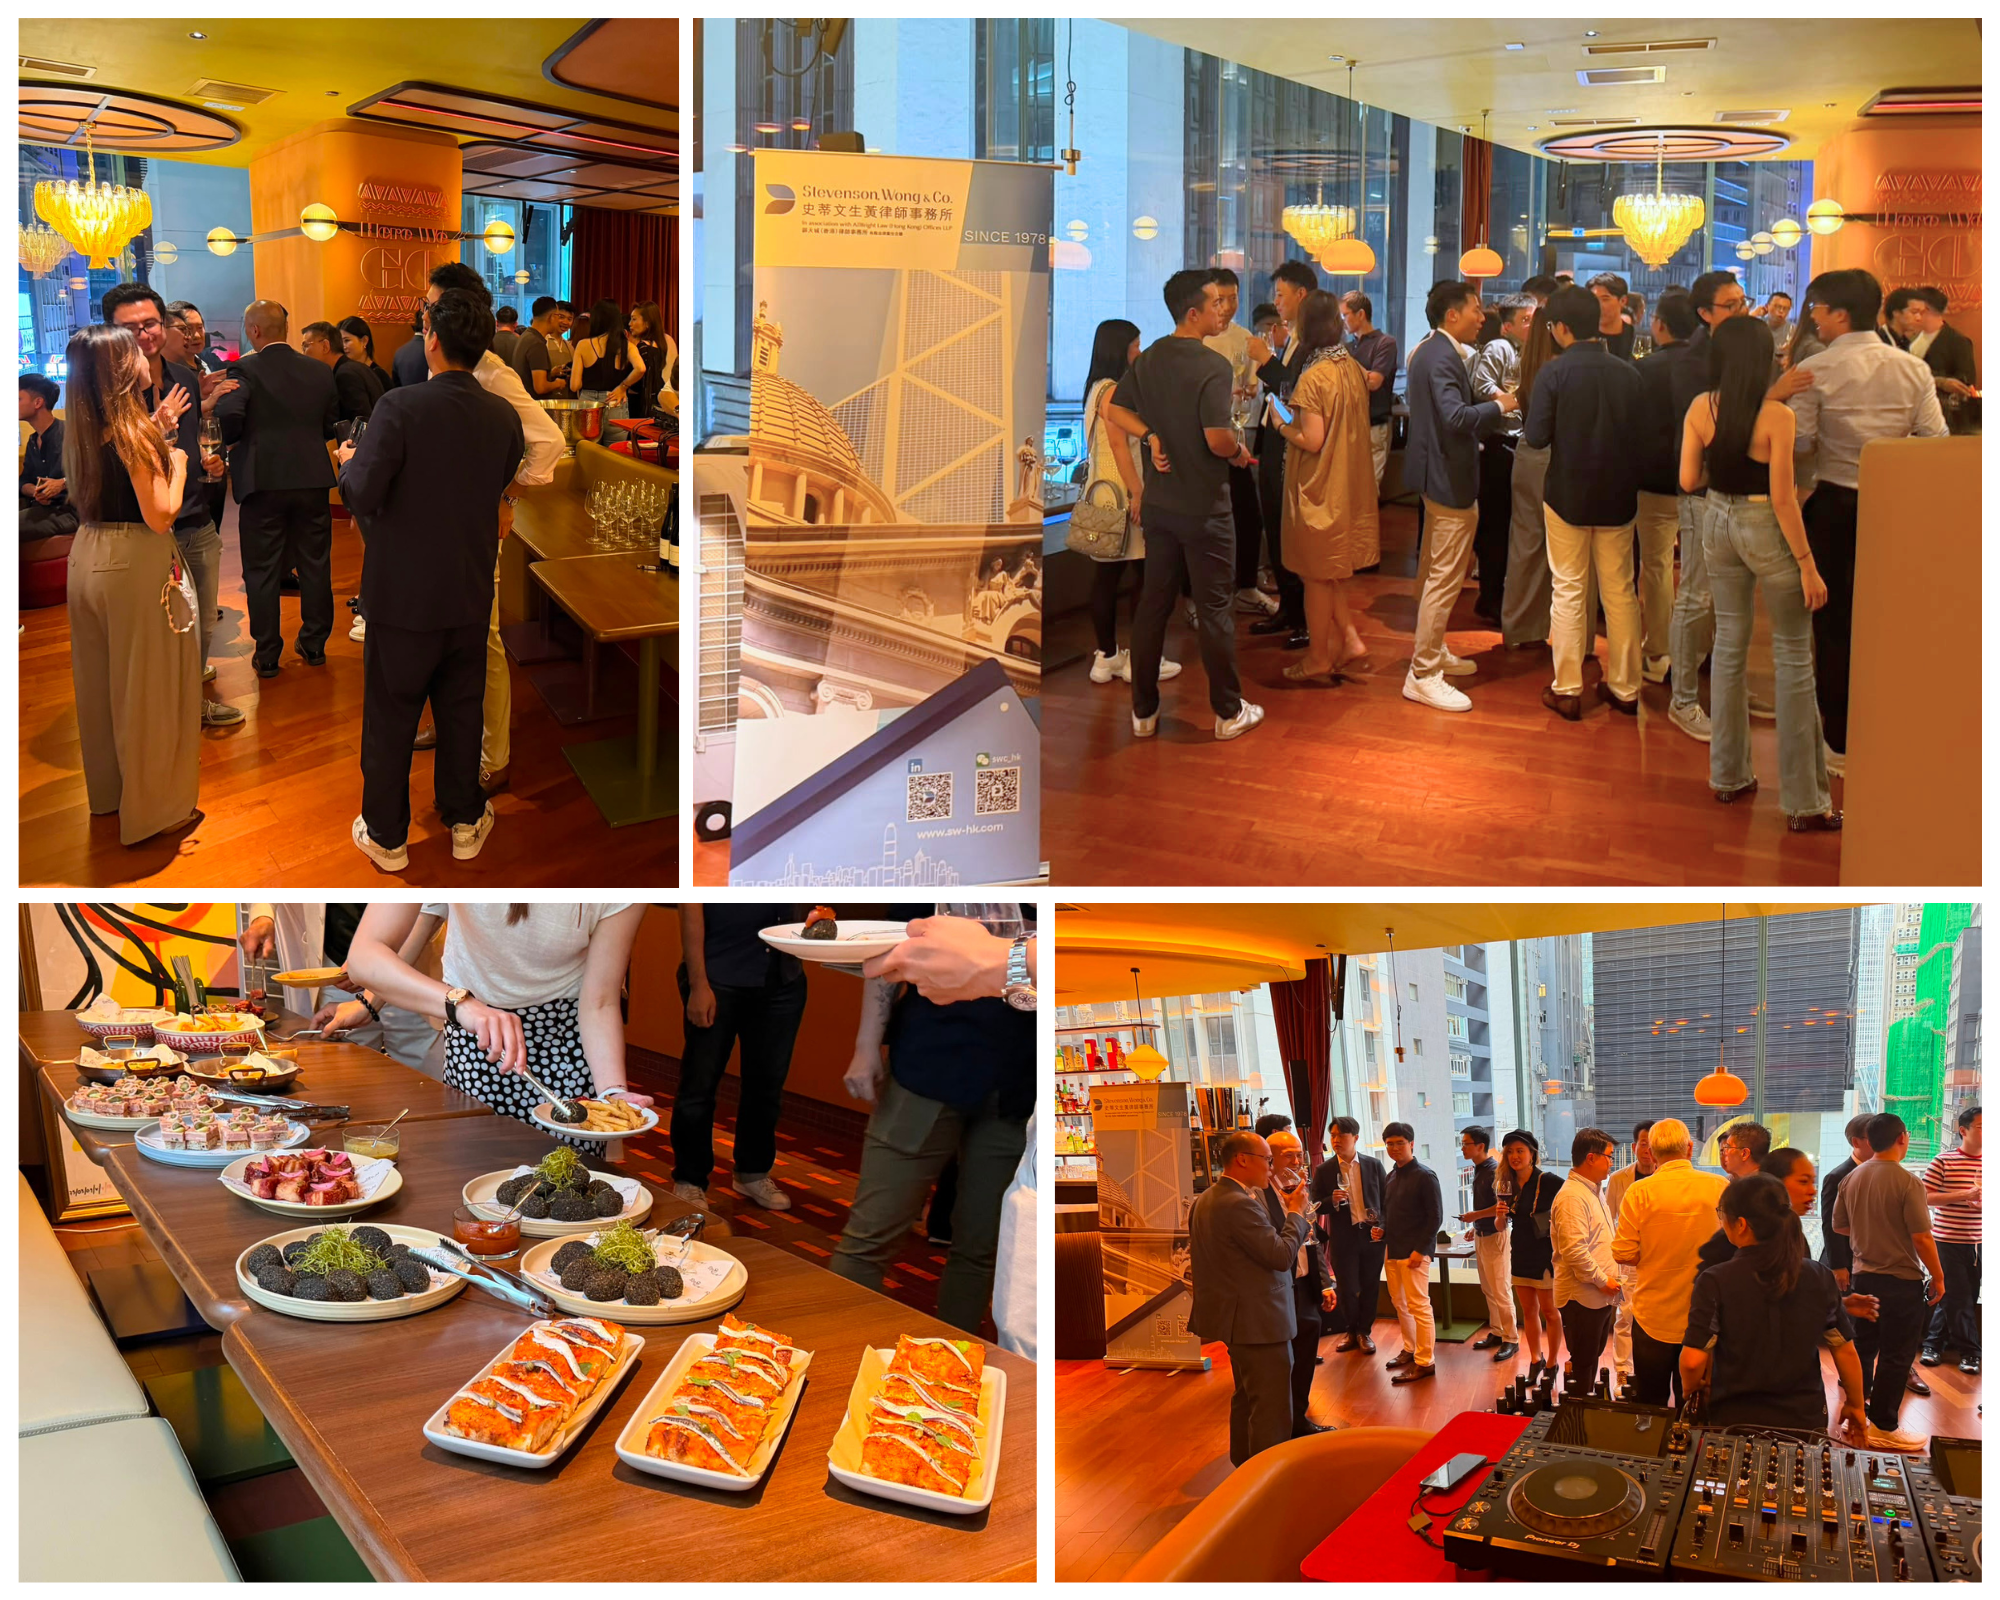
Stevenson, Wong & Co. (“SW”) was pleased to co-host an evening of networking drinks with Formex Financial Press on Friday, 21 August 2026, at MIGAS, H Queen’s in Central, Hong Kong.
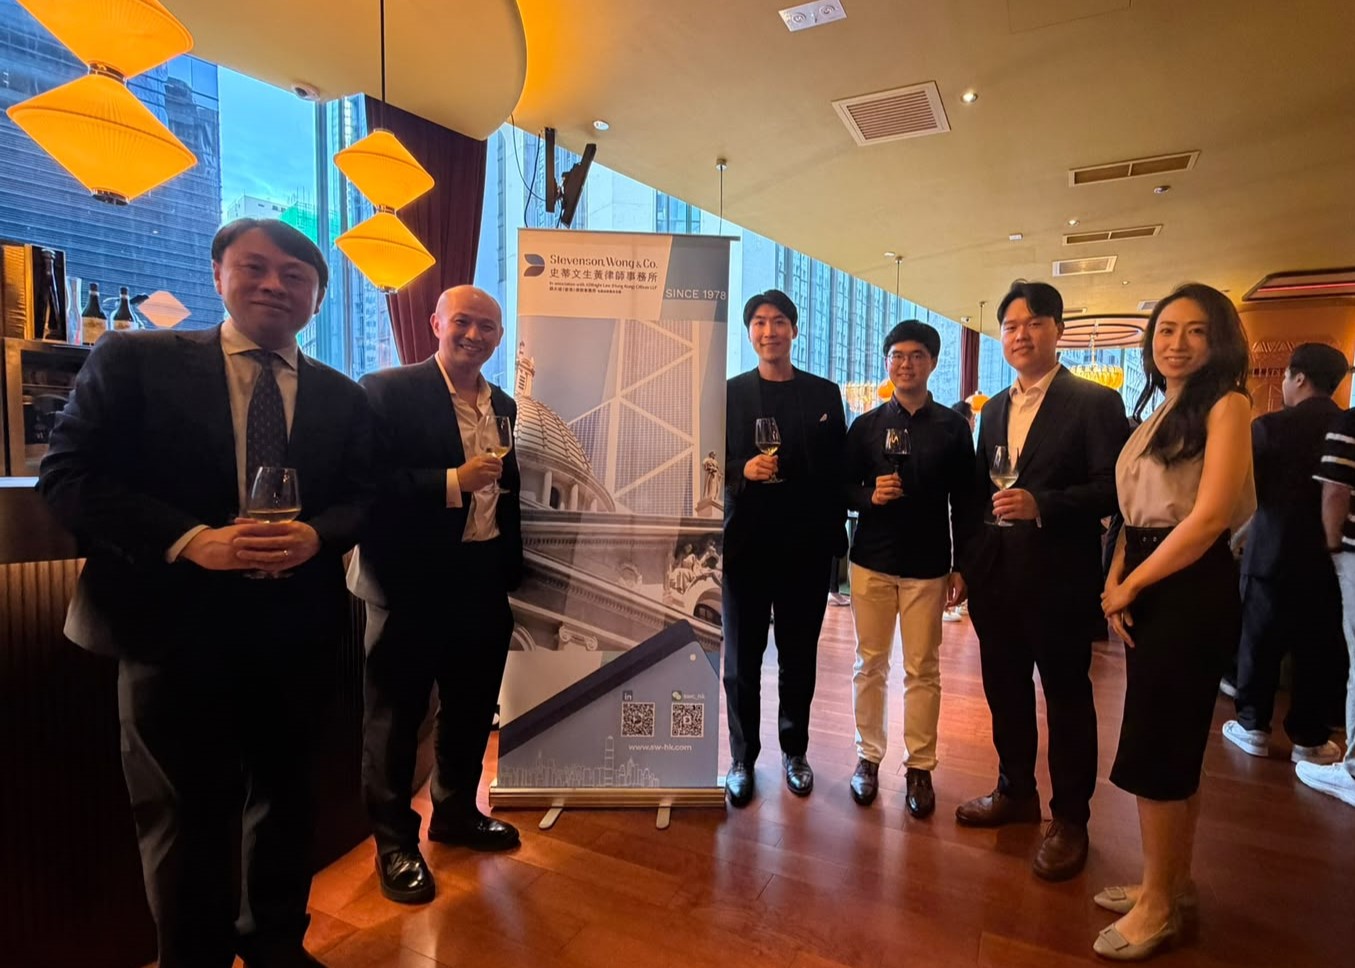 …
From the left: Consultant Philip Tsang, Partners Rodney Teoh and Kenneth Leung, Associates Ronnie Tse and Justin Kim, and Marketing and Communications Manager Julia Yeung.
The event brought together clients, business partners and professionals from across the legal, financial and business communities for an enjoyable evening of drinks, conversation and networking.
Set against the vibrant backdrop of Central, the event provided guests with an informal setting to reconnect with familiar faces, exchange perspectives and establish new professional connections. The evening offered a welcome opportunity for a lively and engaging conversations continuing throughout the event.
We were delighted to partner with Formex Financial Press in bringing our respective networks together and creating an enjoyable setting for new conversations and connections.
A warm thank you to everyone who joined us and made the evening such an enjoyable one. We look forward to staying connected and welcoming our clients, business partners and friends to more gatherings in the future.
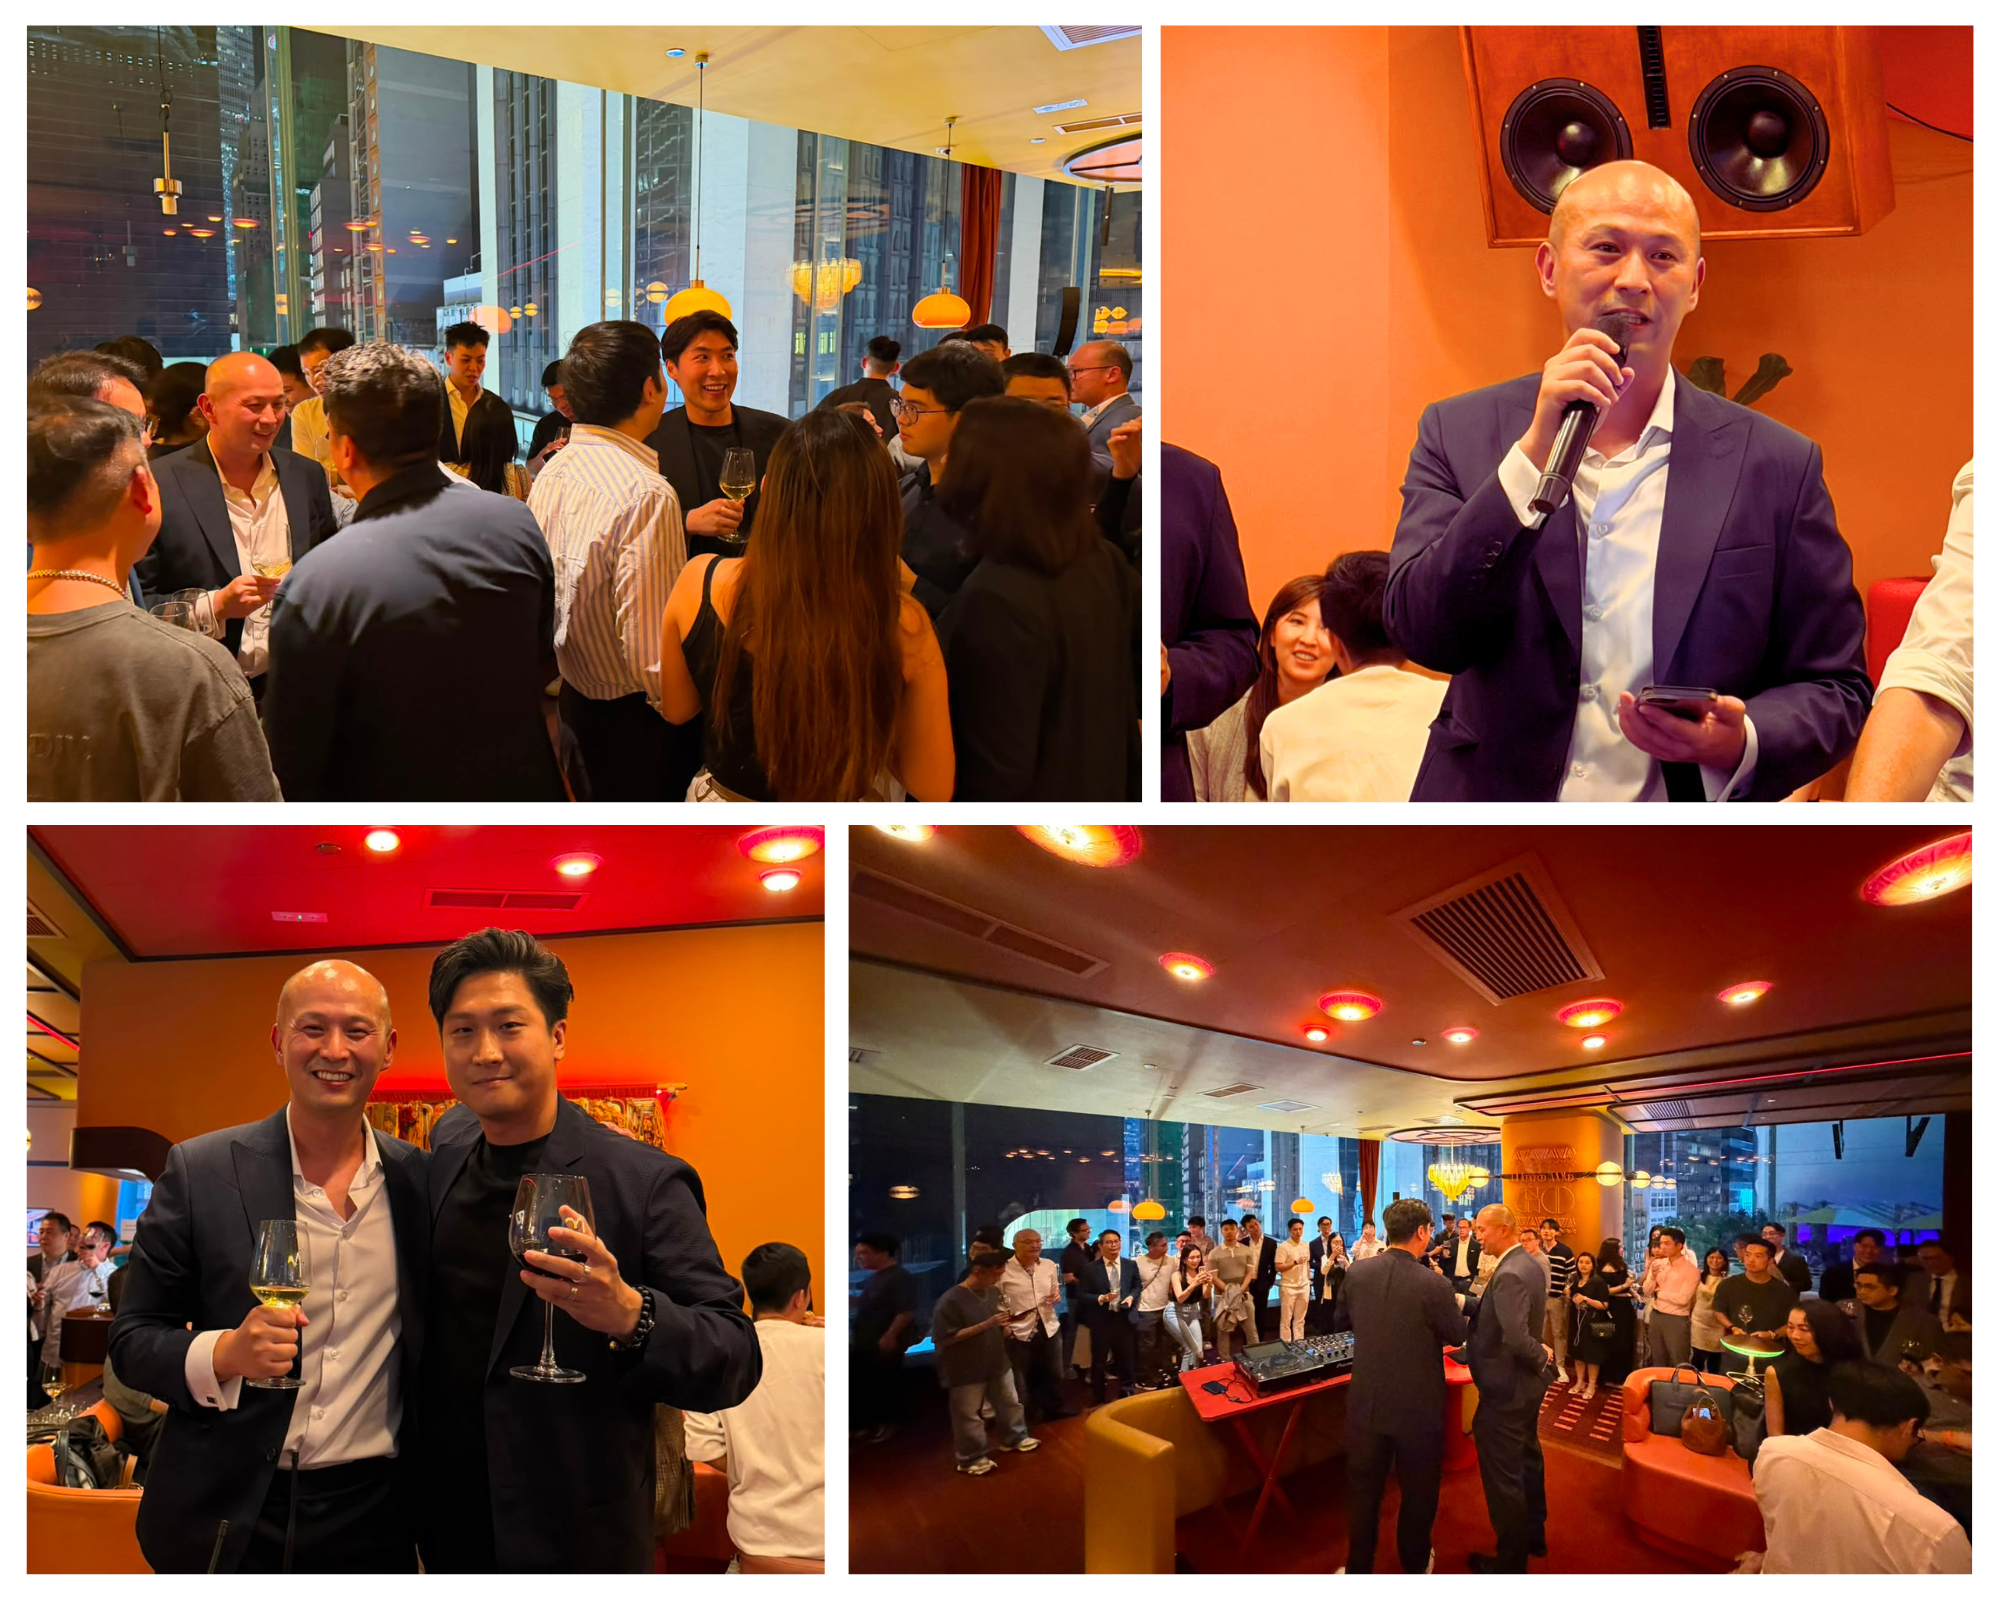
On the top right: Our Partner Rodney Teoh
On the botton Left: Our Partner Rodney Teoh (left) and Leo Chan, Director of Sales Marketing at Formex Financial Press (right)
Partner Kenneth Leung Recognised in Asian Legal Business Hong Kong Rising Stars 2026
 …
We are pleased to announce that our Partner, Kenneth Leung, has been named in the Asian Legal Business (ALB) Hong Kong Rising Stars 2026, recognising outstanding young legal practitioners in Hong Kong.
The annual ALB Hong Kong Rising Stars list recognises the achievements of the next generation of legal talent under the age of 40. Candidates are considered on the strength and complexity of their work, client feedback and their contribution to the wider legal profession.
Kenneth is a Partner in our Litigation & Dispute Resolution and Regulatory Enforcement & Compliance practices. He has extensive experience in complex commercial disputes and regulatory matters, with a particular focus on advising and representing corporations and financial institutions in contentious regulatory investigations, enforcement proceedings and related advisory matters.
Kenneth’s inclusion in the ALB Hong Kong Rising Stars 2026 recognises his strong legal and commercial judgement, professionalism and commitment to client service, as well as his expertise in navigating complex disputes and regulatory matters.
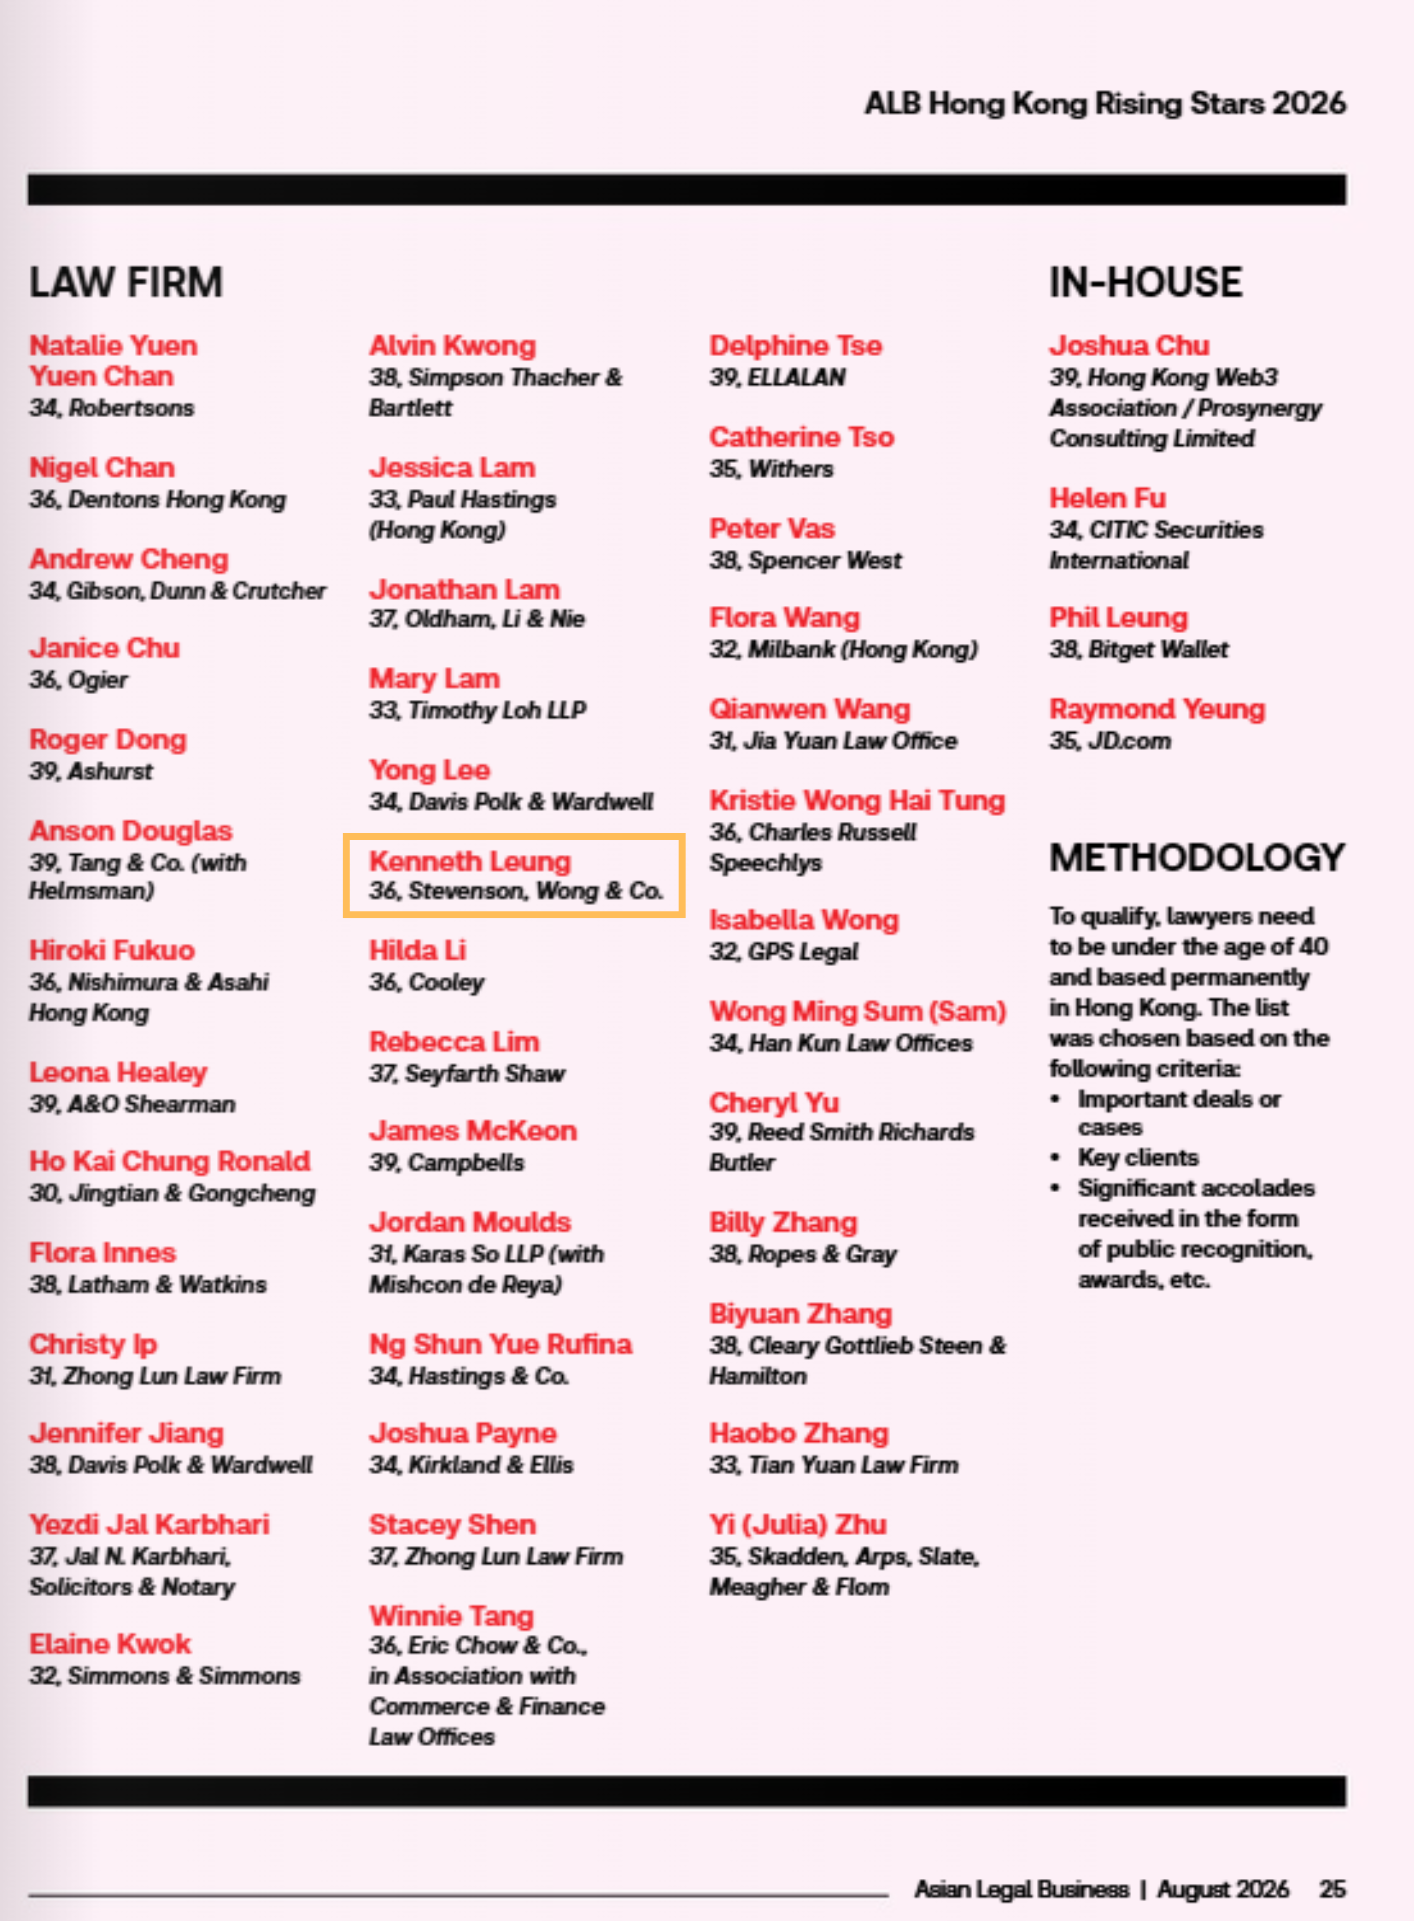
View the full-list of the ALB HK Rising Stars 2026 here.
Please contact our Partner Kenneth Leung for any enquiries or further information.
Closing the Loophole: Inside China’s Crackdown on Offshore Brokerages
 …
China’s securities regulator has fired its most significant shot yet in a years-long campaign against unlicensed cross-border brokerages. On 22 May 2026, the China Securities Regulatory Commission (“CSRC”), acting jointly with seven other government departments, announced it would impose firm and decisive enforcement action against (坚决予以打击)[1] three of the region’s most prominent online brokers:
- Tiger Brokers (NZ) Limited;
- Futu Securities International (Hong Kong) Limited; and
- Longbridge Securities (Hong Kong) Limited.
These coordinated actions — resulting in proposed penalties exceeding RMB 2.3 billion (~HK$2.67 billion), a mandatory two-year wind-down of mainland-facing operations, and a parallel Hong Kong regulatory response from the Securities and Futures Commission (“SFC”) — underscore Beijing’s determination to close unlicensed cross-border brokerage channels and reassert control over cross-border capital flows.
In this newsletter, our Regulatory Enforcement and Compliance team provides an overview of the CSRC’s findings, the mechanics of the rectification scheme, the SFC’s parallel action, and the critical takeaways for brokers, asset managers, and fintech platforms operating across the Hong Kong–Mainland border.
- CSRC’s position
On 22 May 2026, the CSRC announced it would impose firm and decisive enforcement action against on Tiger Brokers (NZ), Futu Securities International (Hong Kong), and Longbridge Securities (Hong Kong) for “illegally conducting securities business within China”, stating their activities violated China’s securities, funds and futures laws and disrupted market order (破坏了市场秩序).
Specifically, the CSRC found that the three firms had, without mainland licenses, solicited mainland investors, executed trades, and offered fund and futures brokerage services in breach of the PRC Securities Law. The CSRC formally opened cases against both onshore and offshore entities of all three firms.
The CSRC’s announcement can be accessed here.
The penalties are significant. The CSRC proposed roughly 2.3 billion yuan (HK$2.67 billion) in confiscations and fines against the two firms and their founders, penalizing them for providing securities marketing and order-processing services on the mainland without the required licenses. The heaviest impact falls on their mainland client base. Drawing on end-of-2025 figures, the two firms are expected to wind down roughly 570,000 to 630,000 mainland-funded accounts over the coming two years, collectively holding between US$27 billion and US$29 billion in assets.
This enforcement action did not arise in isolation but represents the culmination of a multi-year regulatory campaign. The CSRC first flagged the issue in October 2021 and then formally acted on 30 December 2022[2], finding that Futu and Tiger Brokers had been operating a cross-border securities brokerage business for mainland residents without the requisite CSRC licence or approval. The CSRC accordingly ordered both firms to stop onboarding new mainland clients, though existing account holders were still permitted to trade and withdraw funds.
In response, Futu and Tiger withdrew their apps from mainland app stores in mid-2023, and by September 2023 the CSRC told brokerages based in offshore jurisdictions such as Hong Kong to stop offering securities trading accounts to new mainland investors, according to a Sept. 28 notice issued by its Shanghai unit. Compliance gaps persisted over the following two years, and a parallel 2026 Securities and Futures Commission review of 12 licensed brokers uncovered continued weaknesses, including inadequate due diligence on account opening documents, acceptance of forged or questionable documentation, and insufficient verification of clients’ cross-border correspondent relationships.[3]
- The Legal Mechanism — Two-Year Rectification Plan
Alongside the enforcement action, the CSRC and seven other government departments jointly issued the “Implementation Plan for the Comprehensive Rectification of Illegal Cross-Border Securities, Futures and Fund Business Activities”[4], approved at the State Council level. The plan sets a two-year rectification period (集中整治期) to wind down existing illegal business, rather than terminate it outright.
During this period, affected brokers may only process sell orders and withdrawals — no new purchases, deposits, or account openings for mainland ID holders are permitted, and existing services cannot be expanded. Longbridge and Futu have already implemented these restrictions from 12 June 2026. Once the two years lapse, all mainland-facing platforms, apps, and servers must be fully shut down.
- Parallel Hong Kong Regulatory Action
Crucially, this was never solely a Mainland story. On the same day as the CSRC’s announcement, the SFC issued its own circular to all licensed corporations[5], referencing the CSRC’s rectification plan directly. The circular followed the SFC’s review of 12 licensed brokers, which uncovered “significant deficiencies” in account-opening due diligence and ongoing monitoring of cross-border correspondent relationships with overseas intermediaries. Some brokers had accepted questionable or forged client documents, with certain accounts later linked to suspicious fund transfers involving no genuine trading activity.
- Practical Takeaways for Clients
For SFC-licensed brokers and intermediaries, the priority is a targeted internal review: assess account-opening and beneficial-ownership verification processes for Mainland clients, verify with the clients at issue any accounts opened with questionable documentation, dormant zero-balance accounts, or accounts showing red flags such as shared addresses or bank accounts across unrelated clients. Firms should implement the SFC’s required investor declarations confirming that Mainland clients’ funds originate from lawful sources outside the Mainland. [6]
For asset managers and fintech platforms, this is a prompt to reassess any indirect subscription arrangements, nominee accounts, or omnibus structures that could be characterised as facilitating circumvention of PRC foreign exchange controls, even where the platform has no direct Mainland licensing exposure.
The SFC circular confirms that cross-border introducer arrangements do not dilute accountability, and that breaches of overseas regulatory requirements — including the CSRC’s own rules — may independently constitute a breach of paragraph 12 of the Code of Conduct, exposing licensees to SFC action regardless of the outcome of Mainland proceedings.
Non-compliance carries real consequences: the SFC has stated it has “zero tolerance” for forged documentation, and has warned it may impose external look-back reviews, restrictive licensing conditions under section 116(6) of the SFO, and formal enforcement action affecting a firm’s fitness and properness. Material breaches must also be self-reported to the SFC under paragraph 12.5(a) of the Code of Conduct.
More broadly, all cross-border businesses should treat this as a signal to strengthen senior management oversight of cross-border compliance controls on an ongoing basis, not as a one-off remediation exercise.
If you have any questions or would like to understand how these regulatory developments may impact your business or compliance obligations, please reach out to our Partner Kenneth Leung or our Associate Ronnie Tse.
This article is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
[1] China Securities Regulatory Commission. (2026, May 22). 证监会严肃查处老虎等机构非法跨境展业案件 (CSRC sternly investigates and punishes illegal cross-border business activities by Tiger and other institutions).
[2] China Securities Regulatory Commission. (2022, December 30). 中国证监会推进富途控股、老虎证券非法跨境展业整治工作 (CSRC advances the rectification of illegal cross-border business activities by Futu Holdings and Tiger Brokers).
[3] Securities and Futures Commission of Hong Kong. (2026, May 22). Circular to licensed corporations: Expected controls for account opening and maintaining relationships with clients (Ref. No. 26EC29).
[4] China Securities Regulatory Commission. (2026, May 22). 关于印发《综合整治非法跨境证券期货基金经营活动实施方案》的通知 (Notice on the issuance of the “Implementation plan for comprehensive rectification of illegal cross-border securities, futures, and fund business activities”)
[5] Securities and Futures Commission of Hong Kong. (2026, May 22). Circular to licensed corporations: Expected controls for account opening and maintaining relationships with clients
[6] Securities and Futures Commission of Hong Kong. (2026, May 22). Deficiencies identified in the Review and standards expected of licensed corporations (Appendix B).