News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
We are delighted to announce that our Partner and Head of Litigation and Dispute Resolution Department Ms. Heidi Chui has been appointed by Film Censorship Authority to the Panel Adviser from 1 July 2018 to 30 June 2019. The Panel of Advisers is established under Section 6 of the “Film Censorship Ordinance” (Cap. 392) (“FCO”) to advise on the suitability of films for public exhibition.
Ms. Heidi Chui is an Arbitrator (on the panel list of the Law Society of Hong Kong), Fellow of the Chartered Institute of Arbitrators (U.K.) and an Accredited General Mediator with both the Hong Kong International Arbitration Centre and the Law Society of Hong Kong. She is also a member of the Arbitration Committee of The Law Society of Hong Kong and a China Appointed Attesting Officer. She has been appointed as Expert of professional Committee on Real Estate Arbitration of China Academy of Arbitration Law, a Practising Solicitor Member of the Solicitors Disciplinary Tribunal Panel and a member of Disciplinary Panel A of the Hong Kong Institute of Certified Public Accountants.
Please contact Ms. Heidi Chui for any enquiries or further information.
(中文) 原告人在香港法院开展了诉讼程序,捍卫自身权益,惟被告人在香港以外的法院提出涵盖相同争议的诉讼,意图捷足先登,抢先取得有利判决,藉此阻挠原告人的香港法诉。原告人面对平行诉讼,有何法律手段阻止被告人的恶意诉讼?
在普通法下,与讼人可透过禁诉令(anti-suit injunction)机制,请求香港法庭行使酌情权,颁下禁诉令,禁止香港诉讼的与卞讼方就相同的争议在香港以外的法院开展或继续法律程序。倘若该与讼方无视禁诉令,有机会被控藐视法庭的刑事罪行。然而,出于对其他司法管辖区的礼让及尊重,香港法院一般不会轻易颁下禁诉令。本所诉讼团队处理的案件(Chen Hongqing诉The persons whose names are set out in the second column of the Schedule hereto [2018] HKCFI 1170, unreported, 2018年5月29日)中,香港高等法院以香港为合适诉讼地,以及外地诉讼属虚假及恶意诉讼为由,应原告人的申请,对若干被告人颁下禁诉令。
案件背景
约于2000年10月,随着国退民进政策出台,不少国有企业的员工得以通过员工持股计划认购企业股份,山东山水集团的员工便是一例。山水集团在香港注册成立了山水投资有限公司(下称「山水投资」),作为中国山水水泥集团有限公司(港交所:0691) (下称「中国山水」)的最大股东,而中国山水则持有山东山水水泥集团有限公司(下称「山东山水」)等子公司。该等员工拥有的52.37%山水投资股份,当时安排由张才奎以信托形式代持(下称「信托股份」)。于大约2014年,山水投资员工与张才奎就信托股份出现纠纷,于香港法院就其信托关系提起了诉讼 (下称「信托诉讼」)。原告人与时任山东山水管理层的宓敬田等人接触后,安排通过11名员工代表(下称「11名代表」),收购山水投资员工实益拥有的股份,并先后于约2015年8月至9月及2017年3月支付收购股份的代价。当时同意出售股份的员工共2,263人,其中1,014人与11名代表签署了确认函(下称「确认函」),确认原告人为股份买方,并承诺于信托诉讼中取得胜诉后,把取回的股份转让予原告人。在此过程中,宓敬田等人于山东山水的职务被解除,而济南市政府则成立了一所国企 (下称「济南国企」),声称为解决各方的争议,将主动收购员工实益拥有的山水投资股份,宓敬田则从旁协助要求员工配合国企的收购行动,签署相关文件,配合签字的员工将获赠月饼及食油等礼品。
作为已付款的收购方,原告人对济南国企的收购行动当然感到忧虑,然而因受到宓敬田等人的威胁和影响,不承认原告人收购其股份的员工人数日趋增加。有见及此,原告人在2017年11月开展了针对2,263名员工的香港诉讼 (即本案),要求法庭颁下命令,强制员工于信托诉讼取得胜诉后把相关股份转给原告人。在2017年12月初,11名代表的其中10名(同为本案被告人,下称「10名代表」)连同另一名声称为替代代表的人士(下称「声称代表」)在济南开展诉讼,要求济南法院基于他们为信托股份的真正买方(而非原告人),宣告确认函无效,企图抢先取得对其有利的判决。有见及此,原告人于2017年12月20日向香港法院提出禁诉令申请。
在2018年1月31日,员工于信托诉讼取得胜诉,意味着有关的山水投资的股份谁属,将取决于上述香港及济南两地所进行诉讼的结果。
法律原则 – 颁下禁诉令的条件
在考虑是否行使酌情权颁布禁诉令时,法庭需要首先考虑香港是否为审理当前争议的合适诉讼地,而法院一般通过以下列出的准则作出裁断:-
1. 根据本案的情况,香港法院是否并非最适合审理案件的法院,而且亦有另一个明显比香港更适合审理该案件的法院?
2. 若以上答案为「是」,法院便需考虑在另一个法院审理本案,是否会剥夺原告任何「合理的个人或司法的优势」 (legitimate personal or juridical advantages)。
3. 若以上答案亦为「是」,香港法院则须在上述第1项的好处和第2项的坏处作出平衡取舍。
倘若法庭认为香港是审理当前争议的合适诉讼地,申请人进而需要向法庭证明境外诉讼程序是无理缠扰、具有压迫性或不公正的,或者为了公正的目的,法庭需要颁下禁诉令。同时,法庭亦会考虑自身对禁诉令针对的对象是否具有管辖权。
由于禁诉令将干预境外法域的司法管辖权,申请人亦必须说服法庭颁布禁诉令的迫切性足以凌驾司法礼让原则。由此可见,法庭在考虑是否颁下禁诉令时,必会格外小心谨慎。
法院的裁定
适宜诉讼地
在本案中,由于原告人已经获得法院之前所颁下境外送达令状的命令,因此法庭认为原告至少表面上满足了香港为合适诉讼地的条件。另外,法庭亦考虑了以下因素,最终认定香港是处理及解决当前争议的明显且特别的合适诉讼地:-
1. 争议的股份属于一家香港注册的公司,且实际上涉及到另一家香港上市公司的持股;
2. 在香港存在多起围绕山水投资股份争议的诉讼,且该等股份亦正由香港法院任命的接管人托管;及
3. 由于原告人主张自己对山水投资股份的所有权,适用法律应当为管辖该等股份的法律,即香港法律。
济南诉讼是否是无理缠扰、具有压迫性或不公正
在考虑与讼双方提交的证据后,法院基于以下理由,认为存在几乎无法反驳的证据,证明10位代表及声称代表在济南诉讼中捏造案情,且他们的济南诉讼注定会失败 (bound to fail):-
1. 首先,声称代表并非11名代表之一 – 尽管他声称自己在2016年12月替代成为员工代表之一,惟并未提供任何有力的证据,证明该替换是合法进行的。无论如何,所谓替换实际上进一步支持了原告人的案情,变相佐证了11名代表都仅仅是原告人的代名人。
2. 其次,11名代表的其中一员事实上已经把自己的股份权益出售予原告人,他在济南发起诉讼的行为和他自己售卖股份的行为是完全不一致的。
3. 另外,由于代名人的事宜已经交由北京贸仲处理,原告人也已经在香港发起诉讼,济南的诉讼程序根本没有必要。
4. 最后,从时间上来看,本案的令状刚向被告人送达,10名代表及声称代表便发起了济南诉讼。显然,济南的诉讼程序有着不可告人的不当动机,目的是为了损害原告人在当前香港诉讼的权益。
胁迫和引诱
最后,法院认为本案中员工受到了胁迫和引诱,且济南诉讼存在被操纵的风险,可能损害原告人的权益,或剥夺原告人获得公平审判的权利。
基于上述理由,法院认为原告人的申请满足了颁下禁诉令的条件,因此颁下了禁诉令。
本案深远影响
禁诉令在案例中並不常见,香港法院在考虑禁诉令的申请时一般会格外小心与谨慎,一方面要顾及司法礼让原则,另一方面亦要保障申请人的合法权益。
从本案可见,当香港法院认为境外程序存在被操控的情况,而导致原告人利益被不当损害时,法院在平衡各方情況下,会颁下禁诉令,以维持公义。就香港是否合适诉讼地、境外程序是否是无理缠绕或具有压迫性、境外程序是否存在任何胁迫的成份等问题,法院皆在本案的判决中作出了详细的分析与衡量。相信在日后再出现存在各种相似复杂因素的案件,本案将可成为法院重点参考的案例,并对日后禁诉令的申请起了指引示范的作用。
本案由诉讼及爭议排解部主管徐凯怡律师、卢家俊律师、张俊燊律师及黄晊晄实习律师组成的团队,作出紧急禁诉令申请。
如阁下对本案有任何查询或想了解更多详情,请联络本所诉讼及爭议排解部主管徐凯怡律师(heidichui.office@sw-hk.com)。
免责声明:于此提供的资料只供参考,不构成法律意见,上述资料亦受制于适用案例及法例不时的更新与修改,需以当地法律律顾问的法律意见为准。
We are delighted to announce that our Partner and Head of Litigation and Dispute Resolution Department Ms. Heidi Chui has been appointed by Shanghai International Arbitration Center (“SHIAC”) to the New Panel of Arbitrators from 1st May 2018 for a term of three years.
SHIAC received 1,470 domestic and foreign applications and registration forms. After a preliminary examination by the Selection and Disciplinary Committee of SHIAC and comprehensive consideration of their professional expertise, the need for case management, professional influence of the candidates, and deliberation at the third session of the Committee, SHIAC finally selected the new Panel of Arbitrators.
Ms. Heidi Chui is an Arbitrator (on the panel list of the Law Society of Hong Kong), Fellow of the Chartered Institute of Arbitrators (U.K.) and an Accredited General Mediator with both the Hong Kong International Arbitration Centre and the Law Society of Hong Kong. She is also a member of the Arbitration Committee of The Law Society of Hong Kong and a China Appointed Attesting Officer.
Please contact Ms. Heidi Chui for any enquiries or further information.
Introduction
On 15 December 2017, Hong Kong Exchange and Clearing Limited (“HKEX”) published the Consultation Conclusions on the New Board Concept Paper (the “New Board Consultation Conclusions”), proposing a “way forward” to expand the existing listing regime. Please click here for our previous news update outlining the summary of the proposals. In gist, the Consultation Conclusions proposes: (1) to allow pre-revenue issuers engaging in biotech products, processes or technologies (“Biotech Issuers”) and innovative and high growth issuers that have Weighted Voting Rights Structure (“WVR Structure”) to list on The Stock Exchange of Hong Kong Limited (“SEHK”); and (2) to create a new concessionary secondary listing route for innovative issuers that are primary listed on a qualifying exchange.
Through discussions with the Securities and Futures Commission (“SFC”) and stakeholders, HKEX has published on 23 February 2018 a Consultation Paper on a Listing Regime for Companies from Emerging and Innovative Sectors (the “Consultation Paper”), to follow up its proposals in the Consultation Conclusions. The Consultation Paper contains detailed proposals and introduces two new chapters and certain amendments to the Rules Governing the Listing of Securities on The Stock Exchange of Hong Kong Limited (the “Listing Rules”). The proposals in the Consultation Paper closely follow the “way forward” contained in the Consultation Conclusions.
Among the updates, there are certain key new proposals worth paying attention to:
Listing of Pre-revenue Biotech Issuers
● Biotech Issuers must have developed at least one Core Product (i.e. a regulated product that forms the basis of a Biotech Issuer’s listing application under the Listing Rules) beyond the concept stage.
● Biotech Issuers must be able to show that it has been engaged with research and development of its Core Product(s) for a minimum of 12 months prior to listing.
● SEHK will recognise the US Food and Drug Administration, the China Food and Drug Administration and the European Medicines Agency as competent authorities for the purpose of assessing the Core Products of Biotech Issuers under the Listing Rules.
● Biotech Issuers must have previous meaningful third party investment from at least one sophisticated investor at least six months before the date of listing.
● Biotech Issuers listed under the new Biotech chapter will be restricted from effecting any transaction that will result in a fundamental change to its principal business without its prior consent. Further, any Biotech Issuers who fail to maintain sufficient operations or assets would be given a period of up to 12 months to re-comply with the relevant continuing obligations, failing which SEHK will cancel its listing.
Issuers with WVR Structure
● SEHK will require beneficiaries under a WVR Structure to collectively own a minimum of at least 10% and a maximum of not more 50% of the underlying economic interest in the applicant’s total issued share capital (e.g. dividend rights) at the time of the issuers’ initial listing. However, this will not be an ongoing requirement.
● Only individuals who are directors of the issuer at listing and remain as directors can be beneficiaries of a WVR Structure. The effect is that the WVR Structure would naturally fall away over time.
● The WVR Structure can only be attached to a specific class of shares, which must be unlisted.
● WVRs attached must confer to a beneficiary only enhanced voting power on resolutions tabled at the issuer’s general meetings. Beneficiaries of a WVR Structure would not be able to exercise their enhanced voting powers on matters such as to change the issuer’s constitutional documents, however framed.
Concessionary Route to Secondary Listing
● Applicants that have primary listing in the US or other major international exchanges must demonstrate, to the satisfaction of SEHK, how the combination of domestic laws, rules and regulations to which they are subject and their constitutional documents, are able to satisfy the Key Shareholder Protection Standards under section 1 of The Joint Policy Statement Regarding the Listing of Overseas Companies jointly issued by the SFC and SEHK in September 2013
● A Non-Greater China Issuer with a WVR structure or a Grandfathered Greater China Issuer with a WVR Structure who list in Hong Kong through the new concessionary secondary listing route, may not be required to comply with most new requirements applicable to issuers with a WVR Structure who list directly in Hong Kong.
Moreover, SEHK pointed out that what is considered “innovative” will change over time as technology, markets and industries develop and change. It is therefore important to note that the fact that a previous company has qualified for listing with a WVR structure does not necessarily mean that another applicant with a similar technology, innovation or business model will also qualify for listing with a WVR structure.
Conclusions
The quick publication of detailed proposals and draft amendments to the Listing Rules show HKEX’s commitments to reform the listing regime to offer more choices for emerging and innovative companies to list in Hong Kong. To show HKEX’s receptiveness to suggestions, the Consultation Paper further proposes that if the amendments related to WVR are implemented, HKEX will launch a separate consultation within three months of such implementation to explore on whether to allow corporate entities to become beneficiaries of a WVR Structure. In light of these encouraging developments, we all look forward to seeing Hong Kong continue to be an attractive venue for raising capital.
This newsletter is for information purposes only. Its content does not constitute legal advice, and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage.
Please contact our Hank Lo or Rodney Teoh for any enquiries or further information.
(中文) 史蒂文生黄律师事务所合伙人徐凯怡律师及张源辉律师,联同公共关系部经理叶慧珍小姐于2018年3月22日到访锦天城南京分所参观交流,双方就诉讼及仲裁和资本巿场(上市及收购合并)等议题举行交流座谈会,并获多位南京分所同仁热切款待,包括南京分所主任倪同木律师、高级合伙人奚庆律师、何海军律师、张宇坤律师、王芳律师、王小晶律师、刘嘉豪资深律师、以及南京分所行政主管吴小红女士等。
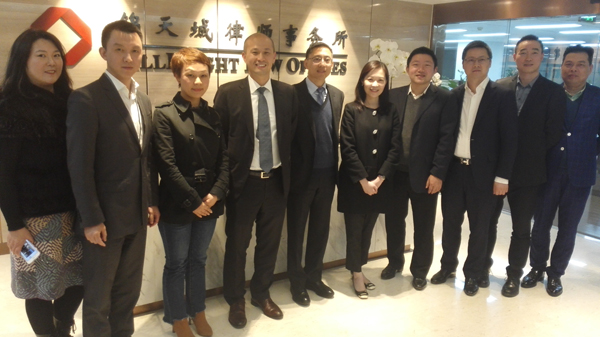
交流会由锦天城高级合伙人张宇坤致欢迎词掀开序幕,奚庆律师也介绍了南京分所的专业领域。
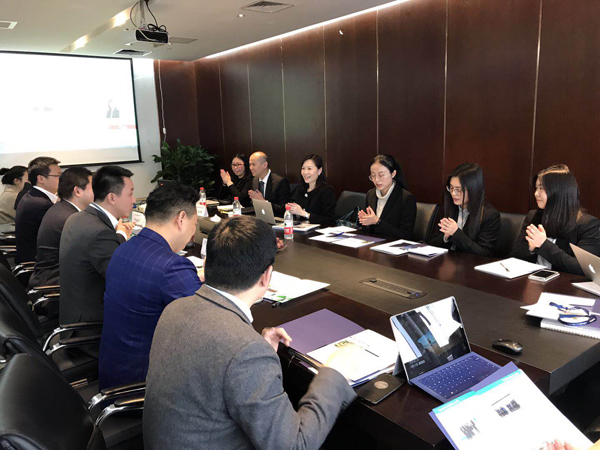
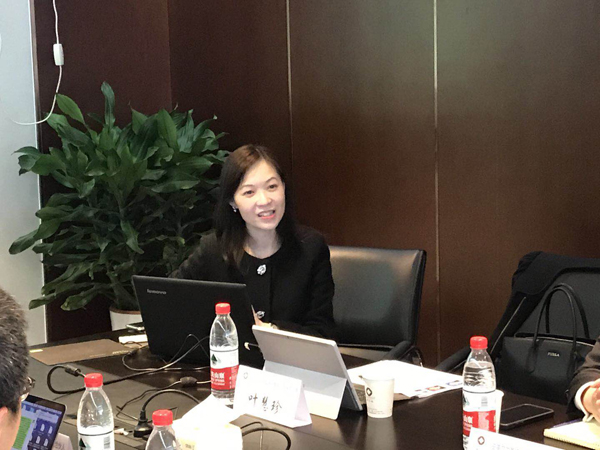
本所合伙人、诉讼及争议排解部门主管徐凯怡律师在交流会上就「跨境诉讼与仲裁」发表演讲。徐律师利用不同的案例,深入浅出地向大家阐述跨境诉讼与仲裁的各种情况,并互相讨论。徐律师更向大家分享第三方资助仲裁的最新发展。
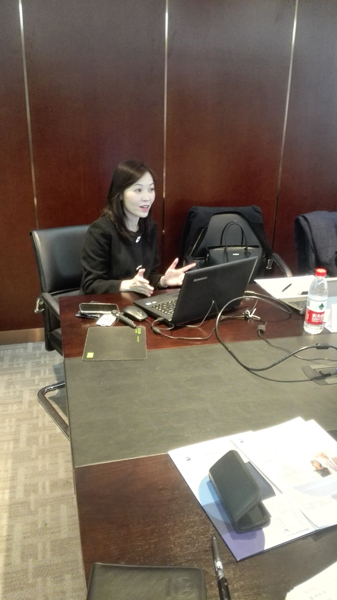
另外,合伙人张源辉律师也介绍了本所企业融资部门的团队及业务,也分享了本所在去年处理上市及收购合并的项目。
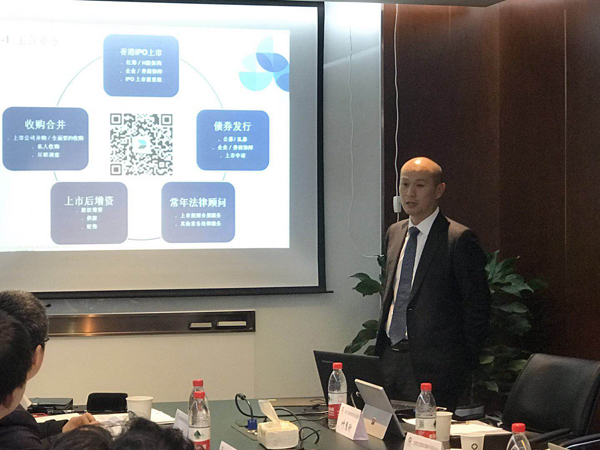
最后,南京分所主任倪同木律师肯定了这次交流会的成果,对本所的到访与分享表示感谢,期待未来两所有更多合作,并祝愿两所有更好的发展。
In July 2017, Mr. Ashley Alder, the Chief Executive officer of the Securities and Futures Commission (“SFC”) introduced a new approach to regulate licensed corporations, listed companies and companies that are applying to be listed on the Stock Exchange of Hong Kong. This new approach, often called the “front-loaded regulation”, aims to identify risks and minimise harm to the investing public from market misconduct and irregularities. It places a strong emphasis on “earlier, more targeted intervention”.
Conventional approach
There are three main arms of the SFC’s regulatory work. The first arm is education. The SFC would issue reports, circulars and guidelines periodically to provide regulatory guidance for the investing public, companies (listed and non-listed), and licensees. The second arm is the Intermediaries Division, which carries out licensing and supervisory functions. Regarding its supervisory role, it acts as a ‘good cop’ to perform regular inspections on regulated licensees with a view to protect the investing public. When material irregularities are found during inspections, the Intermediaries Division would refer the case to the Enforcement Division. The final arm is the Enforcement Division, which takes criminal, civil and disciplinary actions against offenders following investigations into the alleged irregularities or market misconduct.
Issues with the conventional approach
Traditionally, the SFC has primarily relied on the Enforcement Division to carry out its regulatory enforcement functions. On top of that, enforcement powers may only be exercised through a Court or the Market Misconduct Tribunal (“MMT”). This approach can be very time-consuming because all sanctions and remedies were dependent on the approval from the Court or MMT. Once the Intermediaries Division has referred a case to the Enforcement Division, the Enforcement Division would carry out further in-depth investigation into the alleged irregularity before commencing proceedings. The ensuing proceedings in the Court or MMT would also take a considerable amount of time.
Moreover, the transition of cases from the Intermediaries Division to the Enforcement Division may not always be smooth, due to the difference in their investigation approach and evidence gathering methodology causing unnecessary delay that may risk losing the opportunity for timely fact-finding. As a result, the irregularities or market misconducts might usually be needlessly prolonged.
New approach – “early intervention”
Under the new approach, the SFC will take pre-emptive measures to tackle market irregularities and “interact directly with the market at an early stage”.
In terms of administrative measures, the Intermediaries Division will now issue more thematic guidance to licensees and companies on how the SFC intends to deal with specific issues under the Securities and Futures Ordinance (“SFO”) and the Securities and Futures (Stock Market Listing) Rules (“SMLR”). Such thematic guidance will require licensees and companies to conduct internal control reviews regularly to check for irregularities. The active review will be done by the company/licensee so that irregularities can be identified and dealt with immediately.
The SFC may also issue a restriction notice pursuant to ss. 204 and 205 of the SFO. This gives the SFC powers to prohibit the targeted company or licensee from carrying out specific regulated activities that would create irregularities. The issue of restriction notice aims to preserve the assets of the licensee and its clients, and protect the interest of those clients and the investing public. While the SFC has been issuing restriction notices long before the adoption of the new approach, we can expect the SFC to exercise such powers more readily in the future in light of the new approach.
Regarding the disciplinary actions and proceedings brought by the Enforcement Division, the SFC will now be able to exercise enforcement powers without prior approval from the Court/MMT. Under the SMLR, the SFC could suspend a listed company without the need to seek Court approval. The SFC has indicated that it would use such power of suspension as an “exceptional early protective action” during an investigation pending further investigation or legal action.
Furthermore, the SFC will now give credit to the people and/or licensees who are willing to cooperate with the SFC in their investigations. Forms of cooperation may include, inter alia, voluntarily and promptly reporting any breaches or failings to the SFC, acceptance of liability, and taking rectification measures. In both disciplinary matters and Court/MMT proceedings, the SFC may reduce the sanctions imposed if the person/licensee is cooperative. In particular, the SFC has divided its disciplinary process into three stages, with sanction reduction up to 30%, 20% and 10% respectively. These changes to the SFC’s cooperation policy may give rise to more constructive solutions in resolving irregularities, while keeping the daily operations of the company intact. These benefits should help to provide more incentive for people and licensees to cooperate with the SFC.
Overall, the Intermediaries Division will be more proactive in exercising its supervisory powers, meanwhile, the Enforcement Division will only focus on the most serious issues, such as fraud and corporate misfeasance, which would have serious ramifications to the integrity of the capital markets of Hong Kong.
Implications to companies: the changes that will affect your business
The new approach may increase the efficiency of the SFC in handling investigations into the irregular conduct of licensees, companies, and also individuals. The cooperation between the SFC and the licensed entities is also going to be tighter.
However, this approach may also cause the compliance cost of licensees and companies to soar. Licensees and companies may need to conduct excessive internal reviews and monitoring in order to meet the requirements of the regulators, albeit there may not be any material findings on any misconducts.
The lack of universal standards for internal reviews conducted by licensees and companies may also be problematic, as the standard of review would vary from one licensee/company to another, making it difficult for licensees and companies to fully understand how to comply with the SFC’s requirements.
The expansion of enforcement powers of the Intermediaries Division may also be seen as a misplacement of resources. In essence, the roles of the Intermediaries Division and the Enforcement Division are distinct. The “front-loaded” approach delegates more enforcement power to the Intermediaries Division, despite the fact that the Division may not have enough expertise to conduct thorough investigations and obtain material findings for imposing preliminary sanctions.
To tackle such changes, listed companies and regulated activities licensees should be prepared that the SFC may take aggressive strategies to handle any irregularities spotted even at an early stage when the Enforcement Division has not been engaged. Professionals should be engaged to conduct ‘health checks’ on the entities’ internal control on a regular basis.
What we can provide to help you
Key contact
Stephen Wong
Partner
Tel: +852 2533 2525
Email: stephenwong.office@sw-hk.com