
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
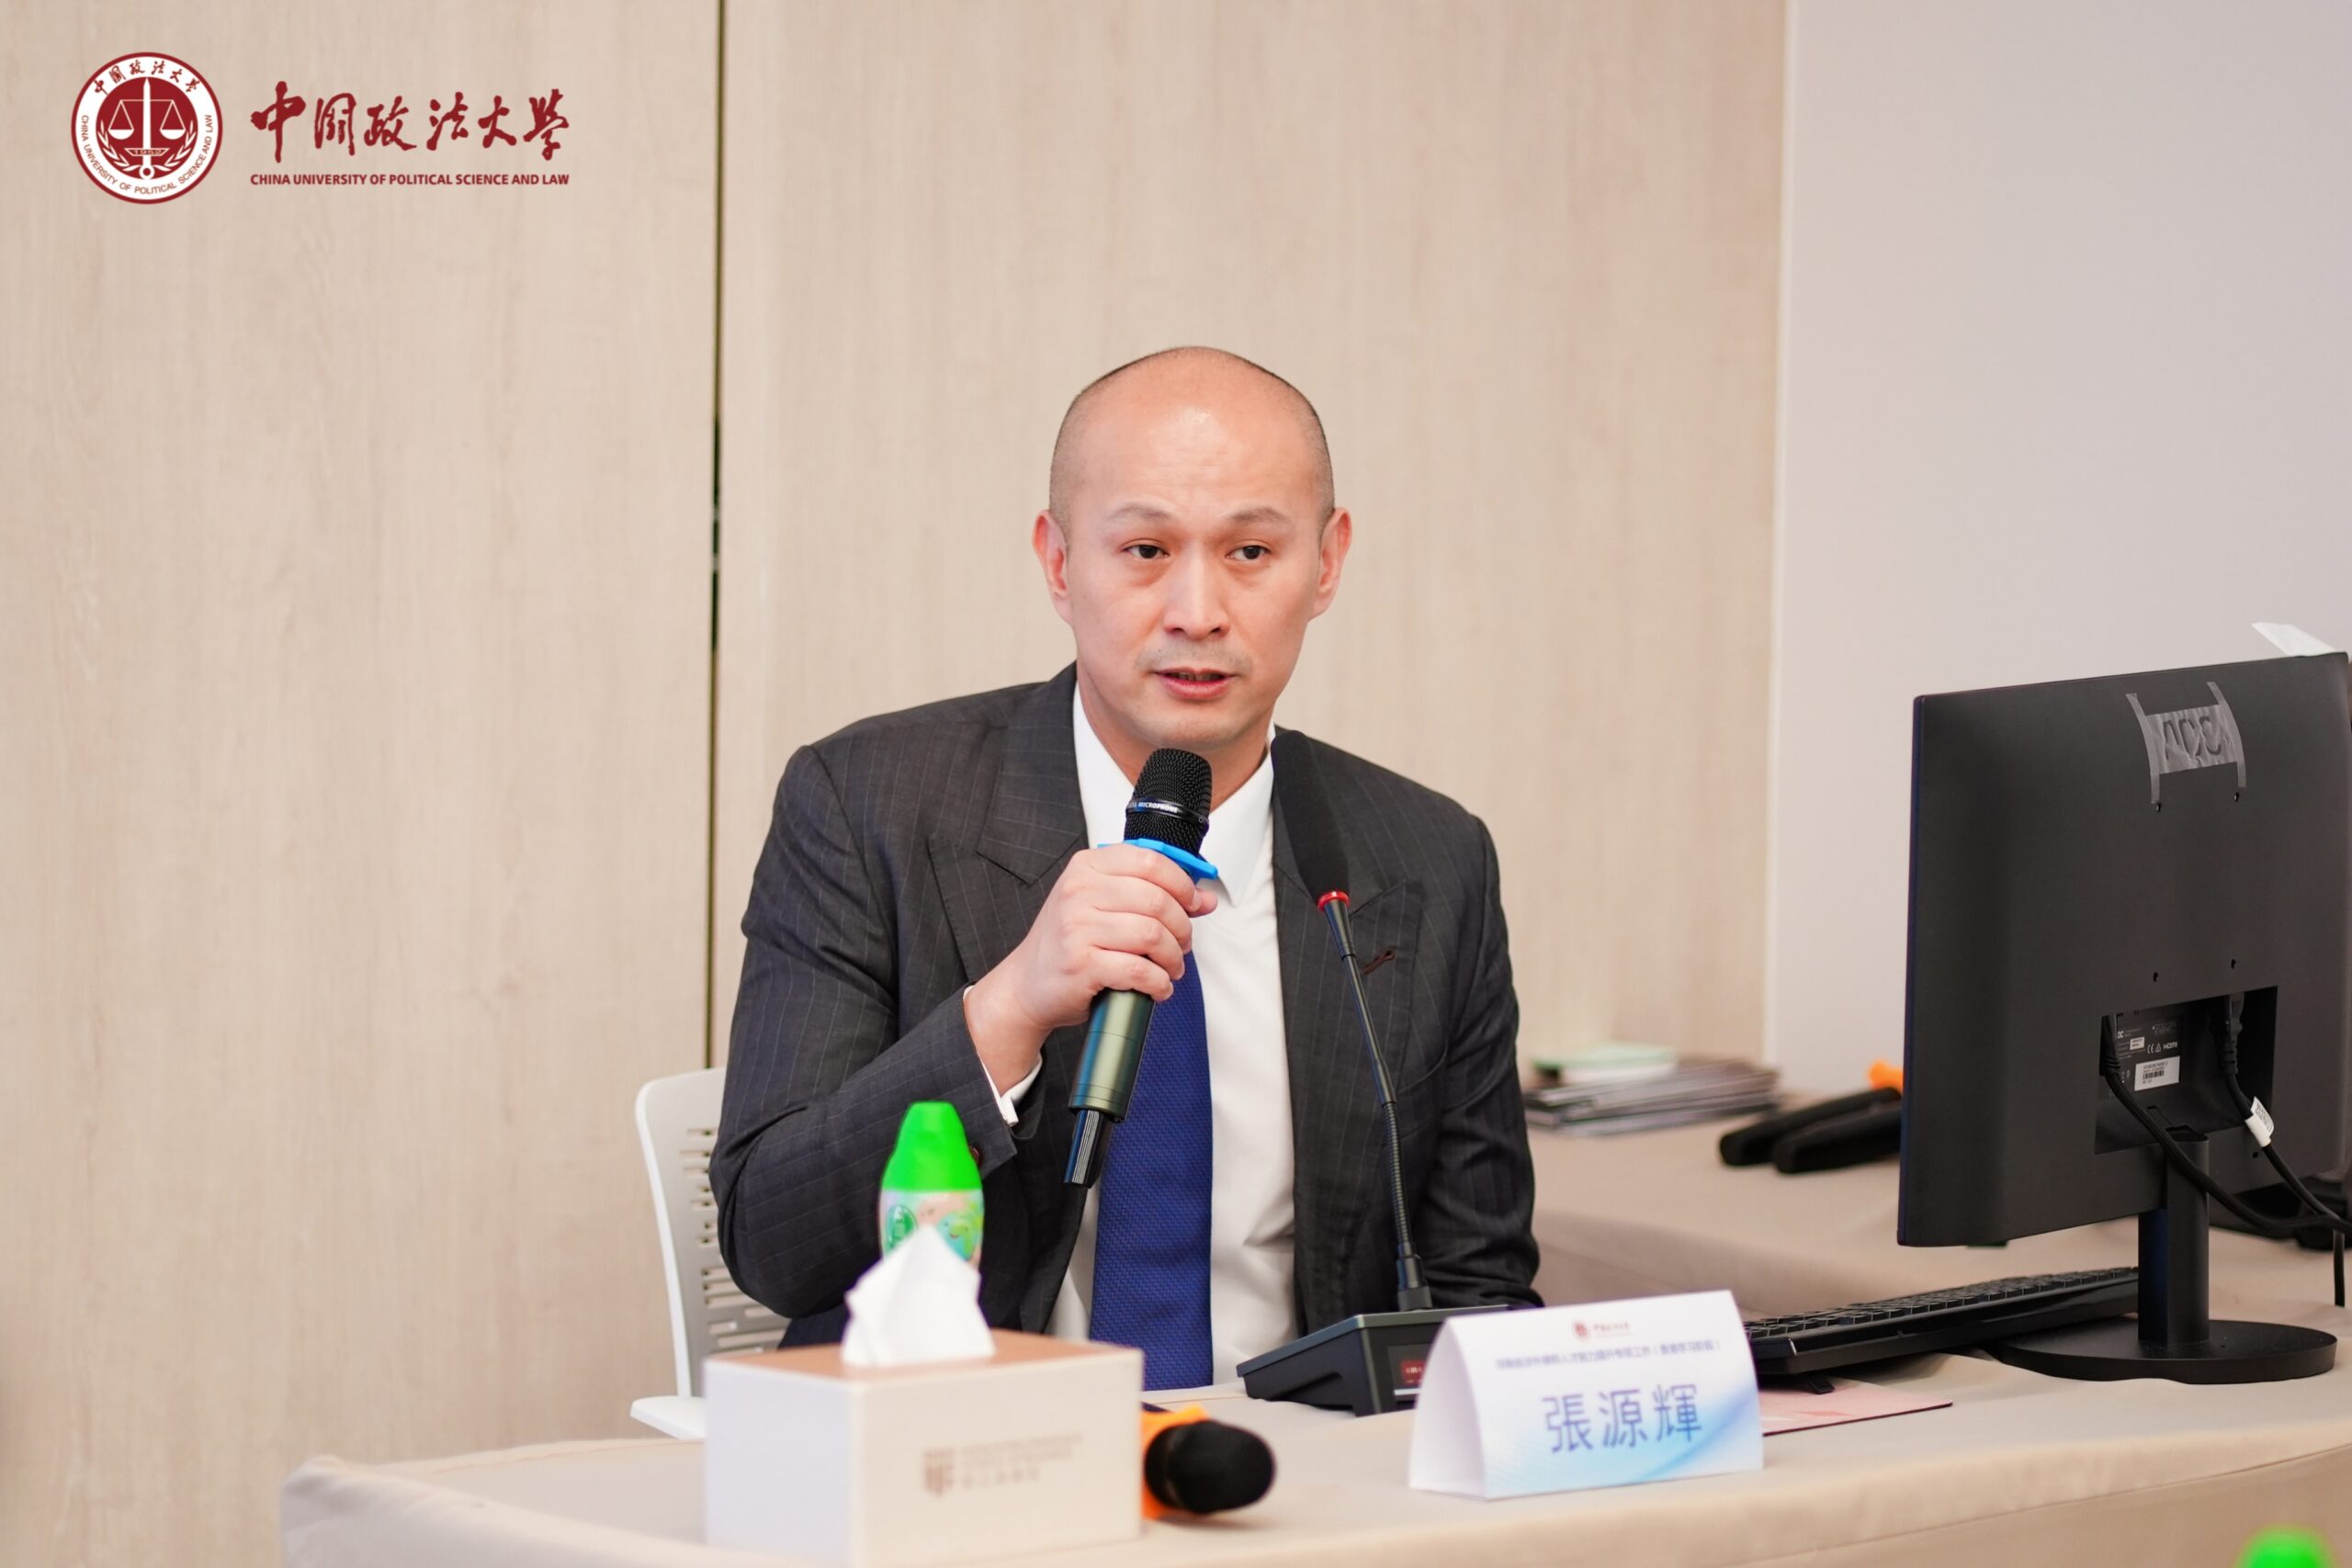
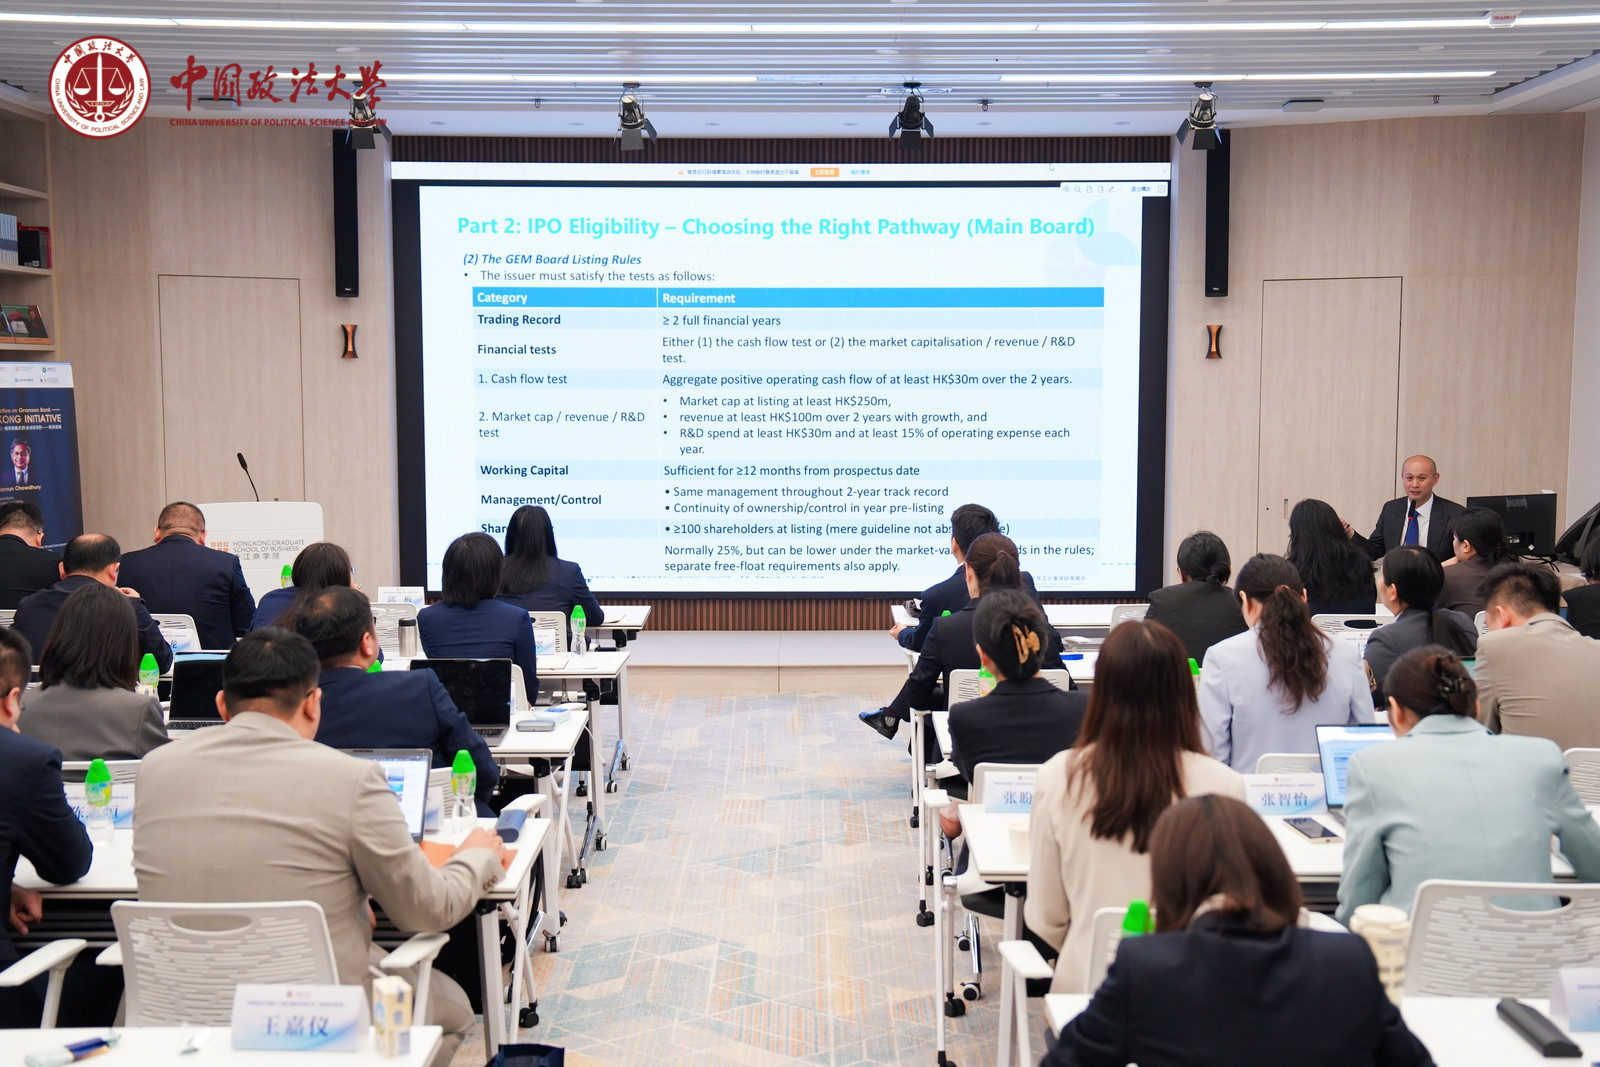
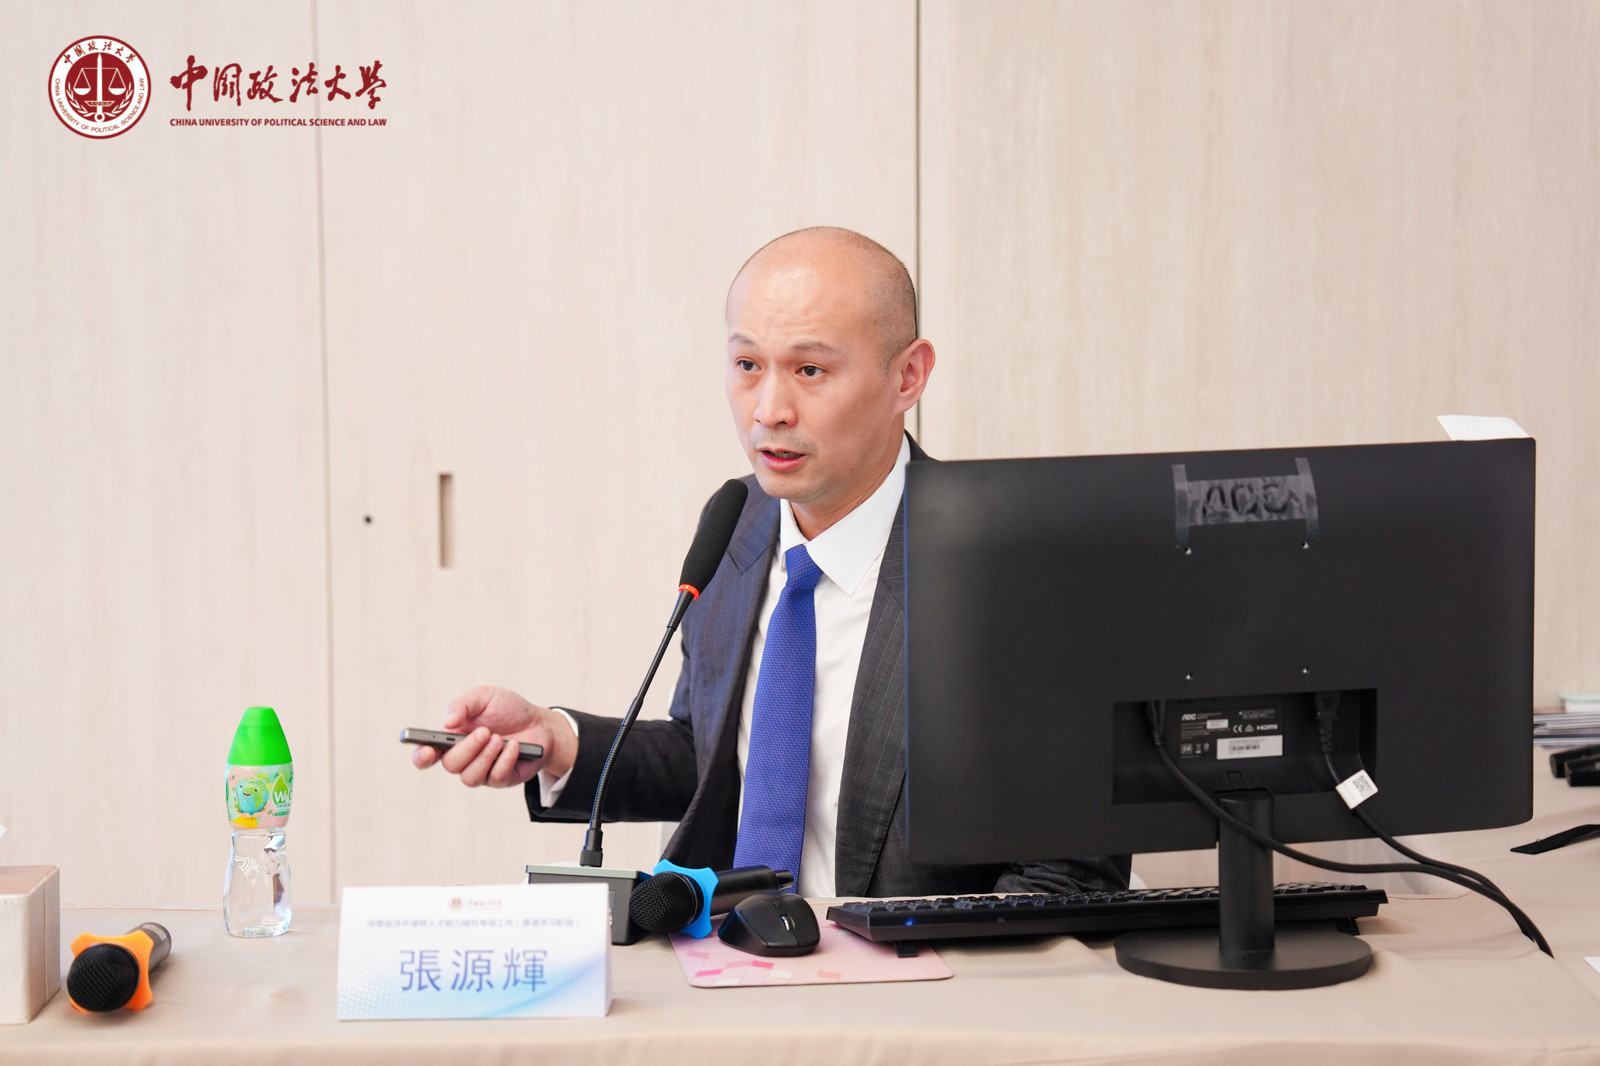
(中文) 2026年4月24日,本所合伙人、企业融资副主管及金融科技联席主管张源辉律师应中央政法培训学院邀请,担任由中国政法大学「中央政法培训学院」与河南省律师协会联合主办的“涉外律师人才能力提升专项工作培训班”讲师,为来自河南省的涉外律师人才进行专题授课。
 …
本次培训班面向企事业单位、律师、公证员、仲裁员等各领域在职法律人才,旨在提升涉外法律服务队伍的专业能力,增强跨境法律服务的实务水平,推动涉外法治人才培养体系建设。
在授课中,张源辉律师以《涉外律师跨境金融业务实务:跨境融资、国际债券发行与金融监管合规》为题,结合其在香港及国际金融市场多年的实务经验,系统讲解了跨境融资结构设计、国际债券发行的法律要点与流程、以及当前全球主要金融监管框架下的合规挑战与应对策略。张律师通过实际案例分析,深入剖析了香港律师在跨境金融交易中的角色,获得了与会学员的高度评价。
 …
The Hong Kong initial public offering (IPO) market has experienced a resounding resurgence. Following a robust 2025 that saw more than 460 new listing applications and over 110 successful listings raising approximately HK$286 billion,[1] the momentum has carried fiercely into the first quarter of 2026. With 40 new listings raising nearly HK$109.9 billion in Q1 alone, Hong Kong has reclaimed its position as the premier global listing venue.[2]
However, this quantitative triumph has unmasked significant qualitative vulnerabilities. Amid the surge in new listing applications in 2025, the Securities and Futures Commission (“SFC”) and The Stock Exchange of Hong Kong Limited (“SEHK”) have observed the declining quality of draft listing documents as well as certain substandard conduct of licensed corporations carrying out sponsor work (“Sponsors”).
In response, the SFC issued a sternly worded circular on 30 January 2026 (the “Circular”), putting the industry on notice. The message is clear: the pursuit of market share must not come at the expense of substantive due diligence.
The Market Reality: Compromised Quality and “Process-Driven” Due Diligence
The SFC has expressed concern that some Sponsors may be adopting a process-driven approach to listing applications, rather than one focused on substantive due diligence and advisory services. This regulatory concern is supported by specific examples of substandard conduct highlighted by the SFC.
As highlighted in the Appendix to the Circular:-
In the Circular, the SFC outlines the specific areas of concern as follows:-
The “Strained Principal”
As of 29 January 2026, there were over 420 active listing applications in the pipeline. This massive workload is disproportionately concentrated among a small fraction of the market’s eligible Principals, sparking a fight for talent as Sponsors scramble to meet regulatory capacity limits. The SFC noted a concerning number of Principals simultaneously undertaking six or more active listing engagements.
The SFC has drawn a hard line on capacity. The SFC now sees any Sponsor that has designated any Principals to simultaneously supervise or participate in six or more active listing engagements (Sponsors with Strained Principal(s)) as lacking adequate resources to carry out sponsor duties, unless under very exceptional circumstances. For the first time ever, the SFC expressed an expectation that a Principal should take on up to five active engagements.
To enforce this, the SFC required all Sponsors to submit the names and number of appointed Principals and the number of active listing engagements each is engaged in. Going forward, new licence applications for individuals intending to engage in Type 6 IPO sponsor work must include a document signed off by all Managers-In-Charge of the Overall Management Oversight (OMOs) confirming compliance with the five-engagements capacity limit.
Stringent Remedial Actions and Vetting Suspensions
The SFC and SEHK are shifting from issuing warnings to taking direct supervisory and enforcement actions. In December 2025, they issued a joint letter to 13 specific Sponsors citing concerns over recent listing applications. These “Concerned Sponsors” and any Sponsors with Strained Principal(s) should expect the SFC to conduct on-site thematic inspections of their sponsor work and resources in the near future.
Furthermore, the SFC has equipped itself with immediate deterrents during the application phase:
Elevated Competency and Examination Thresholds
As noted above, some Sponsors fielded teams with over 40% of staff having less than one year of local IPO experience. In response, the SFC has tightened examination requirements. All individuals engaging in IPO sponsor work must now pass HKSI LE Papers 1 and 16 not more than three years before their first engagement in IPO sponsor work, unless otherwise exempted. Sponsors must report any non-compliant staff.
Management’s Responsibilities
While a Sponsor’s management may delegate operational functions to its staff, management is ultimately responsible for supervising sponsor work and ensuring compliance with all relevant legal and regulatory requirements.
In case of serious failures, the SFC may take regulatory actions including restricting the Sponsors’ business scope or the number of active listing engagements the Sponsors can undertake. The SFC may also commence investigation and/or disciplinary action in serious cases of misconduct against the Sponsor and its Principals as well as Management who are accountable for the Sponsor’s failures.
So what should Sponsors do now?
At Stevenson, Wong & Co., our Regulatory and Litigation team possesses extensive experience in advising licensed corporations on SFC compliance, inspections, and remediation. Should you require strategic counsel on assessing your firm’s sponsor resources or navigating an impending SFC inspection, please contact our Partners Rainbow Ip or Kenneth Leung.
This article is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
[1] According to the Circular, from 1 January to 31 December 2025, more than 460 new listing applications were received by the regulators. The Circular also notes that during this same period, there were over 110 successful listings which raised approximately HK$286 billion. See https://apps.sfc.hk/edistributionWeb/api/circular/openFile?lang=EN&refNo=26EC4.
[2] Based on market data reported by KPMG China in their Q1 2026 review, Hong Kong’s IPO market raised HK$109.9 billion across 40 new listings in the first quarter. See https://kpmg.com/cn/en/insights/2026/04/china-hk-ipo-2026-q1-review.html.
 …
Institutional Upgrade for the “First Mile” of Cross-Border Litigation: New
Arrangement on Service of Judicial Documents in Civil and Commercial Matters
between the Mainland and Hong Kong
On 20 April 2026, the Supreme People’s Court of the People’s Republic of China and the Government of the Hong Kong Special Administrative Region signed the Arrangement on Mutual Service of Judicial Documents in Civil and Commercial Proceedings between the Mainland and the Hong Kong Special Administrative Region (the “New Arrangement”) in Beijing. The New Arrangement addresses a fundamental step in cross-border civil and commercial litigation that often determines whether a case can proceed: the effective service of judicial documents on parties located in the other jurisdiction.
In cross-border litigation, the valid service of judicial documents directly affects whether proceedings can commence, whether procedures are valid, whether a case can proceed, and whether subsequent judgments can be enforced. The New Arrangement will substantially improve the channels and methods for Hong Kong parties to serve judicial documents on addressees in the Mainland.
As background, the 1999 Arrangement for Mutual Service of Judicial Documents in Civil and Commercial Proceedings between the Mainland and Hong Kong Courts (the “Old Arrangement”) has been in force for more than two decades. Over this period, the number of cross-border cases between the two jurisdictions has risen markedly. As the Secretary for Justice of Hong Kong informed the Legislative Council on 27 April 2026, applications for mutual service of judicial documents increased from 359 in 1999 to 2,388 in 2024.
Under the Old Arrangement, Hong Kong judicial documents could only be served in the Mainland through entrusted service, giving rise to practical problems such as inaccurate service addresses, multiple layers of entrustment, and lengthy delays. A typical pain point was that even when a seemingly valid address was known, it could not be used in the entrusted procedure due to misalignment between entrusted documents, address details, and service rules, undermining litigation efficiency.
The New Arrangement therefore comprehensively upgrades the Old Arrangement to tackle these pain points. Its core objectives are to diversify service methods, shorten service pathways, raise success rates of service, and maintain judicial supervision and procedural safeguards for addressees while improving efficiency.
For service of Hong Kong judicial documents in the Mainland, the Old Arrangement offered only a single channel: entrusted service, which had clear limitations in efficiency and flexibility.
The New Arrangement retains entrusted service. In addition to the existing mechanism where higher people’s courts of the Mainland and the High Court of Hong Kong may mutually entrust service, and the Supreme People’s Court may directly entrust the High Court of Hong Kong, it adds a mechanism under which the Supreme People’s Court may authorize certain intermediate and primary people’s courts to mutually entrust service with the High Court of Hong Kong.
This means some cases will no longer need to be escalated to higher people’s courts before transmission to Hong Kong courts, shortening the procedural chain. For numerous contract, corporate, financial, and trade disputes heard by primary or intermediate people’s courts in the Mainland, service requests can connect more directly with Hong Kong courts once the relevant courts are authorized, reducing transmission time and information loss.
The New Arrangement keeps entrusted service and explicitly permits postal service, electronic service, and service by authorized entities as mutually recognized methods. If multiple methods are used simultaneously, service is deemed completed on the earliest effective date. These methods align better with commercial practice where legally required and court-approved.
(1) Postal Service
Article 13 provides that when a Mainland people’s court serves judicial documents on a Hong Kong addressee by post, it shall attach an acknowledgment of service. When a Hong Kong court serves documents on a Mainland addressee by post, it shall provide an original sealed judicial document and an acknowledgment or other proof for the addressee’s signature. Service is deemed complete on the date of signature on the proof; signature on the postal receipt without signing the proof also constitutes valid service.
Postal service becomes a formal cross-border channel with clear proof and timing rules, offering low cost, direct operation, and predictable timing—especially suitable for cases with confirmed addresses and low risk of evasion of service.
(2) Electronic Service
Article 14 allows electronic service via verifiable means where the addressee expressly consents, voluntarily provides an electronic address for service, or accepts service by responding or participating in proceedings. Eligible media include fax, email, mobile communication, and other instant-receipt systems. This is critical for cross-border commercial entities relying on digital communication, shifting the focus from physical delivery to verifiable receipt.
(3) Service by Authorized Entities
Article 15 states that a Mainland people’s court may, upon review, allow a party to arrange service via a Hong Kong law firm or registered foreign law firm if not prohibited by law. Conversely, Hong Kong parties may serve Mainland addressees through Mainland law firms or notary public institutions. Local legal and notary professionals are familiar with address verification, service documentation, and evidence preservation, boosting success rates and procedural compliance.
(4) Service by Public Notice
Article 17 permits service by public notice if other methods fail. Mainland courts shall publish notices on influential online platforms in both jurisdictions; Hong Kong courts may entrust Mainland courts to assist with public notice service in the Mainland when necessary. Service is deemed complete 60 days after publication, providing a fallback for missing or evasive addressees and preventing cases from stalling.
In sum, parties may design a tailored service strategy combining postal, electronic, authorized-entity, and other methods under the New Arrangement.
III. Practical Implications of the New Arrangement
Notably, the New Arrangement has been signed but not yet entered into force. It will take effect following the issuance of relevant judicial interpretations by the Supreme People’s Court and completion of local legislative amendments in Hong Kong, with the effective date to be jointly announced. The Old Arrangement remains applicable in the interim.
Conclusion
The New Arrangement is a major procedural upgrade to cross-border judicial assistance between the Mainland and Hong Kong. It does not alter substantive laws or directly govern recognition and enforcement of judgments, but resolves the core bottleneck of difficulty in service—the most common and delay-prone step in cross-border litigation.
For enterprises and high-net-worth individuals, the revised service regime may accelerate cross-border litigation timelines and narrow procedural defenses, elevating the importance of evidence documentation and compliance. Once in force, parties should integrate service strategy into overall litigation planning at an early stage, rather than reacting passively after proceedings start. Parties in Hong Kong seeking to serve Mainland addressees may combine multiple service methods to improve success and gain procedural advantage.
This article was co-authored by Partner and Head of Litigation and Dispute Resolution, Heidi Chui, Cross-border Practice Director, Stephen Wong, Associate Victor Zhang. For further inquiries or more details, please contact our Heidi Chui.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
News Update:
The Hong Kong Fintech Promotion Blueprint – The Acceleration of Adopting Emerging Financial Technologies
28 April 2026
Introduction
The Hong Kong Monetary Authority (“HKMA”) has released a comprehensive Fintech Promotion Blueprint in February 2026 setting out concrete measures to push Hong Kong’s banking sector from broad, basic use of digital tools into deeply embedded, sophisticated financial technology across core operations.
From “All Banks Go Fintech” to Advanced Adoption
The Blueprint builds on the HKMA’s “Fintech 2030” strategy and the earlier Fintech Promotion Roadmap, which helped banks digitise front‑to‑back operations under the “All Banks Go Fintech” initiative. Comparing data from 2022 to 2025, 95% of surveyed banks – including all retail banks – had adopted fintech for end‑to‑end digitalisation, with particularly high uptake in Regtech (from 83% to 97%), Insurtech (28% to 57%), Greentech (26% to 45%) and Wealthtech (43% to 52%). Banks are also increasing investment: 36% have allocated more than 30% of their technology budgets to fintech, 95% have planned to maintain or increase these levels over the next three years, and half have expected budget growth of 10 – 20%.
Yet the HKMA notes that most institutions still deploy fintech as standalone tools which neither fundamentally re‑engineer processes nor integrate into core operating models, thereby limiting return on investment and slowing more ambitious adoption. The new Blueprint therefore shifts the emphasis from breadth to depth, aiming to move the industry towards “Advanced” maturity, where fintech is embedded in day‑to‑day operations and delivers tangible business value.
Five Pillars: A.I., DLT, HPC, Data and Cyber
The Blueprint is structured around five priority enablers and foundations: Artificial Intelligence (“A.I.”), Distributed Ledger Technology (“DLT”), High‑Performance Computing (“HPC”), Data Excellence, and Cyber Resilience.
Artificial Intelligence
Hong Kong’s financial sector is entering a new phase of A.I., progressing from traditional models used for fraud detection and credit scoring towards Generative A.I. (“GenA.I.”) and agentic A.I. GenA.I. is already powering applications such as anti‑money laundering systems that analyse transaction narratives and communications, and conversational agents that autonomously handle customer queries, supported by the HKMA’s GenA.I. Sandbox. Agentic A.I., emerging since 2025, enables autonomous monitoring, decision‑making and execution, for example real‑time fraud prevention that can freeze accounts or multi‑agent loan approval processes that coordinate risk assessment, identity verification and disbursement.
However, institutions report significant barriers: limited revenue‑generating use cases, concerns around accuracy and “hallucinations” (plausible yet factually incorrect outputs), integration with fragmented legacy systems, decentralised data, and acute talent shortages that combine technical, regulatory and business skills. Smaller banks lag behind their larger peers in adoption, with only 63% of small firms using A.I. compared with 83% of large firms. The Blueprint prioritises industry‑wide knowledge exchange, targeted upskilling, expanded sandbox use and shared infrastructure to enable safe, scalable and impactful A.I. adoption.
Distributed Ledger Technology
DLT is framed as a driver of tokenisation and next‑generation payments by providing shared, synchronised ledgers that support faster, more secure transactions and asset tokenisation. The Blueprint cites live examples including the HKSAR Government’s tokenised Green Bonds and the HKMA’s e‑HKD+ initiative, as well as Project Ensemble, a sandbox for cross‑boundary settlement in tokenised deposits, and the Supervisory Incubator for DLT.
Despite this progress, banks face heavy integration costs with legacy systems, interoperability and scalability constraints, smart‑contract and private‑key risks, difficulties in reversing fraudulent immutable transactions, and regulatory uncertainty over digital asset classification and smart‑contract enforceability. The HKMA therefore sets promotion priorities around sharing concrete integration strategies and commercially successful use cases, building production‑level skills (especially in smart contracts), and working towards clearer standards on asset classification, security baselines and preferred network architectures to support scalable and interoperable deployments.
High‑Performance Computing
HPC – including supercomputing and quantum computing – is positioned as critical infrastructure for advanced modelling, A.I. and risk analytics. Supercomputers can already support intensive risk simulations, portfolio stress‑testing and quantitative trading strategy optimisation, while also providing compute for GenA.I. workloads, for example via Cyberport’s A.I. Supercomputing Centre. Quantum computing is highlighted for its potential in portfolio optimisation, scenario analysis, product pricing and fraud detection, but also for the threat it poses to current cryptography.
Adoption is hampered by high cost, lack of supporting infrastructure, energy and cooling demands, and specialised talent gaps, with some smaller banks not exploring HPC at all. The Blueprint therefore calls for shared supercomputing facilities, broader literacy on supercomputing and quantum concepts, and early integration of post‑quantum cryptography (“PQC”) to address “harvest now, decrypt later” risks.
Data Excellence
Data Excellence is identified as a core foundation for A.I., DLT and advanced risk management, but many banks struggle with incomplete and inconsistent datasets locked in fragmented legacy systems. Batch‑oriented mainframes, non‑standard formats and isolated repositories prevent unified customer views, real‑time monitoring and high‑quality model training, while growing volumes of unstructured and cross‑border data add complexity.
The Blueprint calls for structured programmes to share best practices in managing structured and unstructured data, governance frameworks for internal and external data use, and sector‑wide standards on interoperability, formats and validation to improve availability, quality and sharing of risk data.
Cyber Resilience
As advanced fintech deployments demand large, granular datasets, cyber and privacy risks intensify. The Blueprint highlights adversarial A.I. attacks (such as poisoned training data, prompt‑injection, and deepfakes), smart‑contract bugs and oracle manipulation in DLT, and quantum‑enabled cryptographic threats, compounded by multi‑layered third‑party supply chains in cloud, data and platform services. HKMA’s priorities include stronger governance of third‑party risks, sector‑wide sharing of threat intelligence and defensive practices, and definition of baseline expectations for cyber standards in advanced fintech solutions.
Market Landscape: Adoption Progress and Pain Points
The Blueprint describes a rich fintech ecosystem in Hong Kong comprising fintech firms, financial institutions, regulators, investors, industry associations, academia and the public, all connected through platforms such as Fintech Connect, the FiNETech event series, the Commercial Data Interchange (“CDI”), GenA.I. Sandbox and the Supervisory Incubator for DLT. Government grants, the Digital Bond Grant Scheme, and Cyberport and HKSTP incubation programmes further de‑risk adoption and support solution development.
Despite this, the Tech Maturity Stock‑take identifies persistent barriers: 75% of banks cite high implementation costs, 73% highlight risks associated with new technologies, 71% struggle with integration into existing systems, 61% worry about data privacy and cybersecurity, and 59% report regulatory uncertainty and talent shortages. These challenges, especially for smaller institutions, reinforce the need for tactical and coordinated measures – the core focus of the new Blueprint.
Key Priorities: From Use Cases to Standards
Drawing on its research and engagement, the HKMA distils five priority directions that underpin the Blueprint’s design:
These priorities feed into a Blueprint architecture with three strategic dimensions – (1) Ecosystem Collaboration, (2) Technological Advancement and (3) Talent & Outreach – each populated with concrete initiatives.
Blueprint Design 1: Ecosystem Collaboration
Beyond the flagship projects, the Blueprint sets out a series of ecosystem initiatives designed to increase connectivity and reduce search and coordination costs in the market:
These measures are designed to transform current bilateral engagements into a more structured, data‑rich collaboration fabric that helps banks find credible partners and scale proven solutions more quickly.
Blueprint Design 2: Technological Advancement
Under the Technological Advancement dimension, the HKMA will deploy multiple content‑based and engagement‑based tools that translate complex technologies into implementable blueprints for banks:
These initiatives aim to turn abstract innovation narratives into practical, repeatable models that banks can adapt and deploy in their own environments.
Blueprint Design 3: Talent and Outreach
To ensure human capital keeps pace with the technology push, the Blueprint extends the HKMA’s talent and outreach agenda:
These measures are intended to progressively raise the baseline of technical and practical competence across the industry, enabling institutions to adopt and govern sophisticated fintech safely.
Measuring Impact and Next Steps
To ensure the Blueprint translates into concrete results, the HKMA will monitor progress at both initiative and programme levels. Initiative‑level metrics will track engagement and behavioural changes, while programme‑level assessment will evaluate systemic progress across Ecosystem Collaboration, Technological Advancement and Talent & Outreach, allowing the HKMA to recalibrate actions as market conditions evolve.
The HKMA will kick off implementation with a FiNETech event on Data Excellence in the second quarter of 2026 and will continue to refine the initiatives through active engagement with banks, technology firms and other regulators. Ultimately, the Blueprint positions Hong Kong to move from foundational fintech adoption to strategic technological leadership, using targeted, tactical measures to accelerate the uptake of advanced, responsible financial technology across its financial industry.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
We are delighted to announce the promotion of Kenneth Leung to the Partnership, a move that significantly strengthens our firm’s senior capabilities in financial regulation and dispute resolution.
Mr. Leung is a Hong Kong-qualified solicitor with over a decade of experience at the forefront of the region’s most complex legal challenges. His practice is defined by a sophisticated mastery of corporate and securities laws, where he seamlessly bridges the gap between contentious regulatory enforcement and high-stakes commercial litigation.
Renowned for his strategic precision, Mr. Leung regularly advises on matters involving fiduciary duties and civil fraud, providing robust advocacy in proceedings before the SFC, HKEX, and the High Court. He serves as a pivotal advisor to listed companies and licensed corporations, navigating the intricate regulatory landscapes and shareholder disputes that define the Hong Kong market.
The promotion of Mr. Leung will strengthen our firm’s capacity to deliver exceptional legal services to our clients amidst Hong Kong’s evolving regulatory landscape. His elevation underscores our commitment to excellence and ensures we remain at the forefront of the legal sector.
On 10 and 11 March 2026, the Securities and Futures Commission (“SFC”) and Independent Commission Against Corruption (“ICAC”) executed a major joint operation codenamed “Fuse”. The operation targeted suspected insider dealing and corruption involving senior executives of three licensed corporations, specifically two securities firms and a hedge fund management firm.
 …
During the operation, authorities searched 14 locations and arrested eight individuals. Those arrested included senior executives from the implicated firms and a middleman. Investigators suspect that senior executives at the securities firms accepted bribes exceeding HK$4 million from the hedge fund’s owner. In return, they allegedly leaked confidential information about upcoming share placements by various Hong Kong-listed companies before the information was publicly announced.
Leveraging this confidential information, the hedge fund established short positions through short selling and short equity swap contracts. When the share placements were eventually publicised, the relevant stock prices dropped, allowing the hedge fund to allegedly make illicit profits of approximately HK$315 million.
The joint raid is the latest instalment of joint operations between the SFC and the ICAC, driven by the escalating complexity of financial crime and the necessity for a unified regulatory response. Historically, the SFC handled the administrative regulatory sphere, while the ICAC governed the criminal investigative sphere. However, this distinction has become increasingly permeable, formalized by a 2019 Memorandum of Understanding (“MoU”) and hardened through successive joint operations. Legal practitioners advising listed issuers, licensed intermediaries, and directors of listed companies must all understand the mechanics of this unified enforcement regime.
The Statutory Architecture
The efficacy of the joint operation model is predicated not on the merging of powers, but on their parallel and coordinated application. The 2019 MoU establishes a framework where the limitations of one agency are offset by the capabilities of the other. The current enforcement doctrine utilizes a “pincer movement” strategy to dismantle complex networks systematically.
The Evolution of Enforcement
The operationalization of the MoU has evolved from focusing on singular instances of corruption to targeting sprawling, multi-jurisdictional syndicates.
Judicial Hardening and Strategic Preparation
The courts have responded to the surge in sophisticated financial crime with increasingly severe sentences. In May 2024, the Court of First Instance handed down the heaviest prison sentences for market manipulation since the enactment of the SFO, sentencing three defendants to terms ranging from 4 years and 4 months to 6 years and 8 months for their roles in manipulating shares of Ching Lee Holdings Limited.
In light of these developments, adopting a proactive defence strategy is imperative. Listed companies and financial institutions must prioritize the following:
Conclusion
With enforcement actions becoming more frequent, complex, and punitive, financial advisory work must go beyond technical compliance and address the broader risks of financial crime and internal corruption. It is foreseeable that the frequency of joint operations conducted by regulators such as the SFC and the ICAC will only increase in the future. Surely, this is a potent development for maintaining an orderly and clean financial market. While these collaborations boost market integrity and investor confidence, they also create a high-stakes environment where financial participants must be acutely aware of their legal obligations and rights.
To discuss how we can assist you, please contact our Partner Rainbow Ip, Consultant Kenneth Leung or Associate Ronnie Tse.
This article is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.