Transaction
Find out all about our firm’s latest transaction below. To learn more about any individual item, please contact us here.
Transaction
Find out all about our firm’s latest transaction below. To learn more about any individual item, please contact us here.
 …
Stevenson, Wong & Co. is pleased to announce that the firm has once again been recognised in the Benchmark Litigation Asia-Pacific 2026 rankings, reflecting our continued strength in litigation and dispute resolution.
In this year’s edition, the firm has been ranked in the following five practice areas:
This recognition highlights the breadth of our disputes practice and the firm’s experience in advising on a wide range of contentious matters, including commercial disputes, insolvency-related proceedings, regulatory and white-collar crime matters, and private client disputes.
As a Hong Kong law firm with substantial local experience and cross-border capabilities, Stevenson, Wong & Co. remains committed to delivering practical, strategic and client-focused legal solutions to corporations, individuals, families and private clients.
About Benchmark Litigation
Benchmark Litigation is an international legal ranking guide dedicated to litigation and dispute resolution. Its Asia-Pacific rankings are based on independent research, including market interviews, client feedback, peer review and analysis of recent casework.
We would like to thank our clients and peers for their continued trust and support.
Please contact our Partners Willy Cheng, Heidi Chui, Dominic Lau, Katy Lai, Rainbow Ip, Michael Lau or Kenneth Leung for any enquiries or further information.
To view the full list of rankings, please click here.
 …
Stevenson, Wong & Co. is pleased to announce that the firm has once again been recognised in Benchmark Litigation Asia-Pacific 2025, one of the leading guides to litigation and dispute resolution firms and practitioners across the region.
In the 2025 edition, our firm has been ranked in the following Hong Kong SAR practice areas:
This continued recognition reflects the strength and depth of our dispute resolution practice, as well as our team’s experience in handling a broad range of contentious matters for individuals, families, private clients and corporate clients.
About Benchmark Litigation
Benchmark Litigation is a specialist legal ranking publication focused on litigation and dispute resolution. Its Asia-Pacific rankings are based on independent research, including market analysis, interviews with litigators, arbitrators and dispute resolution specialists, client feedback, peer review, and assessment of recent casework.
We are grateful to our clients and peers for their continued support and recognition.
Please contact our Partners Willy Cheng, Heidi Chui or Dominic Lau for any enquiries or further information.
To view the full list of rankings, please click here.
 …
If you have been following the financial news, you might have noticed that the legal walls are closing in on Andrew Left, the founder of Citron Research.
On 1 June 2026, a federal jury in Los Angeles convicted the 55-year-old activist short-seller on 13 of 17 counts of securities fraud. Left faces a theoretical maximum of decades in prison at his upcoming sentencing in August.
Left’s downfall offers a perfect moment to reflect on a grand financial irony. It is a tale of two jurisdictions, a spectacular property collapse, and a downfall that threatens to deepen a pre-existing public hostility and misunderstanding towards the practice of short-selling itself.
To understand the tragedy and comedy of Andrew Left, we have to travel back to 2012, when Left targeted a titan of the Chinese real estate market: China Evergrande Group.
In a research report, Citron Research asserted that Evergrande was fundamentally insolvent and accused it of using fraudulent accounting tricks to mask its massive debts. The result of this early whistleblowing?
The Vindication: A Decade Too Late
Fast forward to the 2020s. Evergrande collapsed under a staggering $300 billion mountain of debt, triggering a systemic crisis in Chinese real estate. In 2024, a Hong Kong court ordered the company’s liquidation.
Adding the ultimate layer of irony, Evergrande’s liquidators are now threatening massive legal claims against PricewaterhouseCoopers (PwC), the company’s former auditor, for failing to sound the alarm on the property giant’s catastrophic books.
So, does Andrew Left deserve vindication?
In the court of public opinion, perhaps. The Hong Kong regulators essentially shot the messenger and sent the opposite signal to the market.
If Left was a prophetic hero in Hong Kong, why is he currently awaiting sentencing in Los Angeles?
The key difference lies in his trading behaviour. In Hong Kong, the issue was whether his analysis of Evergrande was fundamentally honest. In the US, the Department of Justice and the SEC proved that Left was running a sophisticated “bait-and-switch” scheme.
According to prosecutors, Left’s business model wasn’t just about publishing research. It was about using his broad digital reach and television appearances to move stock prices in the short term, and then immediately doing a “U-turn” trade:
Public Posture = Ultra-Bearish (or Bullish)
==> Actual Action = Secretly exit position within minutes
Crucially, several of the trades that sealed Left’s fate did not even involve short-selling. Instead, they were classic, long-side “pump-and-dump” manoeuvres. Left would quietly accumulate long positions, hype them to his followers to drive the price up, and then immediately dump his holdings at a premium.
Left wasn’t convicted because he was a short-seller. He was convicted because he was telling his followers to head for the exits while he was secretly sneaking back inside to buy up the discounted goods, or pumping shares he was already quietly selling.
The Great Misconception: Are Short-Sellers Actually “Evil”?
The public generally despises short-sellers. We are conditioned to favour builders and optimists. When a stock price goes up, everyone wins (or so we assume). When a short-seller arrives, they are viewed as market cynics profiteering from corporate distress.
A few years ago, I was invited to deliver a seminar entitled “How to Tackle Short-Sellers”. The audience, largely comprised of corporate executives, expected a tactical playbook of defensive manoeuvres.
When I commented that the most effective defence was simply to be honest with their financial data and ready to rebuke a short-selling report — pointing out that the SFC can ultimately only prosecute for the dissemination of false or misleading information — the reception was remarkably poor. It was a telling moment. To many in the corporate establishment, the short-seller is the harbinger of doom, an existential threat to be silenced, rather than a mirror reflecting their own structural flaws.
But this emotional bias ignores a fundamental law of economic hygiene: every healthy market needs its sceptics, and price discovery requires friction.
Why Short-Selling is Crucial for Markets
Conclusion: Don’t Throw the Bear Out with the Bathwater
The real tragedy of Left’s fall is that it will almost certainly deepen public and regulatory hostility towards short-selling. By conflating one man’s manipulative, long-side deceit with a vital market mechanism, we risk feeding the popular narrative that short-selling itself is a corrupt enterprise.
As Left prepares for his sentencing on 31 August 2026, regulators and the public must learn the right lesson from his trial. The target of our anger should be market manipulation and deceit, not the practice of short-selling itself.
After all, a market without short-sellers is like a house without a smoke detector: quieter, perhaps, but infinitely more vulnerable to a sudden, catastrophic fire while you sleep.
Dominic Lau
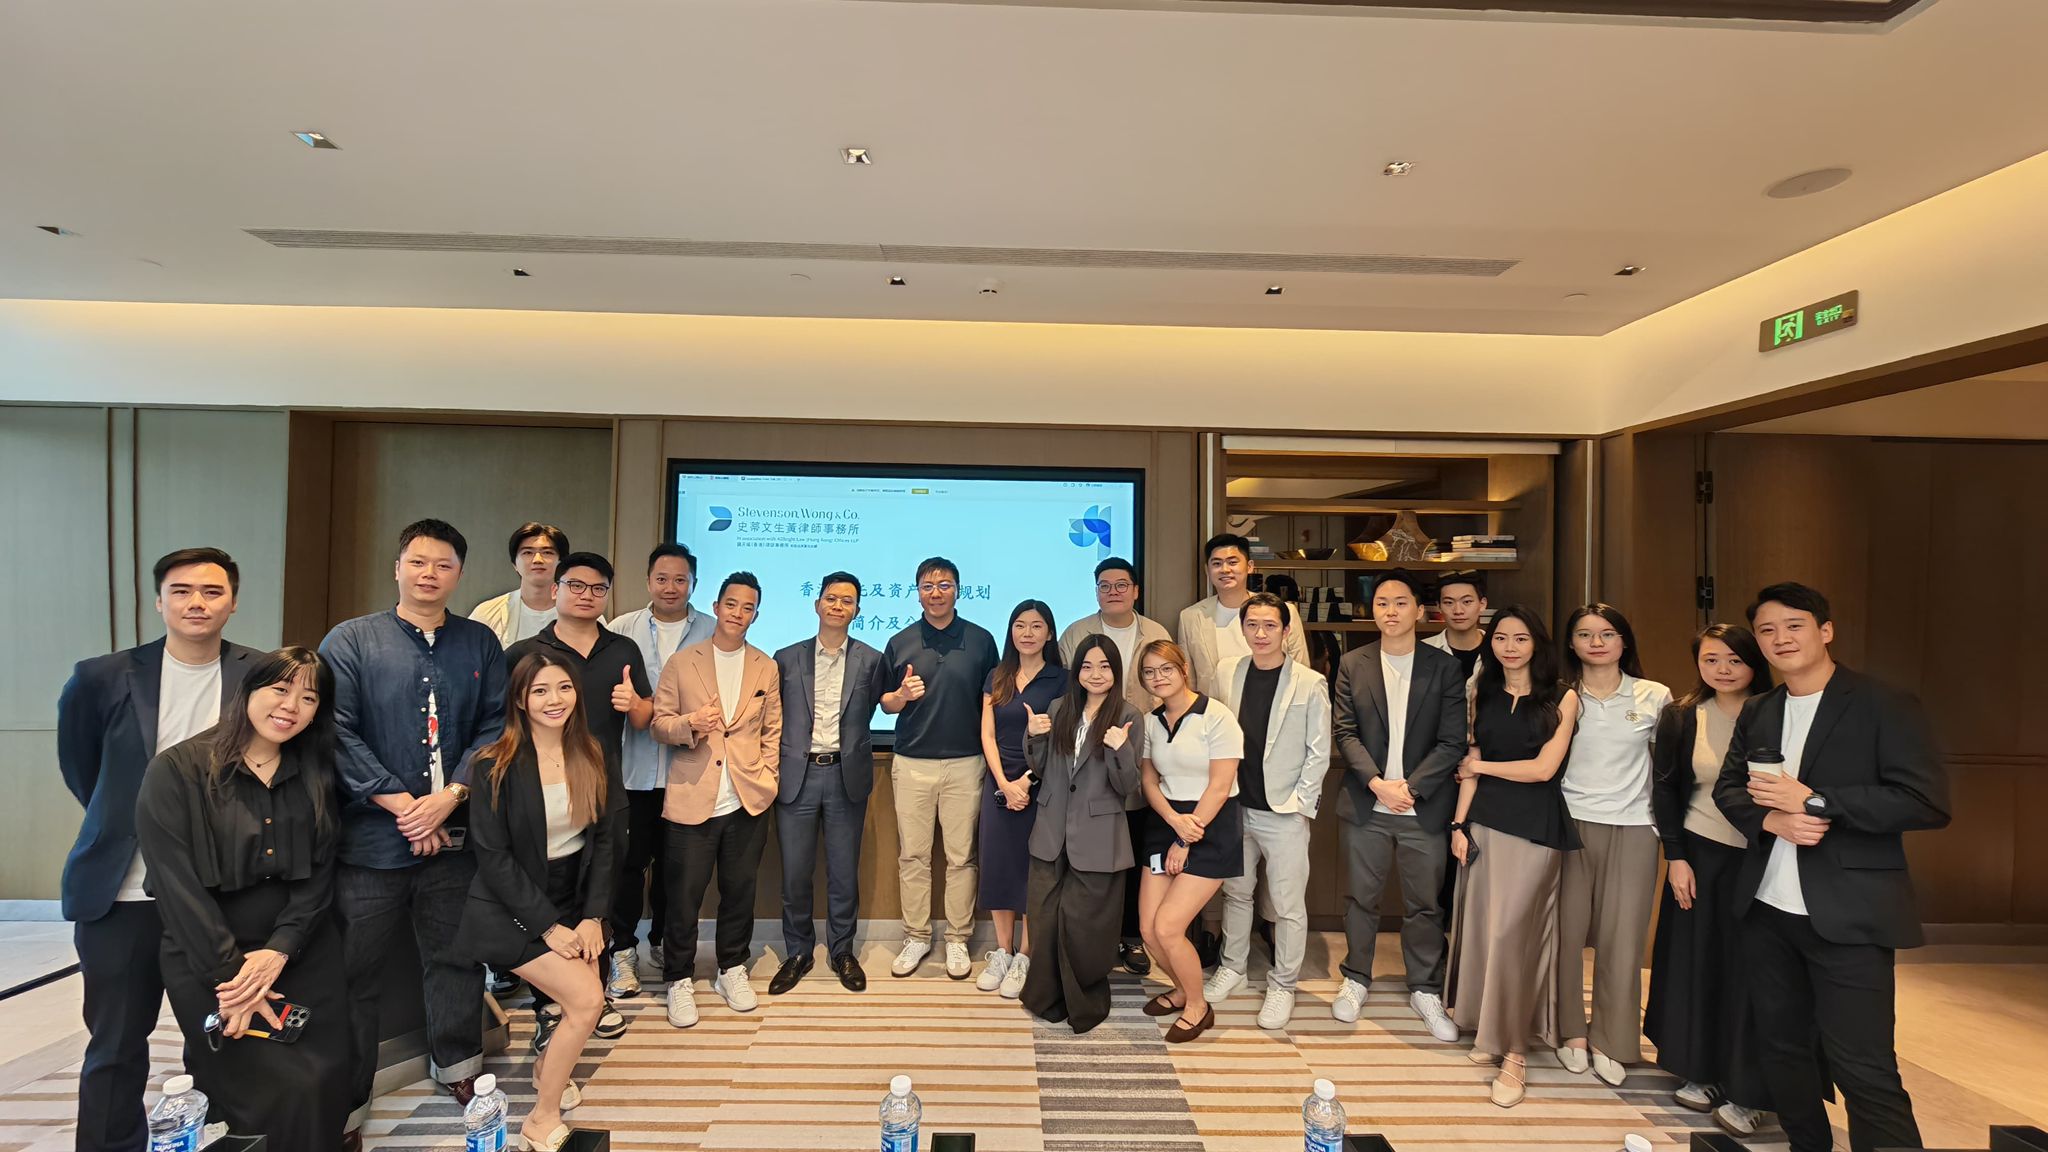 …
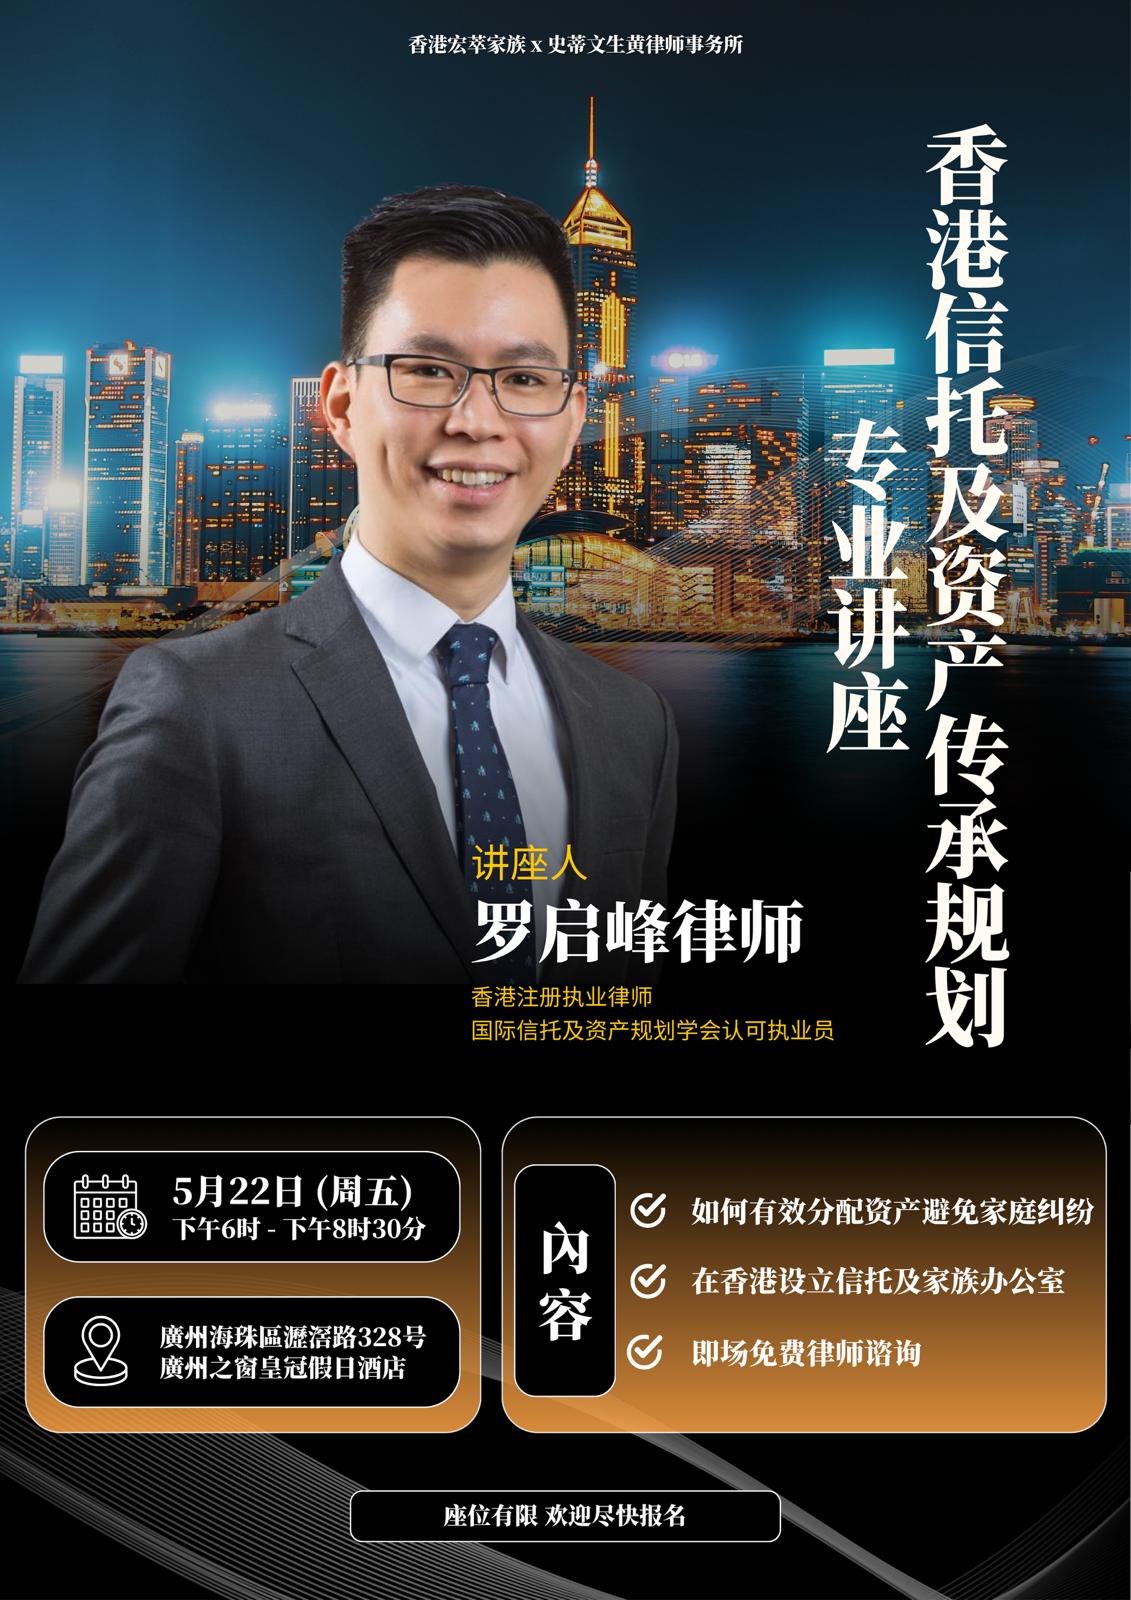
On 22 May 2026, our Partner, Calvin Lo, was invited by AIA’s Vendici Family to act as the keynote speaker for a seminar titled “Hong Kong Trusts and Wealth Succession Planning”, held in Guangzhou. Mr Lo is a Trust and Estate Practitioner (TEP) of the Society of Trust and Estate Practitioners (STEP) and a Certified Trust Practitioner (CTP) of the Hong Kong Trustees’ Association.
Addressing the core requirements of high-net-worth individuals, the seminar provided attendees with a comprehensive analysis of modern wealth succession instruments and cutting-edge regulatory policies.
During the session, Mr Lo introduced key succession planning tools—including wills, enduring powers of attorney, and trusts—highlighting the distinct advantages of trusts in asset protection and family wealth preservation. He broke down the pivotal roles within trust structures and offered practical insights into trust deeds, letters of wishes, structural design, and the selection of jurisdictions. The presentation also covered ongoing administration and the definition of family offices, concluding with a detailed look at the zero-tax concession for Family Investment Holding Vehicles (FIHVs) under Schedule 16E of the Hong Kong Inland Revenue Ordinance.
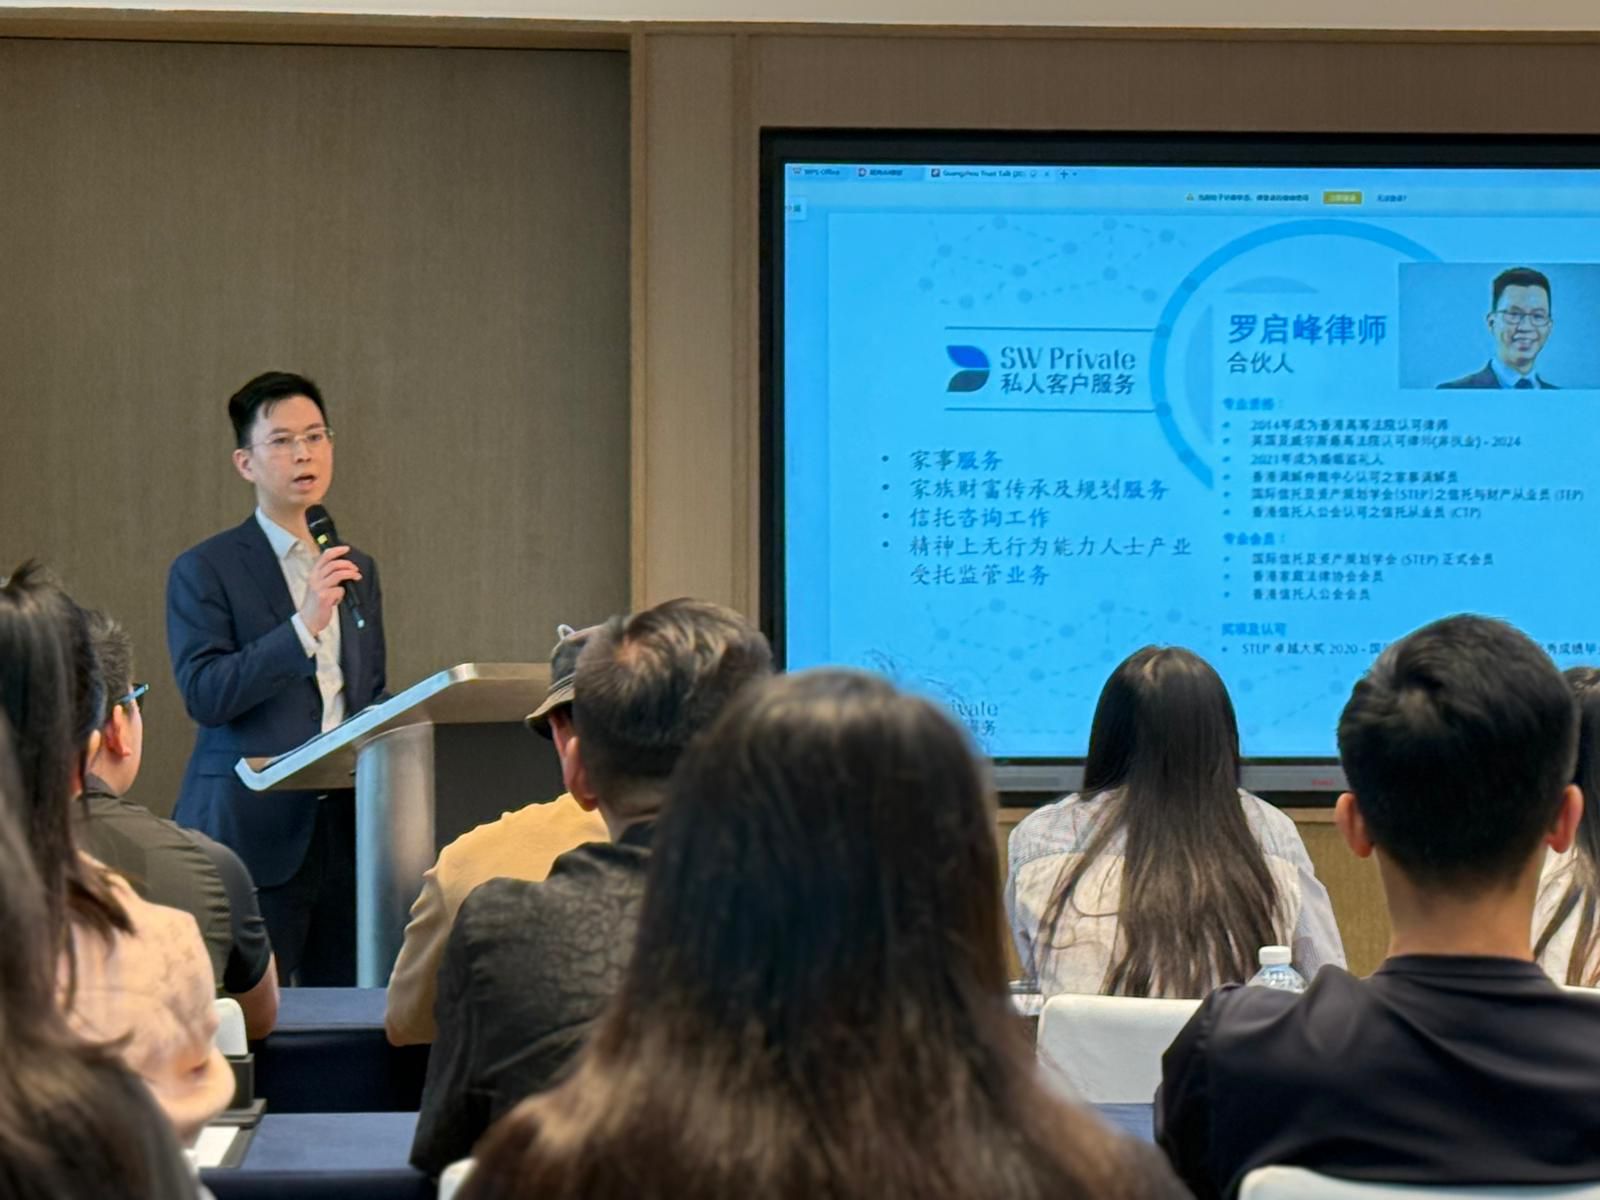
Using the famous Zhang Lan case as a lesson, Mr Lo explained how improper administration of trust and excessive reserved powers and control would adversely impact the asset protection functions of a trust. Mr Lo also used practical case studies to highlight the risks of neglecting succession planning, such as severe probate complications, financial strain on surviving family members, and legal disputes triggered by forced heirship regimes in Mainland China and Europe.
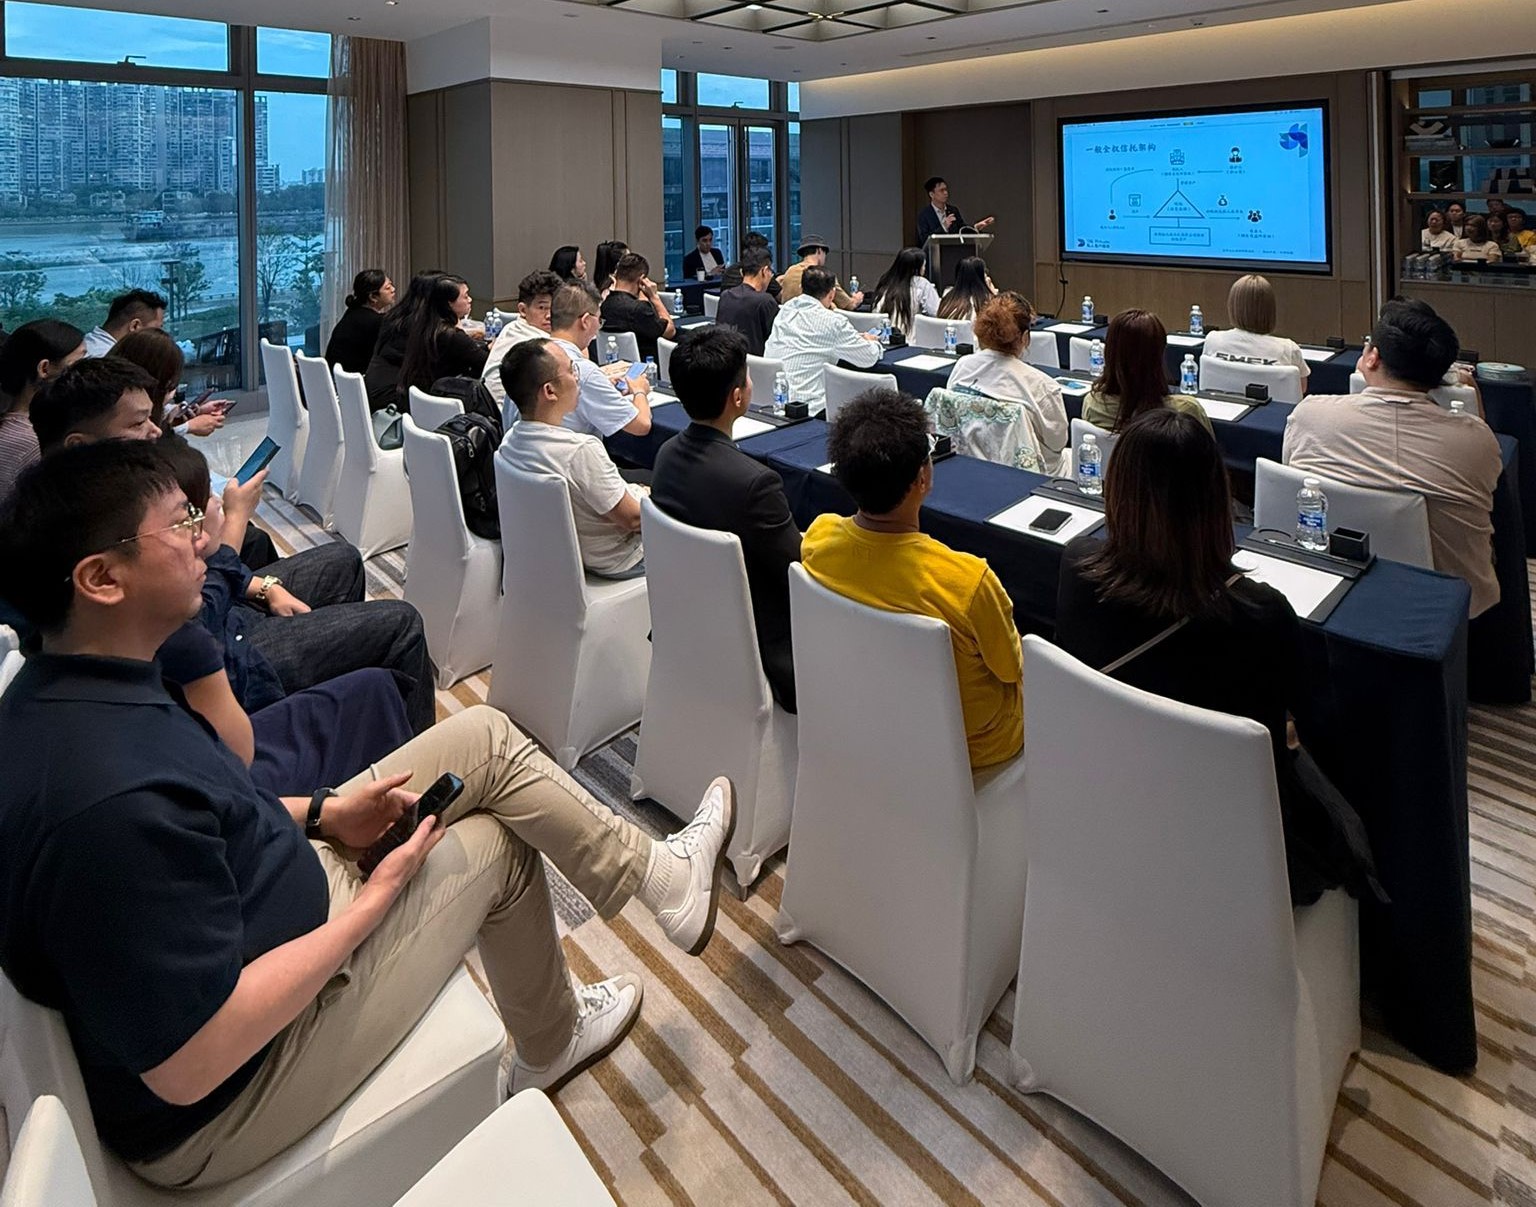
The event was attended by high-net-worth individuals, family business owners, and wealth management professionals and was well-received by the full-house audience.
 …
On 19 May 2026, the Stock Exchange of Hong Kong Limited (the “Stock Exchange”) published a Statement of Disciplinary Action against a former company secretary of a listed company, Venus Medtech (Hangzhou) Inc. (Stock Code: 2500) (the “Listco”).
The Listco engaged a corporate service provider (“CSP”) to provide company secretarial services, including advice on Listco’s compliance with the Rules Governing the Listing of Securities on The Stock Exchange (the “Listing Rules”), review of corporate documents such as interim reports and annual reports, and assignment of a qualified company secretary to the Listco pursuant to Rule 3.28 of the Listing Rules. The CSP assigned Mr. Wong Wai Chiu (“Mr. Wong”), a certified public accountant, to the Listco. Mr. Wong was appointed as one of the joint company secretaries of the Listco on 18 January 2021.
During the period from January 2020 to June 2023, the Listco provided unauthorised financial assistance totaling approximately RMB 2.477 billion to two of its executive directors (the “Non-compliant Transactions”). The Listco was found to be in non-compliance with the Listing Rules regarding certain Non-compliant Transactions. For the financial years ending 31 December 2021 and 2022, Mr. Wong received draft annual results and reports from the Listco for which contained references to Non-compliant Transactions. However, Mr. Wong failed to review the relevant documents. Instead, Mr. Wong delegated his company secretarial responsibilities to his colleagues at the CSP, who only provided high-level and clerical comments. As a result, the board of directors of the Listco (the “Board”) was not made aware of Listing Rules implications relating to the Non-compliant Transactions.
The Listing Committee of the Stock Exchange (the “Listing Committee”) found that Mr. Wong failed to discharge his duties as a company secretary, and was liable under Rule 2A.10B(3) of the Listing Rules for the Listco’s breaches of relevant reporting, announcement, circular and independent shareholders’ approval requirements pursuant to Chapters 13, 14 and 14A of the Listing Rules in relation to the Non-compliant Transactions. The Listing Committee considered that, had Mr. Wong reviewed the documents he received, considered the potential breaches of the Listing Rules and provided professional advice to the Board as required, the wrongdoings could have been prevented or rectified at an earlier stage. The Listing Committee also considered that Mr. Wong’s appointment as a “named” company secretary of the Listco is personal, and the involvement of external legal counsels and auditors did not relieve Mr. Wong of his professional obligations as a company secretary.
This case is notable as it is the first disciplinary action taken by the Stock Exchange against an individual in his sole capacity as a company secretary (without any other concurrent role, such as director or CFO) in a listed company.
2.1 Key legal principles
The core finding of this case is not that the company secretary “knew and failed to report”, but negligence in the form of “should have known but did not report”, which constitutes a dereliction of duty.
The Listing Committee explicitly rejected two common defences:
This case reveals three legal risks of “named” company secretaries:
If you currently serve or intend to be appointed as a “named” company secretary of a listed company (particularly as an external service provider), you are recommended to implement the following risk control measures:
An alarming red line been drawn: “Named” company secretaries of listed companies are personally accountable. Individuals acting as “named” company secretaries of listed companies, whether in-house or outsourced, must discharge their duties as a member of the senior management of listed companies. This requires personal oversight, professional judgement and timely remedial actions to ensure compliance and good corporate governance.
The proportionality between the amount of compensation received by the “named” company secretaries and the legal risks involved for them to discharge their duties is irrelevant. The test is clear: As a “named” company secretary, have you personally reviewed the potential non-compliant documents and raised the necessary queries?
For more information, please see:
(Chinese version)
https://www.hkex.com.hk/-/media/HKEX-Market/Listing/Rules-and-Guidance/Disciplinary-and-Enforcement/Disciplinary-Sanctions/2026/2605192_SoDA_tc.pdf
(English version)
https://www.hkex.com.hk/-/media/HKEX-Market/Listing/Rules-and-Guidance/Disciplinary-and-Enforcement/Disciplinary-Sanctions/2026/2605192_SoDA.pdf
If you wish to assess Listing Rules compliance risks, company secretary responsibilities or risk management arrangements in relation to a specific case, please contact our Partner Terence Lau, Senior Associate Teresa Yip or Associate Michael Leung.
This article is provided for general informational purposes only. Its content does not constitute legal advice and should not be treated as such. You should not rely solely on the content of this article when making any decision or taking (or refrain from taking) any action without first obtaining specific professional legal advice based on your particular facts and circumstances. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
On May 14, 2026, the U.S. Securities and Exchange Commission (SEC) officially approved the proposed rule change SR-NASDAQ-2025-069 (as modified by Amendment No. 3), introducing additional initial listing standards for companies primarily operating in China (including the Hong Kong and Macau Special Administrative Regions). The rules will take effect 30 days after approval.
This move is not merely elevating standards but represents Nasdaq’s positive signal in balancing investor protection and market vitality. For high-quality Chinese companies with strong fundamentals and compliance awareness, the new rules provide a clearer pathway to stand out in the global capital markets, attract premium investors, and achieve long-term value enhancement.
The New Listing Standards
In recent years, Chinese companies have shown strong enthusiasm for U.S. listings, reaching new highs in 2024 and 2025. China holds significant weight in emerging market indices and is a key allocation for global investors. However, some smaller or less liquid listings have raised regulatory concerns, including but not limited to potential manipulation risks, audit transparency, and cross-border enforcement challenges.
Nasdaq’s new rules focus on “China-based Issuers” and use quantitative standards to improve listing quality, aiming to ensure sufficient liquidity, investor base, and fair and orderly trading, while addressing concerns from Congress, state financial officers, SEC and the market.
Minimum Offering Size for an IPO
When conducting an IPO, China-based issuers must use a Firm Commitment Offering to issue securities to public holders in the United States, with gross proceeds to the company of no less than US$25 million. This is higher than the minimum Market Value of Unrestricted Publicly Held Shares (MVUPHS) of US$15 million required for Nasdaq Capital Market.
Minimum Market Value of Publicly Held Shares for a Business Combinations (e.g., Special Purpose Acquisition Companies (SPAC) Mergers)
To prevent circumvention of IPO rules, China-based issuers listing via business combination must have a MVUPHS of no less than US$25 million. This requirement ensures that the post-merger entities possess a sufficient public float, thereby mitigating the risk of speculative trading.
Direct Listing Restrictions (as defined in Rule IM-5315-1)
China-based issuers may only apply for direct listing on the higher-liquidity Nasdaq Global Select Market (NGS) and are not permitted to list on the Nasdaq Global Market (NGM) or Nasdaq Capital Market (NCM) via direct listing. They must also satisfy stricter requirements (e.g., a minimum Market Value of Publicly Held Shares of US$250 million).
The above restrictions help ensure that a company has sufficient public float, investor base, and trading interest to generate the market depth and liquidity necessary to promote fair and orderly trading in the secondary market.
Transfer Listing Requirements
China-based issuers transferring from over-the-counter (OTC) market or other national exchanges must have traded for at least one year on the prior market and have a MVUPHS at no less than US$25 million. This requirement ensures that securities to be listed on Nasdaq have adequate liquidity, distribution, and U.S. investor interest.
Determination Criteria for “China-based Issuers”
Nasdaq will holistically assess the following factors to determine whether a company is a China-based issuer, including:
Nasdaq makes determinations on a holistic basis and may request sufficient information to support the above assessment. If China-based issuers do not satisfy the additional requirements described above, Nasdaq may deny their applications. Appeals are available under Nasdaq Rule 5800 Series.
Deeper Regulatory Logic and Data Support
Nasdaq’s analysis shows that many Chinese IPOs below US$25 million from 2022-2025 faced higher rates of compliance issues, with nearly half cited for continued listing failures. In addition, referrals for suspected market manipulation involving Chinese emerging market companies were disproportionately high relative to the overall proportion of Chinese companies listed on Nasdaq.
The rules aimed at mitigating the illiquidity, high volatility, and potential manipulation risks often associated with small-scale listings. Additionally, the new rules emphasize the due diligence advantages of a Firm Commitment Offering, which helps enhance disclosure quality and bolster investor confidence.
How High-Quality Companies Should Respond
Conclusion: Strategic Opportunities Under the New Rules
Nasdaq’s rule changes mark a more mature and standardized phase in U.S.-China capital market interactions. They serve as a screening mechanism that weeds out low-quality and volatile cases while creating a healthier, more liquid environment for truly competitive companies.
For well-governed, high-growth Chinese enterprises, these rules provide a competitive advantage: higher standards attract more institutional investors, enhance international brand recognition, and fuel further development for continuous financing and development. In the context of global allocation to China stories, leading compliant companies will seize broader opportunities and maximize value.
Companies intending to list are advised to assess early, prepare proactively, and embrace this standardized opportunity to leverage this regulatory normalization as a strategic opportunity.
If you have any enquiries regarding Nasdaq listings, or wish to learn more, please contact our Partner Gordon Tsang, Senior Associate Gary Kwok, Associate Maggie Yim or Associate Sam Liu.
This article is provided for general informational purposes only. It does not constitute, and should not be construed as, legal advice or investment guidance, nor does it create a solicitor-client relationship. The information contained herein may be updated or amended from time to time, and the applicability of any content will depend on specific facts and relevant laws or regulations. The feasibility of any company’s listing should be assessed on a case-by-case basis in light of its particular circumstances and the applicable regulatory framework. To the fullest extent permitted by law, our firm and our lawyers accept no responsibility for any loss or damage (whether direct or indirect) arising from any decision, action, or inaction taken in reliance upon the content of this publication.