Transaction
Find out all about our firm’s latest transaction below. To learn more about any individual item, please contact us here.
Transaction
Find out all about our firm’s latest transaction below. To learn more about any individual item, please contact us here.
 …
28 July 2026
On 24 July 2026, The Stock Exchange of Hong Kong Limited (the “Exchange”) (wholly-owned subsidiary of HKEX) published a guidance letter (HKEX-GL122-26) to provide clarity on the potential implications under the Listing Rules for new listing applicants and listed issuers engaging in digital asset-related activities, covering continuing obligations and disclosure requirements.
Against the backdrop of rapid technological innovation in global financial markets, the Exchange has observed a growing number of listed issuers involved in digital asset-related activities or exploring such initiatives, ranging from investments in digital assets and stablecoin issuance to tokenisation and the creation of blockchain-based platforms.
While acknowledging the transformative potential of digital assets to bring tangible benefits to the real economy and financial markets, the Exchange remains committed to safeguarding investor confidence and protecting the interests of the investing public.
The definition of “digital assets” is not exclusive, but the Exchange gave some examples that “digital assets” are defined as assets that:
Examples include tokenised real-world assets (including traditional financial instruments), stablecoins, and cryptoassets such as Bitcoin. While the Exchange caveated that this definition is used solely to explain Listing Rules implications, we note that such definition is generally consistent with those as seen in other Hong Kong regulatory regimes.
Companies that primarily adopt an operating model similar to a “digital asset treasury company” (DAT), i.e., their principal business involves buying and holding digital assets, will unlikely be considered suitable for listing under Chapter 8 of the Listing Rules. By contrast, SFC-authorised exchange-traded funds investing in digital assets may be listed under Chapter 20.
Issuers have a continuing obligation to maintain a business that is substantive, viable and sustainable. If an issuer adopts a DAT‑like model, holding digital assets unrelated to its operations, or holding digital assets without any substantive business, it will likely be regarded as lacking sufficient operations under Rule 13.24(1) of the Listing Rules.
Issuers whose assets consist wholly or substantially of cash and/or short-term investments are regarded as “cash companies” and are not suitable for listing (see Rule 14.82 of the Listing Rules). Digital assets held for investment purposes will likely fall within the scope of “cash and/or short-term investments”. If an issuer is found to be a cash company, trading in its securities will be suspended.
Where an issuer acquires a business holding substantial digital assets and its existing principal business becomes immaterial after the transaction, the Exchange may treat the transaction as a reverse takeover, requiring the issuer to comply with all new listing requirements. Similarly, large‑scale issues of new securities for cash to acquire or develop a new business may be viewed as an attempt to circumvent the new listing requirements, and the Exchange may not grant listing approval for the shares to be issued.
Acquisitions or disposals of digital assets are generally considered transactions under Chapters 14 (Notifiable Transactions) and 14A (Connected Transactions) of the Listing Rules, regardless of whether they are conducted for investment, treasury or distribution purposes.
Issuers must comply with applicable disclosure and shareholder approval requirements based on transaction size and observe the aggregation rules for transactions involving the same type of digital assets conducted within a 12‑month period.
The Exchange reiterated that advance “blanket approvals” without key transaction terms are generally not acceptable, as shareholders would not have sufficient information to make an informed voting decision. Proposals with key terms will be examined cautiously, and those exhibiting abuses or non‑compliance will not be accepted.
A notable clarification from the Exchange is that acquisitions or disposals of digital assets classified as cash or cash equivalents, namely central bank digital currencies (CBDC) or “other regulated digital monetary value that is authorised or prudentially supervised, designed primarily for payment/settlement and redeemable at par in fiat currency”, will not normally be treated as notifiable transactions. Remarkably, the Exchange has confirmed in this Guidance Letter that an example of such digital representation of monetary value in Hong Kong is any stablecoin whose issuance is authorised by a licence granted under the Stablecoins Ordinance (Cap. 656 of the Laws of Hong Kong).
The Exchange stresses that any disclosure relating to digital asset‑related activities must be accurate, complete in all material respects, and not misleading or deceptive. Disclosure is not required solely because an issuer engages in such activities. However, where disclosure is otherwise required under the Listing Rules, other laws or regulations, or made voluntarily, issuers should include the following information (to the extent relevant):
The Exchange also requires additional specific disclosures on:
Issuers should avoid making misleading disclosure or creating unrealistic expectations, particularly at preliminary stages, and should refrain from using generic or boilerplate descriptions when explaining rationale and integration of digital assets.
If an issuer proposes to distribute digital assets (including tokenised assets) to shareholders in specie, it must ensure fair and equal treatment of all shareholders. The Exchange will have concerns if the objectives and reasons are unclear, no reasonable cash alternative is offered, certain shareholders are ineligible to receive the distribution, or shareholders cannot readily hold title or realise value from the distributed tokens.
When issuing equity securities to fund digital asset acquisitions, the announcement must include the recommended disclosure set out above. Issuers must report on use of proceeds in subsequent annual reports, including details of digital assets acquired and their purposes. If a particular digital asset holding represents 5% or more of the issuer’s total assets at year‑end, the annual report disclosure requirements for significant investments apply.
Issuers are reminded to establish and maintain adequate risk management and internal control (RMIC) systems. For digital asset‑related activities, appropriate RMIC measures commensurate with the nature, scale and complexity of the activities should be implemented, covering:
Conclusion
We appreciate the Exchange’s clarification on its stance in relation to digital assets. As the classification of digital assets continues to crystallise and gain broader acceptance, the Listing Rules should be applied consistently with reference to such classifications. While there is indeed a difference in how the Listing Rules treat digital assets in general compared to CBDCs and stablecoins specifically, this distinction is understandable given the latter’s “fiat currency” nature. That said, in view of digital assets’ agility and unique characteristics, appropriate risk management and internal control measures are indeed necessary. The Exchange’s clarity on digital assets is a positive development, and we are confident it will help foster greater innovation and confidence in Hong Kong’s digital asset ecosystem.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
Stevenson, Wong & Co. is pleased to announce that the firm has been shortlisted in six categories at the Asian Legal Business (ALB) Hong Kong Law Awards 2026, organised by Asian Legal Business, Thomson Reuters’ leading legal publication for the region.
The shortlist recognises the firm’s continued strength across a broad range of practice areas and reflects its commitment to providing high-quality legal services to clients in Hong Kong and across the Greater Bay Area. The nominations span both firm-wide and individual categories, highlighting the breadth of the firm’s capabilities and the recognition of its lawyers’ professional excellence.
The ALB Hong Kong Law Awards honour outstanding achievements by law firms, lawyers and in-house legal teams across Hong Kong. Winners are selected through an independent judging process based on a range of criteria, including legal expertise, significant matters handled, client service, market reputation and overall contribution to the legal profession.
The award winners will be announced at the ALB Hong Kong Law Awards ceremony on 11 September 2026 in Hong Kong.
Shortlisted Categories
Firm Awards
Individual Awards
Please click hereto view the complete list of nominations for the ALB Hong Kong Law Awards 2026.
 …
On 20 April 2026, the Hong Kong Government and the Supreme People’s Court signed a new Arrangement on Mutual Service of Judicial Documents in Civil and Commercial Proceedings (the “New Arrangement”), marking an important step towards modernising cross-border judicial cooperation.
The New Arrangement will come into effect upon completion of the relevant legislative procedures in Hong Kong.
Background
Since 1999, cross‑border service between Hong Kong and the Mainland has operated under a court‑to‑court entrustment mechanism, under which Hong Kong courts transmit judicial documents to their Mainland counterparts for onward service, and vice versa.
Over time, requests for mutual service of judicial documents have surged alongside the growth in cross-boundary interactions. Against this backdrop, the following challenges have become apparent:
Expanded and Multi-Route Model of Service
Under the New Arrangement, service is no longer limited to court-to-court entrustment. The following modes of service are also recognised:
These modes may be used in parallel. Service may be regarded as effective based on the earliest successful method, which significantly enhances efficiency.
It should be noted that judicial documents to be served in the Mainland must be in the Chinese language. Where the documents are not in Chinese, a Chinese translation must be provided.
Where these methods prove unsuccessful, service may be effected by public announcement. In such cases:
Proof of Service
Proof that a document has been received may take various forms, including:
Importantly, service may also be deemed effective where the recipient has referred to the served judicial documents before the adjudicating court or has acted in accordance with those contents.
Relevance to Divorce Proceedings in Hong Kong involving parties in the Mainland
The New Arrangement is expected to have practical significance in divorce proceedings involving the Mainland.
Whilst it is not necessary to seek prior leave from the Hong Kong courts to serve divorce petitions and other documents in matrimonial proceedings out of jurisdiction, Order 11 of the Rules of the High Court must be complied with. Proceedings may be delayed if the petition or other documents cannot be properly brought to the attention of the respondent or other interested third parties in the Mainland.
The New Arrangement is therefore expected to facilitate the cross-border service of divorce petitions between Hong Kong and the Mainland, enhancing both efficiency and procedural flexibility, particularly in cases involving non‑cooperation or uncertainty as to the whereabouts of the respondent or other interested third parties.
Please contact our Partners, Wendy Lam and Calvin Lo, for any enquiries or further information.
This article is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
On 26 May 2026, the Financial Services and the Treasury Bureau (“FSTB”) and the Securities and Futures Commission (“SFC”) published their consultation conclusions on the legislative proposal to regulate virtual asset (VA) advisory and management service providers in Hong Kong.
With the overarching goal of introducing a bill into the Legislative Council in 2026 under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance (Cap. 615) (“AMLO”), these new regimes complete a critical node in Hong Kong’s digital asset ecosystem. However, beneath the surface of broad market support lies a shifting regulatory landscape that demands immediate attention, particularly for traditional asset managers who may have previously considered themselves outside the SFC’s virtual asset crosshairs.
Adhering strictly to the “same activity, same risks, same regulation” principle, the SFC is establishing a framework that mirrors the traditional Type 4 (advising on securities) and Type 9 (asset management) regulated activities under the Securities and Futures Ordinance (“SFO”). For both existing VA-native firms and traditional asset managers, the margin for error has just been drastically reduced.
The “no de minimis” trap for traditional Type 9 asset managers
Perhaps the most commercially significant takeaway from the consultation conclusions is the explicit confirmation that the regulators will not set a de minimis threshold for the VA Management Regime.
Historically, traditional Type 9 asset managers could manage portfolios with limited VA exposure (below the established de minimis threshold) without triggering the full weight of VA-specific licensing conditions. That safe harbour is now gone. Intermediaries licensed by or registered with the SFC to carry on Type 9 regulated activities under the SFO, which currently manage portfolios with VA exposure below the de minimis threshold, will be required to obtain a licence or registration under the new VA Management Regime.
Crucially, they will be subject to the exact same regulatory standards as full-scale VA fund managers. For traditional funds that have dabbled in tokenised assets or hold small crypto allocations, this triggers an immediate need for comprehensive gap analyses to ensure their current AML/CFT frameworks, valuation policies, and risk management systems meet the exacting standards of the AMLO.
The “hard stop” threat: no deeming arrangements
The regulators are playing hardball regarding the transition. The FSTB and SFC have confirmed they do not plan to grant a “deeming arrangement” (grandfathering) to existing VA advisory or VA management service providers. The regimes will take full effect on the commencement date of the relevant statutory provisions.
The consequences of inaction are severe. The regulators have explicitly warned that providers who do not contact the SFC or the Hong Kong Monetary Authority (HKMA) for pre-application may suffer undue business disruptions, as they will have to stop operations on the commencement date. Firms must take appropriate steps as soon as possible to ensure proper transition, or wind down their VA management business in an orderly manner.
The silver lining: expedited fast track and early engagement
To mitigate market disruption, the SFC will introduce an expedited approval process for licensed corporations and registered institutions currently providing VA advisory and VA management services.
The regulators strongly encourage all industry stakeholders to reach out as soon as possible to initiate pre-application processes. Early engagement will allow firms to walk through the licensing process and help ensure their business models align with regulatory expectations.
Thematic inspections: the SFC’s escalating enforcement
This legislative overhaul does not exist in a vacuum; it coincides with an increasingly aggressive posture from the SFC regarding general asset management compliance. In October 2024, the SFC issued a circular flagging various deficiencies and substandard conduct identified during its supervision of licensed corporations managing private funds.
The SFC stated it will commence a thematic on-site inspection of asset managers managing private funds and will not hesitate to take decisive action against asset managers and their management, including Managers-In-Charge and Responsible Officers, for failures to discharge supervisory duties.
Because the new VA regimes operate on the “same activity, same risks, same regulation” principle, prospective VA managers must anticipate this exact level of scrutiny. Furthermore, VA management service providers who take a particular VA into custody on behalf of funds under their management (self-custody) will be subject to robust self-custody requirements.
So, what should asset managers do now?
The transition of VA advisory and management into the AMLO framework means that institutional-grade compliance and rigorous anti-money laundering controls are no longer optional. Instead, they are prerequisites for survival.
Stevenson, Wong & Co.’s Regulatory and Litigation practice is uniquely positioned to help your firm navigate this critical juncture. We routinely advise market-leading financial institutions, family offices, and virtual asset service providers on complex regulatory structuring and SFC enforcement matters.
Our team can assist you with:
The window to secure a seamless transition is narrowing. Proactive engagement is the only viable strategy to protect your operations and capitalize on Hong Kong’s expanding digital asset ecosystem.
If you have any questions or would like to understand how these regulatory changes may impact your business or compliance obligations, please reach out to our Partner Kenneth Leung.
This article is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
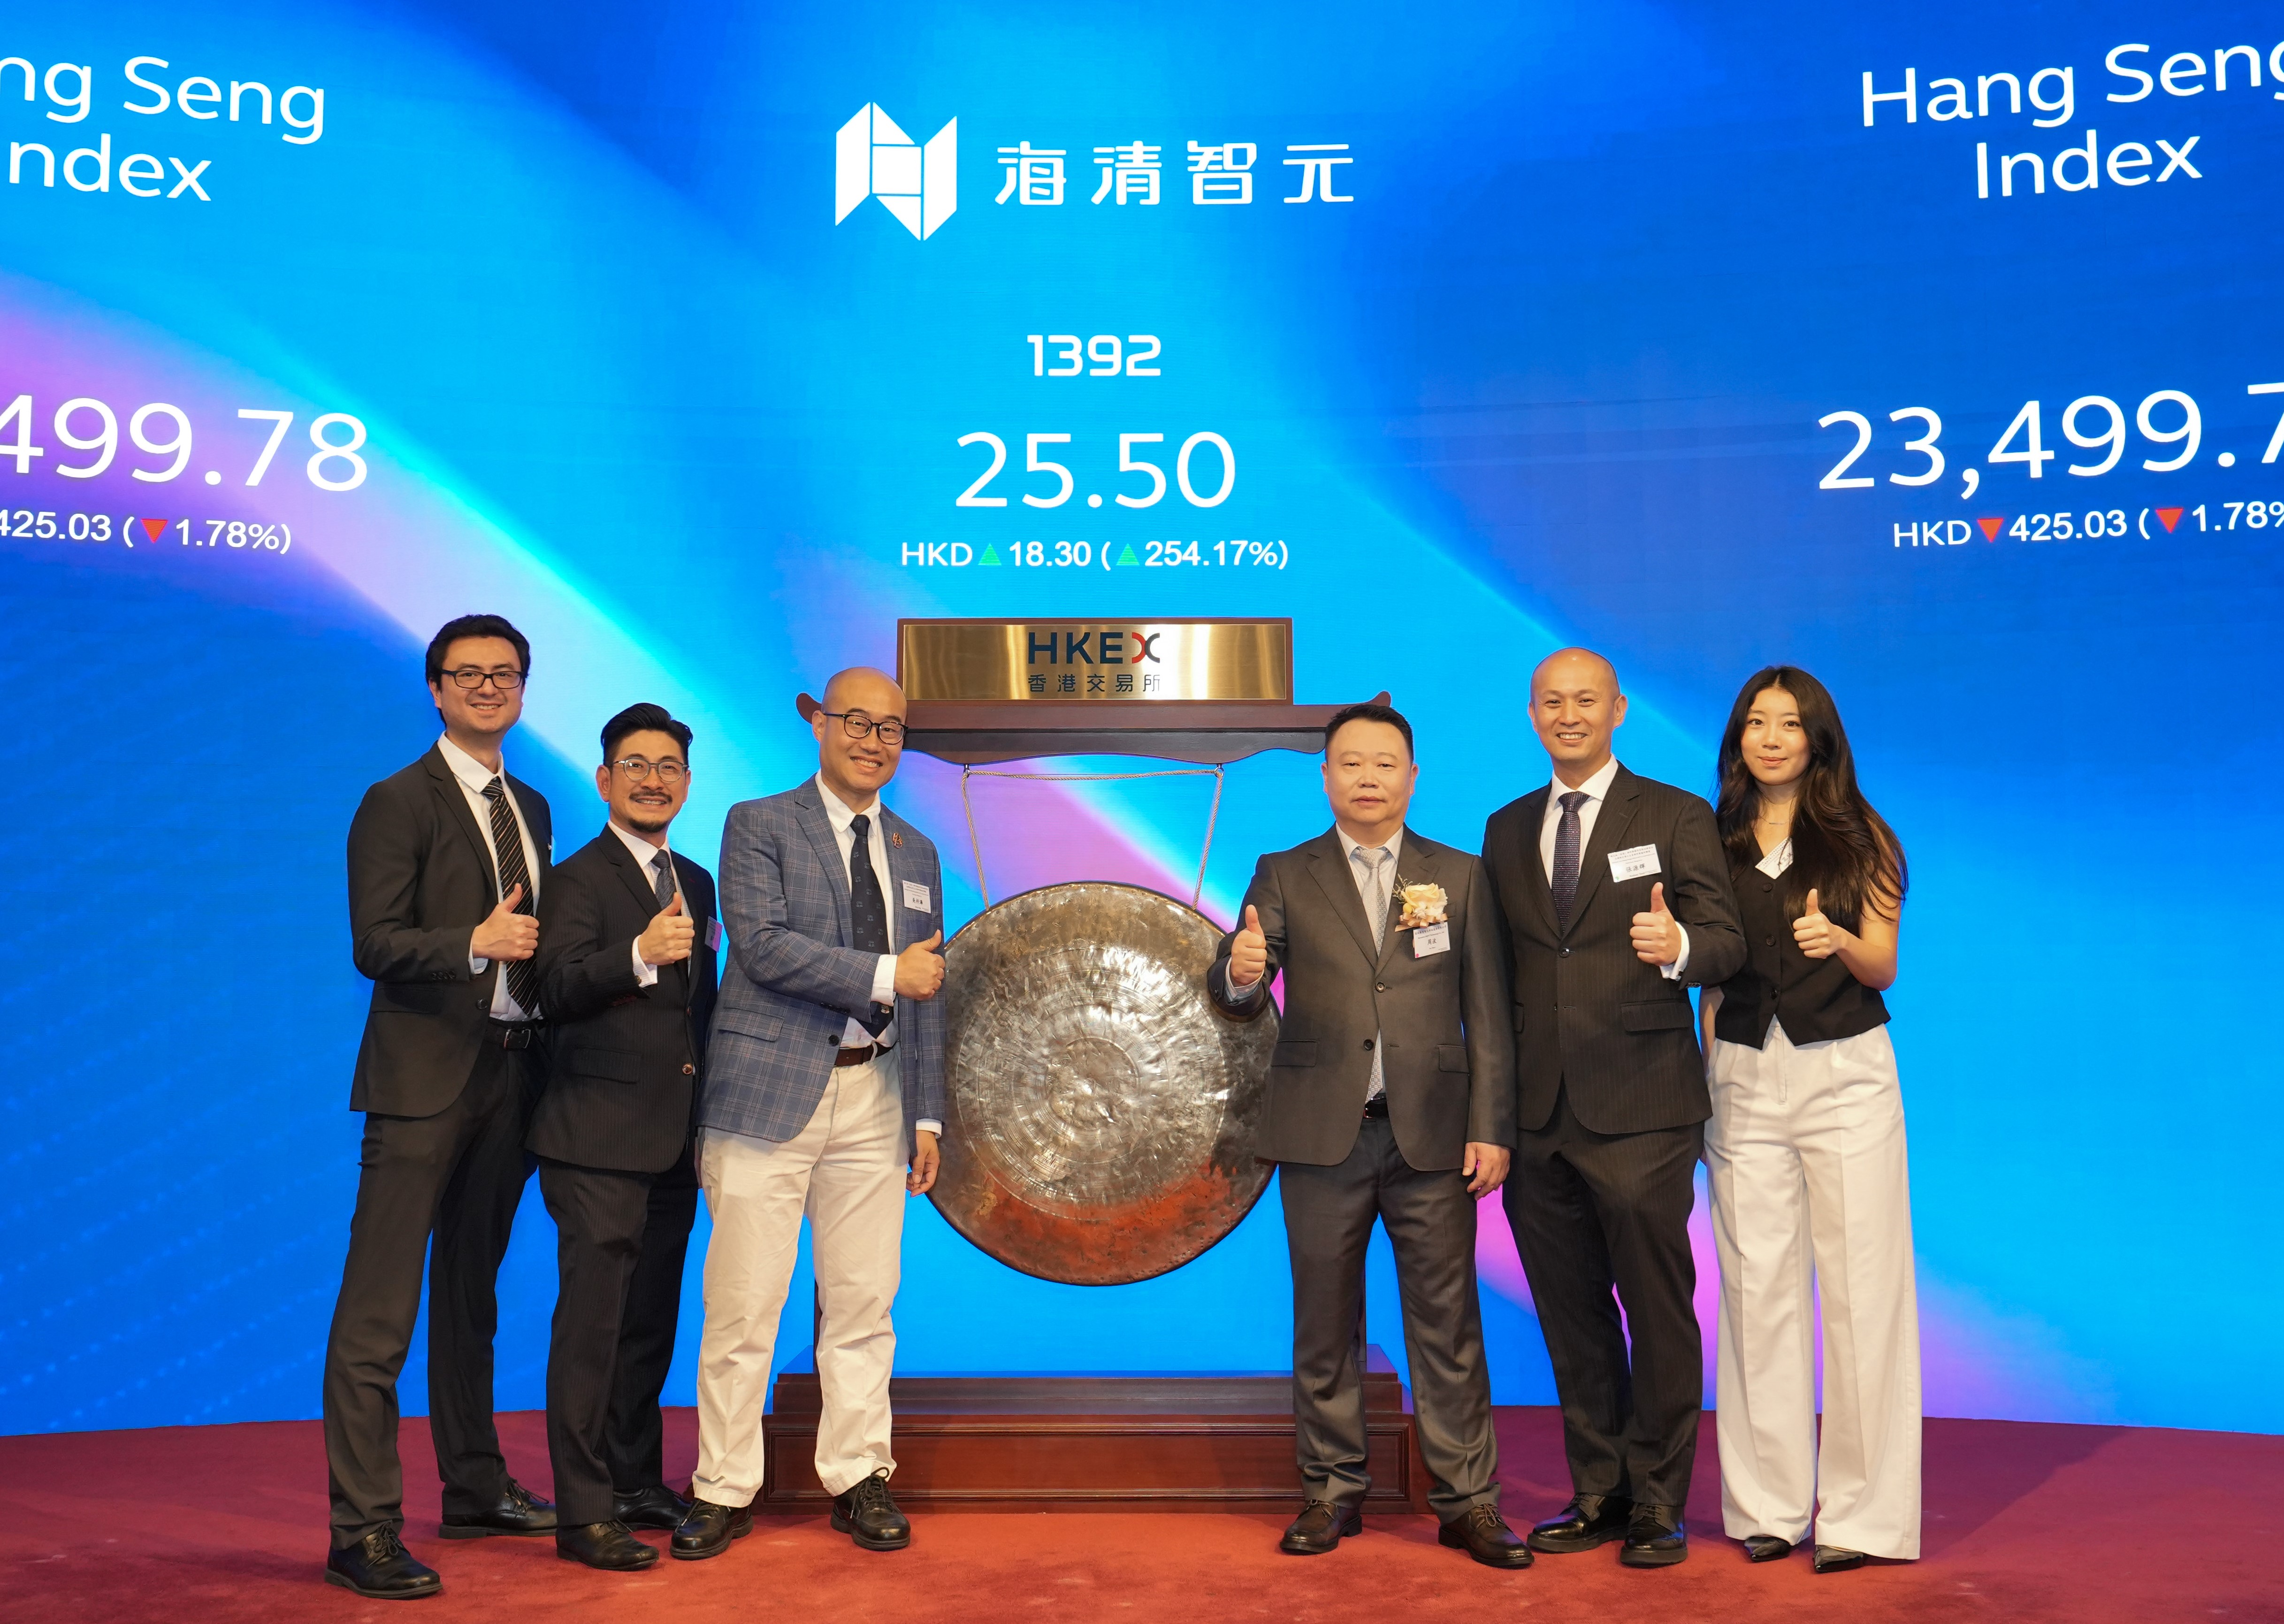
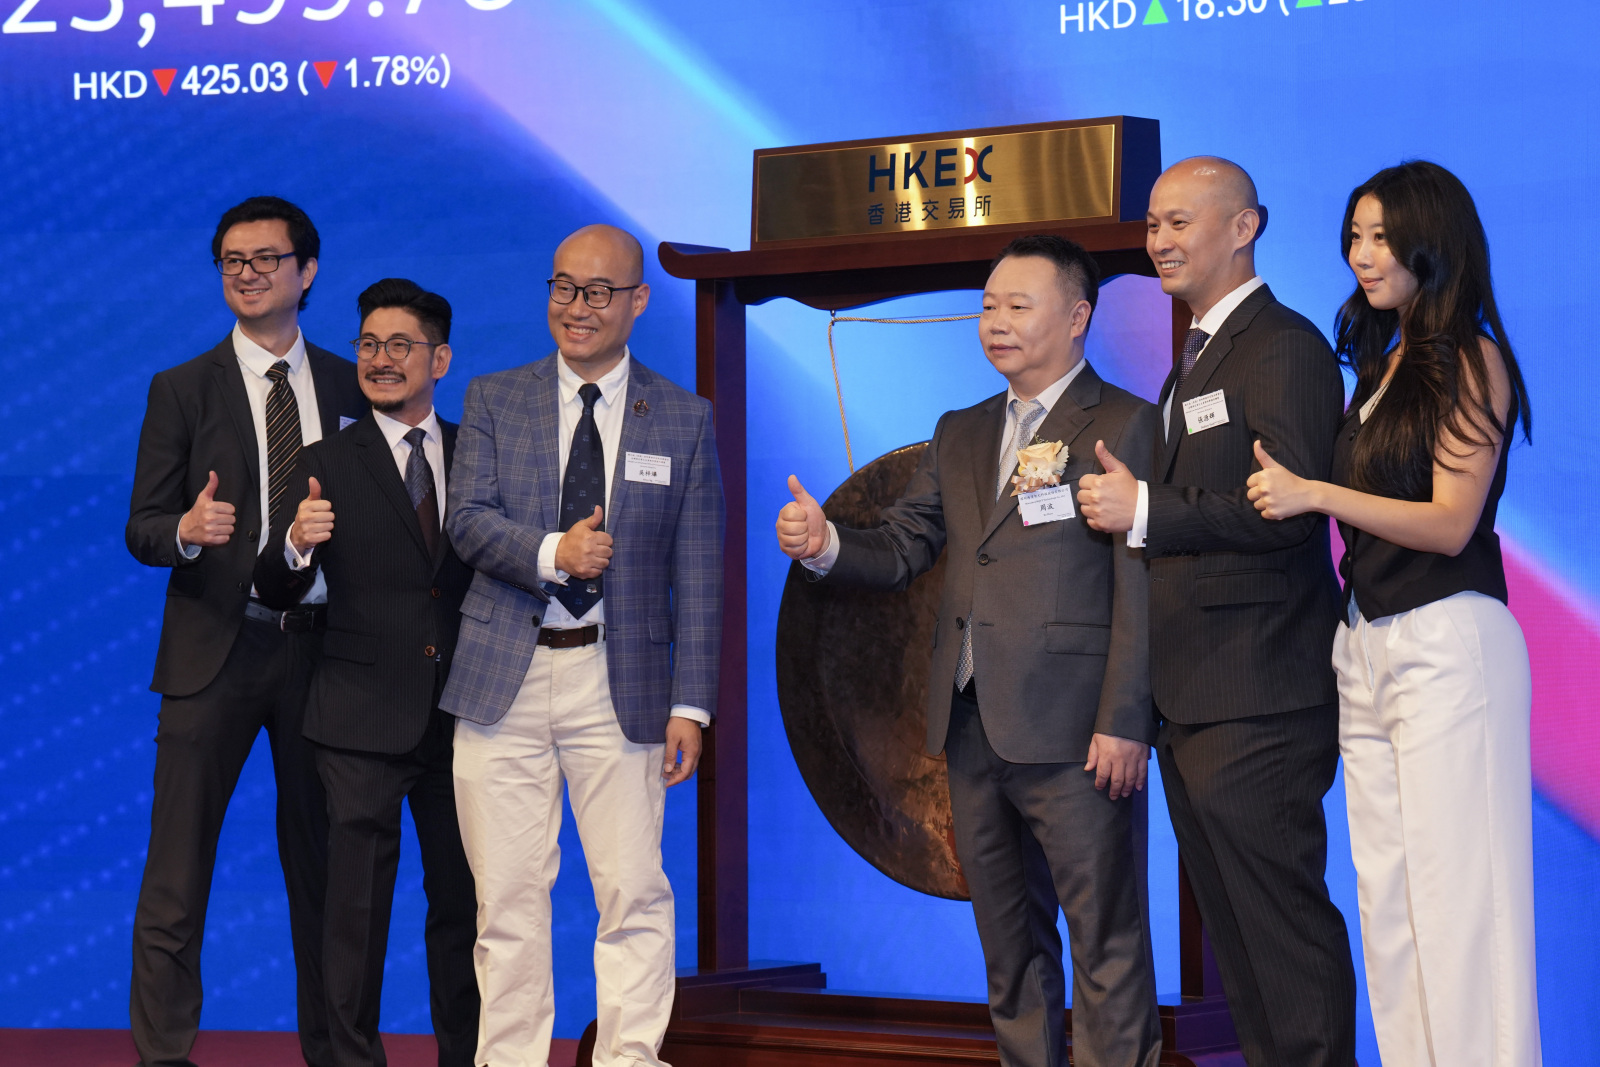
Our partner Rodney Teoh (2nd from the right) , senior associate Alroy Ng (3rd from the left), associates Clement Lai (2nd from the left), Xavier Wong (1st from the left) and trainee solicitor Christie Chan (1st from the right).
…
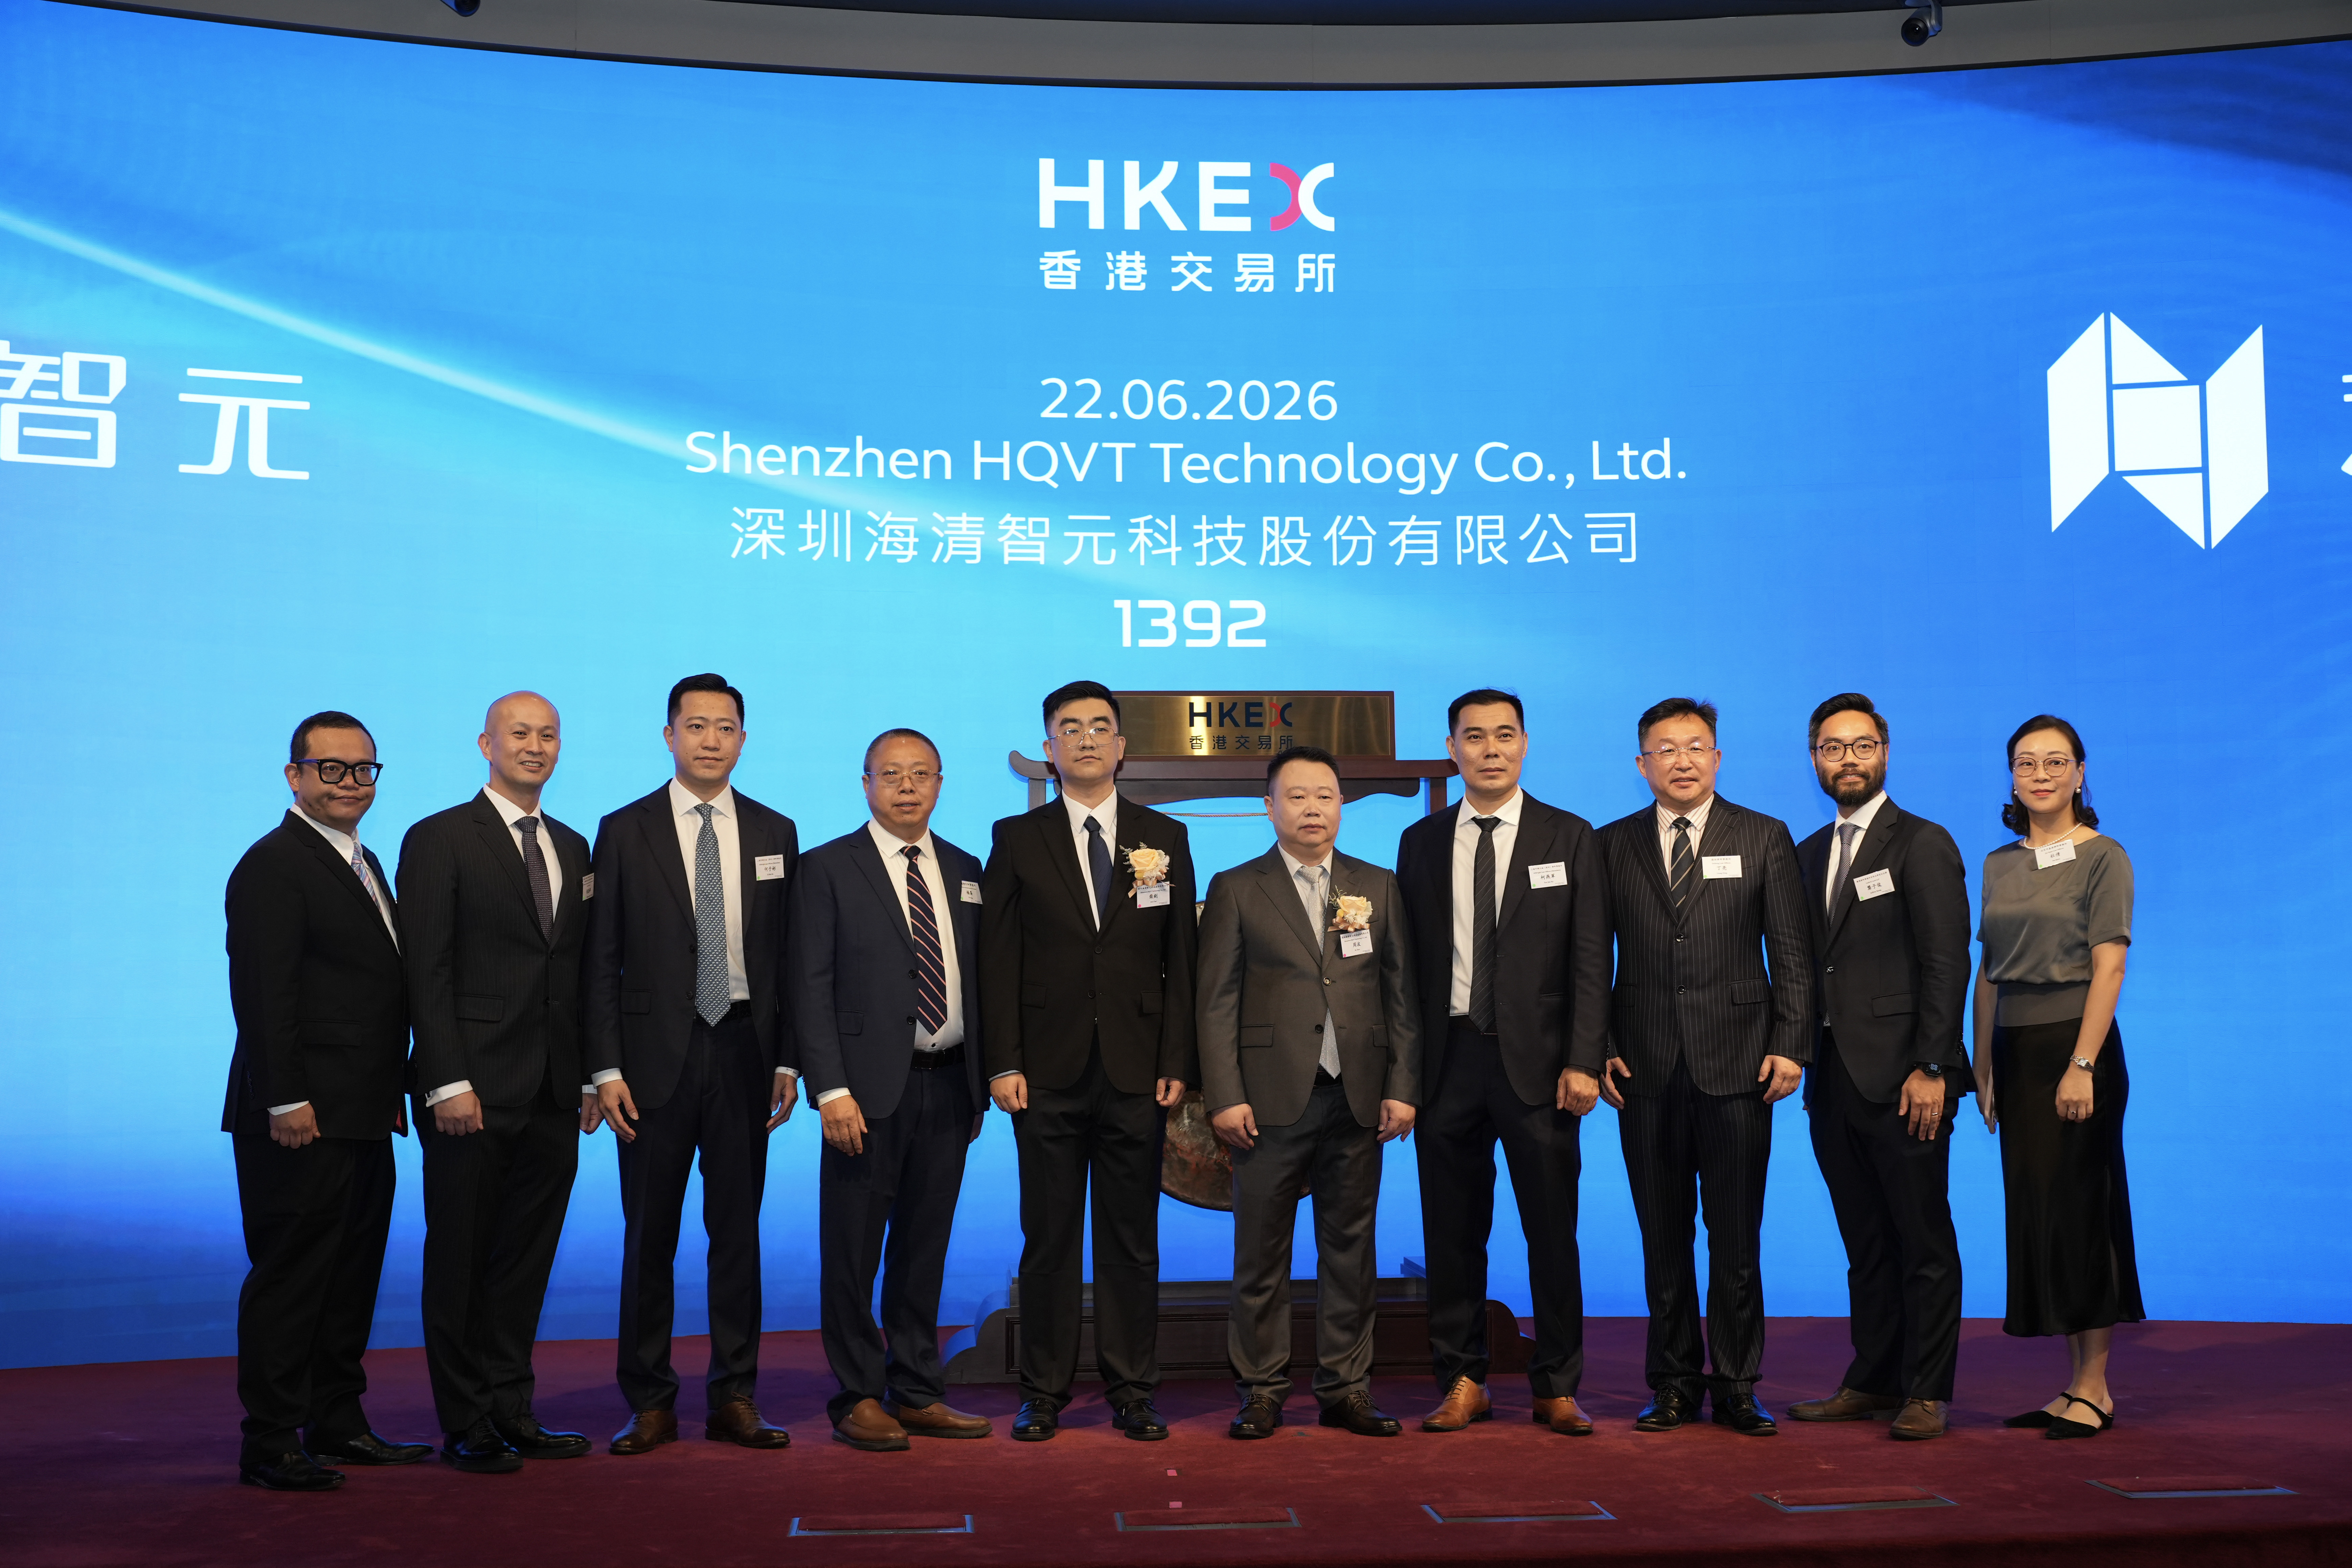
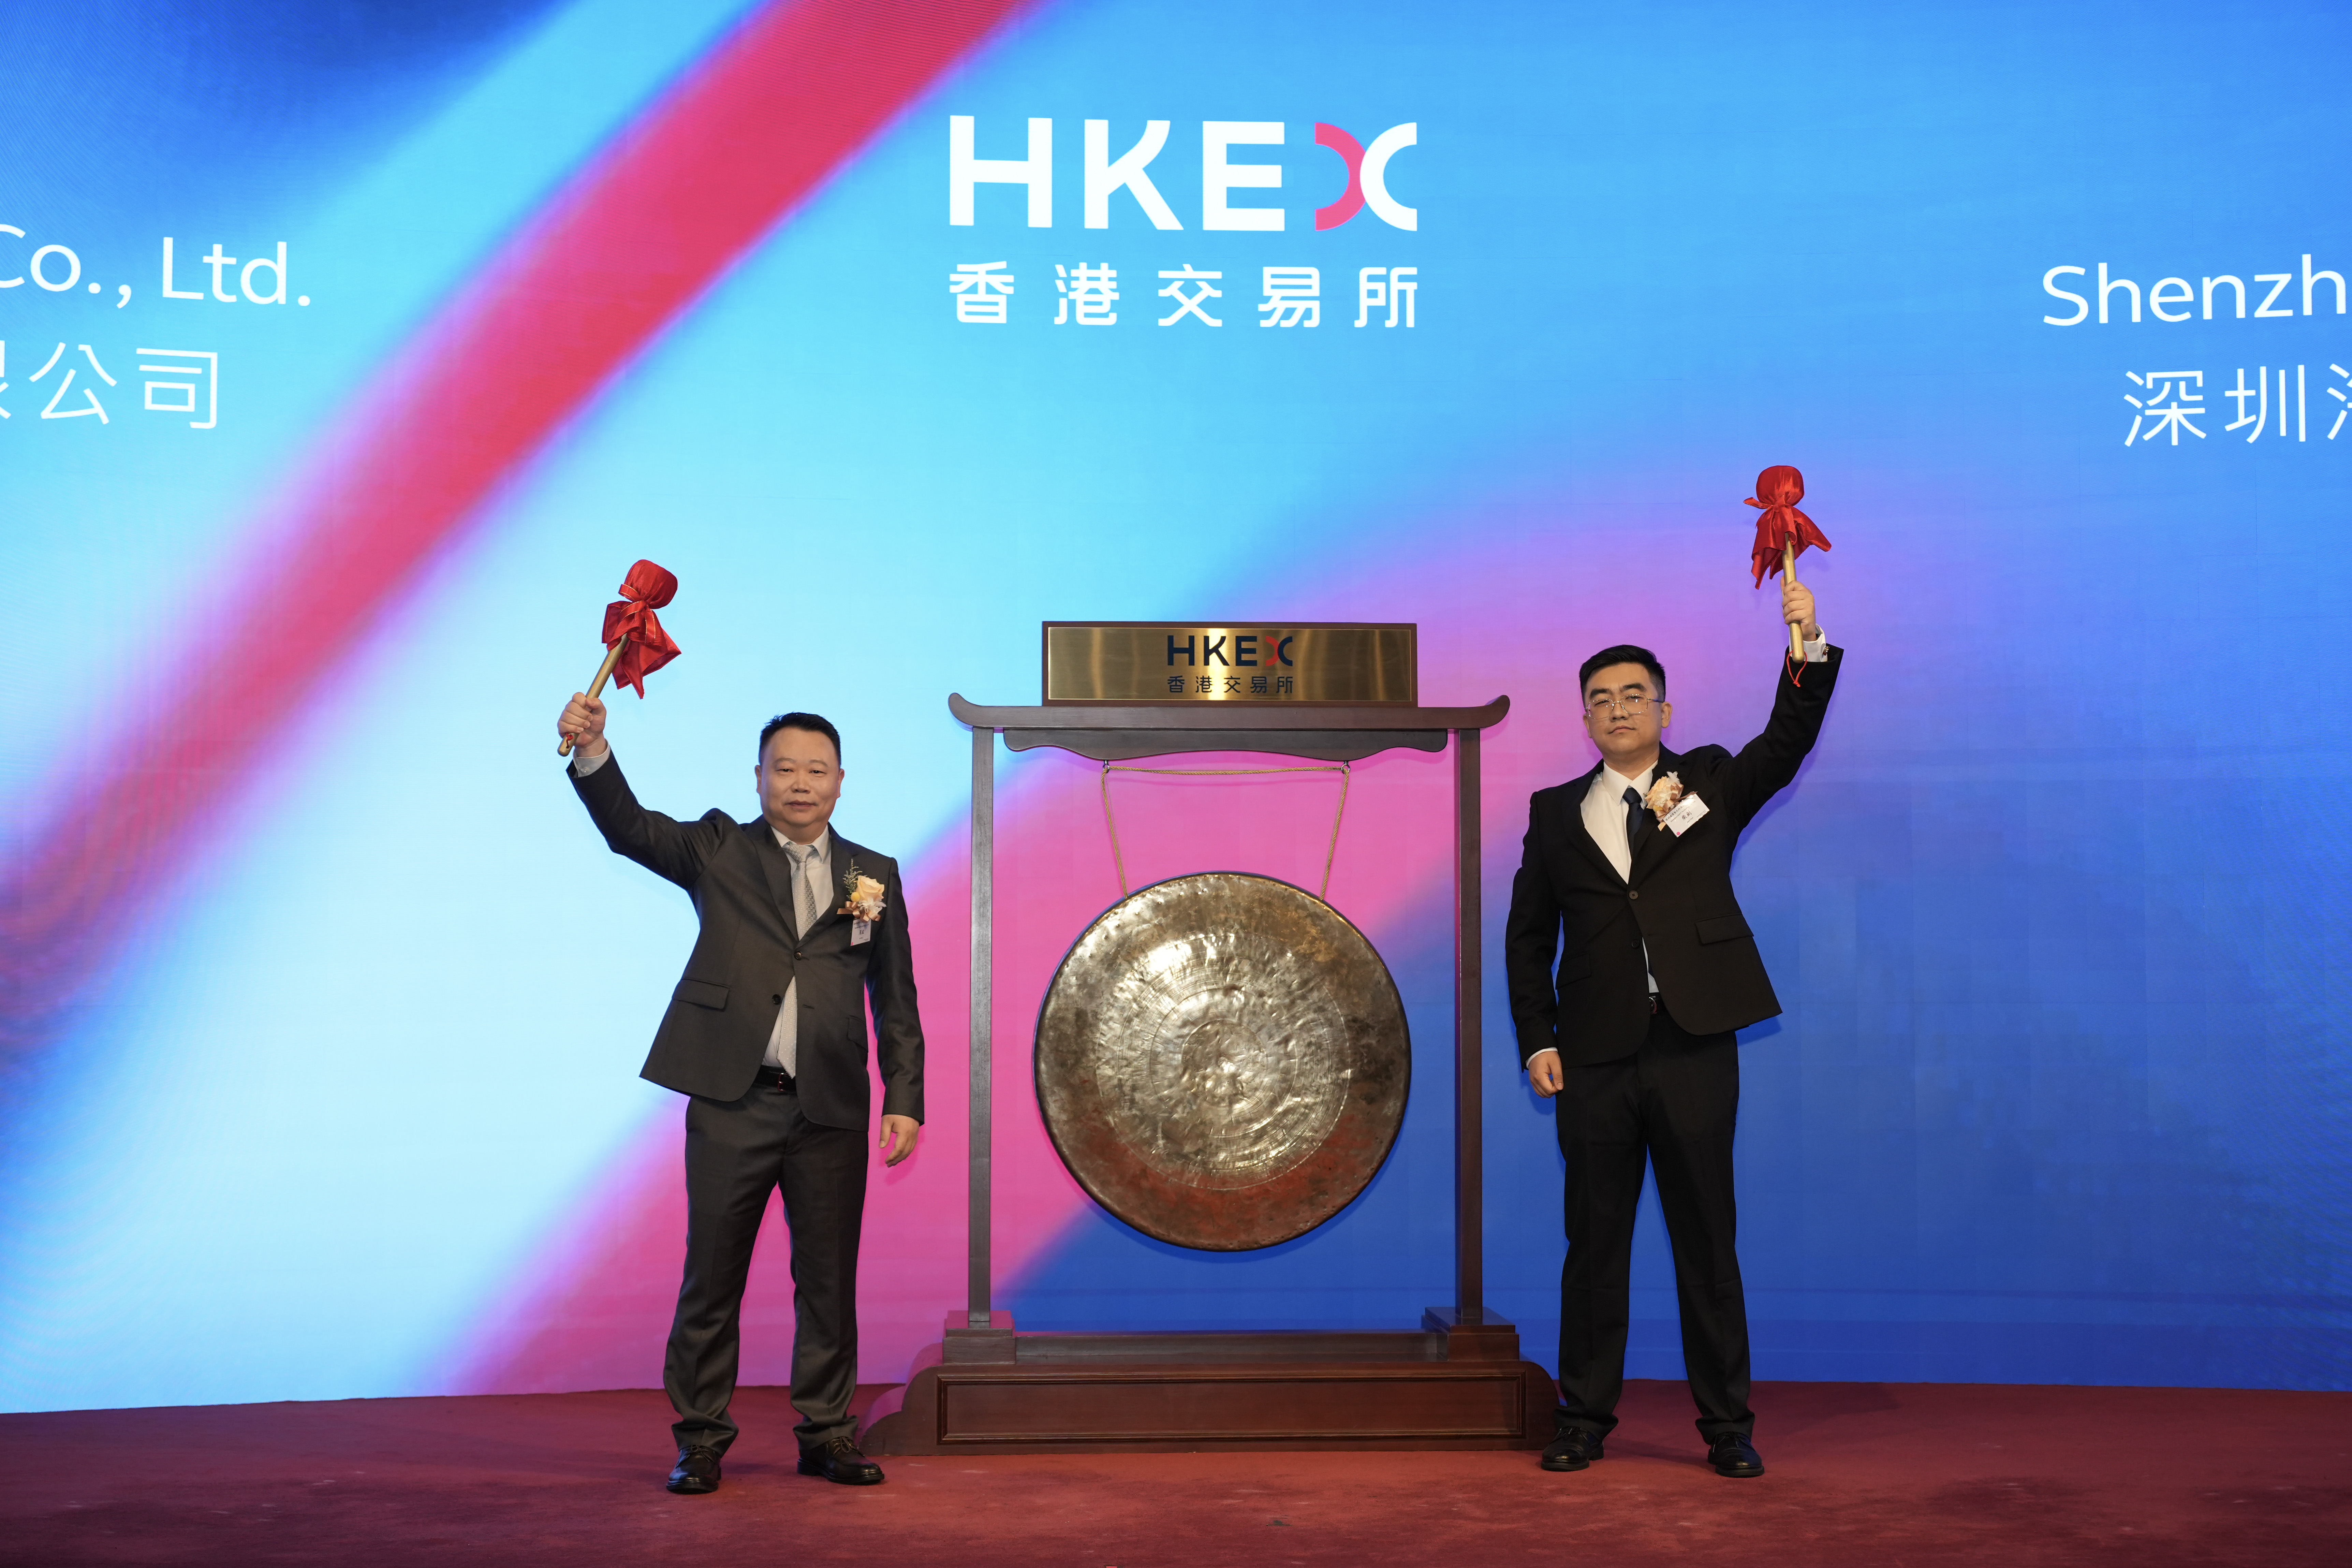
Stevenson, Wong & Co. (in association with AllBright Law (Hong Kong) Offices LLP) acted as the Hong Kong legal advisers to Shenzhen HQVT Technology Co., Ltd. (1392.HK) (“Shenzhen HQVT Technology”) in its successful listing on the Main Board of The Stock Exchange of Hong Kong Limited (the “Stock Exchange”).
The shares of Shenzhen HQVT Technology were listed on the Stock Exchange on 22 June 2026. Shenzhen HQVT Technology offered a total of 85,162,500 H shares, among which 8,516,500 H shares and 76,646,000 H shares were offered under the Hong Kong public offering and the international placing, respectively. The market capitalisation of the Company based on an offer price was HK$7.20 per share was HK$5,574.3 million. The gross proceeds from the global offering amounted to approximately HK$613.17 million.
Shenzhen HQVT Technology and its subsidiaries (the “Group”) are a leading multispectral AI technology enterprise in China. Since its inception, the Group leverages proprietary technology in multispectral perception and Al algorithms, to offer products and services designed to detect both visible and invisible spectral information to human eyes. The Group’s solutions deliver enhanced perception and safety monitoring, providing additional information decisions for multi-scenario safety and intelligent perception purposes for over 2,500 diverse customers who are mainly engaged in business related to software and information technology services, electronic products, information data centres (IDCs), intelligent driving systems, telecommunication operators, internet-of-things (IoT) system integration, and construction.
The joint sponsors of the listing were CMBC International Capital Limited and SPDB International Capital Limited. The overall coordinators were CMBC Securities Company Limited, SPDB International Capital Limited and Livermore Holdings Limited.
Our team was led by our partner Rodney Teoh, supported by team members including Alroy Ng (senior associate), Clement Lai (associate), Xavier Wong (associate) and Christie Chan (trainee solicitor).
Please contact our Rodney Teoh for any enquiries or further information.
 …
Stevenson, Wong & Co. is pleased to announce that the firm has once again been recognised in the Benchmark Litigation Asia-Pacific 2026 rankings, reflecting our continued strength in litigation and dispute resolution.
In this year’s edition, the firm has been ranked in the following five practice areas:
This recognition highlights the breadth of our disputes practice and the firm’s experience in advising on a wide range of contentious matters, including commercial disputes, insolvency-related proceedings, regulatory and white-collar crime matters, and private client disputes.
As a Hong Kong law firm with substantial local experience and cross-border capabilities, Stevenson, Wong & Co. remains committed to delivering practical, strategic and client-focused legal solutions to corporations, individuals, families and private clients.
About Benchmark Litigation
Benchmark Litigation is an international legal ranking guide dedicated to litigation and dispute resolution. Its Asia-Pacific rankings are based on independent research, including market interviews, client feedback, peer review and analysis of recent casework.
We would like to thank our clients and peers for their continued trust and support.
Please contact our Partners Willy Cheng, Heidi Chui, Dominic Lau, Katy Lai, Rainbow Ip, Michael Lau or Kenneth Leung for any enquiries or further information.
To view the full list of rankings, please click here.