News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
Introduction
The Primary Equity Connect (“PEC”) initiative is a key element of The Hong Kong Exchanges and Clearing Limited’s (“HKEX”) Strategic Plan 2016 – 2018, specifically to complete Mainland-Hong Kong Mutual Market connectivity of the equity market segment. The PEC aims to expand cross-border accessibility to the primary equity markets in both the Mainland and Hong Kong for mainland and global investors. This will be achieved by allowing Mainland investors to subscribe for Initial Public Offerings (“IPOs”) in the Hong Kong market via the PEC (Southbound) and global investors in Hong Kong to subscribe for IPOs in the Mainland market via the PEC (Northbound). It is believed that this initiative will be of mutual benefit to each market in view of the limited “internationalisation” development of both markets. Industry players have expressed interest in the PEC, in the belief that the initiative will improve market liquidity, expand investor base and attract sizable global IPOs. However, concerns have been raised regarding the PEC’s potential negative impact on both markets, as well as regulatory and operational complications relating to the implementation of the PEC. In response to such concerns, HKEX has released a research report seeking to elaborate and clarify the details of the PEC, to address the concerns, and to enhance public confidence and support for the initiative.
Background
HKEX has identified deficiencies currently faced by the Mainland and Hong Kong markets:
(a) A Mutual Market without primary market connectivity; and
(b) Developmental bottlenecks in Mainland and Hong Kong stock markets.
The table below summarises the deficiencies as presented by the HKEX:
|
Deficiency |
Details |
|
| (a) | a Mutual Market without primary market connectivity |
|
| (b) | Developmental bottlenecks in Mainland and Hong Kong stock markets | Mainland market:
Hong Kong market:
|
In light of the above deficiencies, HKEX proposes that the mutual market connectivity model with access to the primary equity market via PEC, supplemented by access to the secondary stock market via Stock Connect, will sufficiently remedy those deficiencies. The PEC will also provide various benefits to the Stock markets on both sides of the border, and contribute to China’s wider economic strategy of attaining a balanced economy, opening up the financial market, and fully realising RMB capital account convertibility.
Implications
The PEC’s potential benefits to both the Mainland and Hong Kong markets are detailed in the table below:
|
Potential Benefits |
||
|
Mainland Market |
Hong Kong Market |
|
| (a) | The PEC (Southbound) will open up an additional global asset allocation channel for Mainland investors, allowing them to subscribe to new shares of international companies to be listed in Hong Kong. As such, the overseas portfolio investment of Mainland capital will be enhanced. | Given the significant size of Mainland domestic savings and abundance of business opportunities in China, and that the PEC (Southbound) will allow Mainland investors to subscribe to IPOs in Hong Kong, this should attract international companies to list in Hong Kong. |
| (b) | The PEC (Northbound) will provide the Mainland with more opportunities for developing the international investor base in the domestic market. | Increased market liquidity in both primary and secondary market due to increased international listings and Mainland investor participation. |
| (c) | The PEC under the Mainland-Hong Kong Mutual Market model allows foreign issuers to abide by the internationalised rules and standards of the Hong Kong stock market, instead of needing to conform to the regulatory framework of the Mainland stock market. | More business opportunities to market intermediaries. |
| (d) | The PEC will provide more listing opportunities to Mainland enterprises, specifically to Mainland enterprises waiting in the Mainland IPO queue. Listing in Hong Kong is also a viable alternative for Mainland enterprises targeting a Mainland investor base, by virtue of the PEC (Southbound). | |
| (e) | The PEC (Southbound) allows Mainland investors to gain international experience of IPO shares subscription and price movements upon listing, thus helping to nurture the Mainland investor base. | |
| (f) | The closed-loop system of the PEC will alleviate risks of capital outflow | |
| (g) | Accelerate RMB convertibility | |
However, there are legitimate concerns in connection to the implementation of the PEC. Sound market regulations for the PEC will have to be established to ensure a fair environment for investors, and to provide adequate investor protection and risk control. This may include eligibility criteria for issuers and investors, and obligations and liabilities of interested parties such as exchanges, market regulators, intermediaries, issuers and investors on both sides of the Mutual Market. Additional disclosure requirements may also need to be imposed for both IPOs under PEC (Southbound) targeting Mainland investors, and IPOs under PEC (Northbound) offered to local and global investors in Hong Kong. A coherent and well-constructed regulatory framework will ensure that regulatory incidents relating to issuers under PEC which impact investors’ interests could be minimised and resolved.
Operational concerns, such as those relating to IPO procedures and general market practices were raised:
(a) whether cross-border retail investors will be allowed to subscribe for PEC shares, or will PEC shares only be open to cross-border institutional investors;
(b) how PEC shares will be allotted to cross-border investors;
(c) whether there will be a separate subscription pool for cross-border subscription, or a combined pool with domestic market subscription;
(d) whether cross-border subscription be subject to different market rules or follow the IPO home market rules;
(e) whether cross-border investors be served by intermediaries in the IPO home market or in the investor’s market; and
(f) whether intermediaries serving cross-border investors be subject to different regulatory requirements, such as Know-Your-Client rules and placement guidelines.
For example, with regards to (a), if the PEC allows retail investors in the Mainland to subscribe for IPO shares, it may entail additional regulatory requirements for the listing company, as this will be deemed as a mainland public offering. This will foreseeably lead to increased time and costs for the listing company. Conversely, if the PEC only allows institutional investors in the Mainland to subscribe for IPO shares, the listing will be exempt from those regulatory requirements. Such operational uncertainties must be properly remedied to preserve market fairness and integrity.
It is anticipated that with considerable effort, a suitable model design catering to the best interests of the Mainland-Hong Kong Mutual Market will be able to effectively address the regulatory and operational concerns, and the PEC will be a successful endeavour benefitting both the Mainland and Hong Kong markets.
This newsletter is for information purposes only. Its content does not constitute legal advice, and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage.
Please contact our Eric Lui or Rodney Teoh for any enquiries or further information.
1 Refer to HKEX Research Report “Primary Equity Connect – A Breakthrough Opportunity for Mainland-Hong Kong Mutual Market Connectivity and RMB Internationalisation” pp 7; and CSDC Monthly Statistics, CSDC website, December 2016
2 Refer to HKEX Research Report “Primary Equity Connect – A Breakthrough Opportunity for Mainland-Hong Kong Mutual Market Connectivity and RMB Internationalisation” pp 7; and Southwest Securities research report on QFII 2017Q1 shareholding status, 1 May 2017
3 Refer to HKEX Research Report “Primary Equity Connect – A Breakthrough Opportunity for Mainland-Hong Kong Mutual Market Connectivity and RMB Internationalisation” pp 10 – 11 and Figure 7
We are delighted to announce that our Partner and Head of Litigation and Dispute Resolution Department Ms. Heidi Chui has been appointed by The Honourable Chief Justice Geoffrey Ma, the Chief Justice of the Hong Kong Court of Final Appeal as a Practising Solicitor Member of the Solicitors Disciplinary Tribunal Panel in October 2017 for a term of three years.
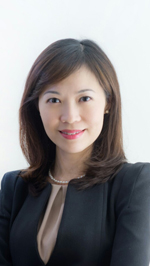
The Solicitors Disciplinary Tribunal deals with specific disciplinary cases brought by The Law Society of Hong Kong against any person who is, or was at the relevant time, a solicitor, a registered foreign lawyer, a trainee solicitor or an employee of a solicitor or a registered foreign lawyer of Hong Kong for alleged professional misconduct.
Ms. Heidi Chui is an Arbitrator (on the panel list of the Law Society of Hong Kong), Fellow of the Chartered Institute of Arbitrators (U.K.) and an Accredited General Mediator with both the Hong Kong International Arbitration Centre and the Law Society of Hong Kong. She is also a member of the Arbitration Committee of The Law Society of Hong Kong. She is a China Appointed Attesting Officer.
Please contact Ms. Heidi Chui for any enquiries or further information.
On 9 October 2017, SW partners Mr. Hank Lo, Mr. Eric Lui, Ms. Erica Cheng and Mr. Stephen Wong attended the 10th listing anniversary celebration dinner of China Aoyuan Property Group (“Aoyuan”) held at the Shangri-La Hotel Guangzhou. More than 1,000 guests from foreign investment institutions, financial institutions, media, strategic partners of Aoyuan and industry associations attended the event.
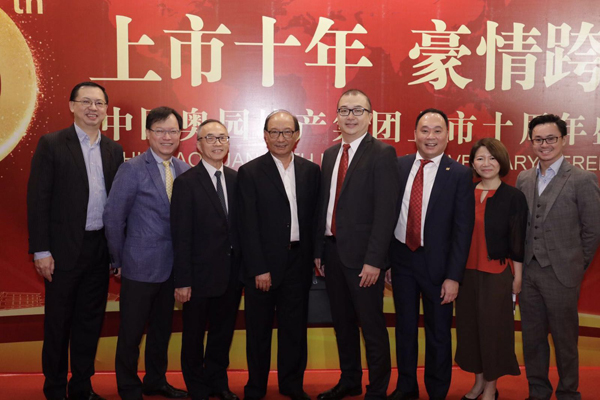
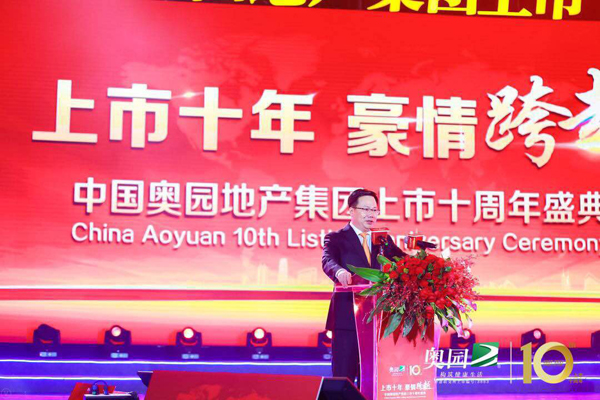
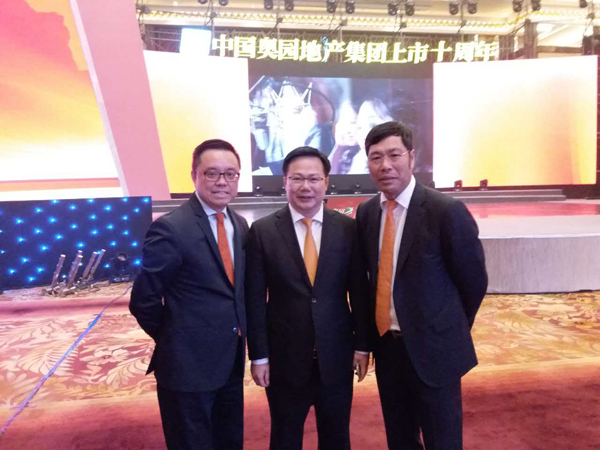
Aoyuan is a company listed on the Main Board of The Stock Exchange of Hong Kong Limited (stock code: 3883) and has established a long-term working relationship with our firm.
Please contact Mr. Hank Lo, Mr. Eric Lui, Ms. Erica Cheng or Mr. Stephen Wong for any enquiries or further information about this event.
On 27 September 2017, our partner Mr. Stephen Wong was invited by “zhi10.com” to host an E–class with the topic “How to Obtain a Financial License in Hong Kong”.
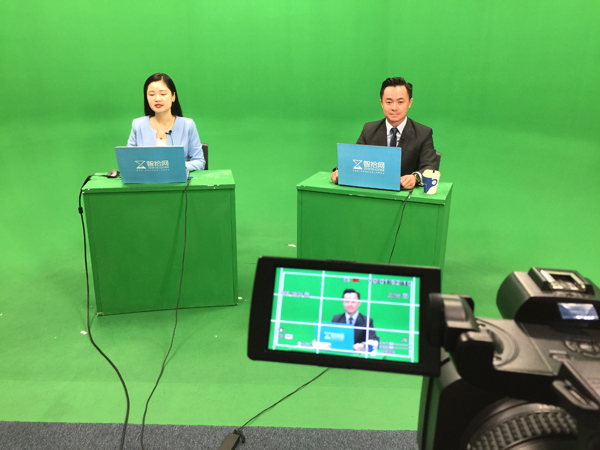
Mr. Wong shared six issues of Hong Kong financial license including license application; financial resources; management structure; full licensed representatives, responsible officers, substantial shareholders, senior officers and the others; and additional requirements of Type 6 and 9 licenses applications. Mr. Wong hopes that people and enterprises have better understanding about Hong Kong financial license through this online seminar.
The E-class received positive feedback and the registered users of “zhi10.com” can watch the recorded seminar online.
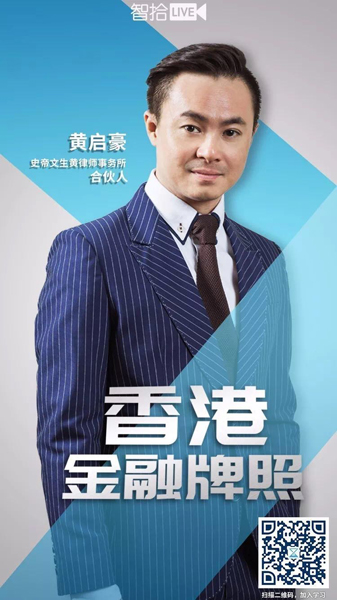
“zhi10.com” is a renowned online legal education platform in mainland China, which has previously invited a number of distinguished practitioners from top law firms. Having a strategic association with AllBright Law Offices, one of the nation’s best law firms, Stevenson, Wong & Co. has a profound experience and knowledge in both China and Hong Kong with a comprehensive network in the two jurisdictions. SW was delighted to have the opportunity to give the online seminar for “zhi10.com” and the firm looks forward to joining more events to connect with mainland China.
Please contact Mr. Stephen Wong for any enquiries or further information about this seminar.
The award ceremony of 2017 Deloitte Technology Fast 20 (TF20) and Rising Star Programs was successfully held in the Auditorium of Hong Kong Exchanges and Clearing Limited on 27 September 2017. Mr. Hank Lo, our partner and head of Corporate Finance, is honoured to be invited to the event and presented the awards to the top five winners of the TF20 program. They are WeLab Holdings Limited, SenseTime Group Inc., GoGo Tech Holdings Limited, MoneyHero Global Limited and Weigang Holdings (Hong Kong) Limited.
For the Rising Star Program, 10 companies including Klook and TNG (Asia) Limited have been recognised for their viable business models and strong growth potentials. The winners came from a wide spectrum of industries, including FinTech, artificial intelligence, software, hardware, biotech, media and e-commerce.
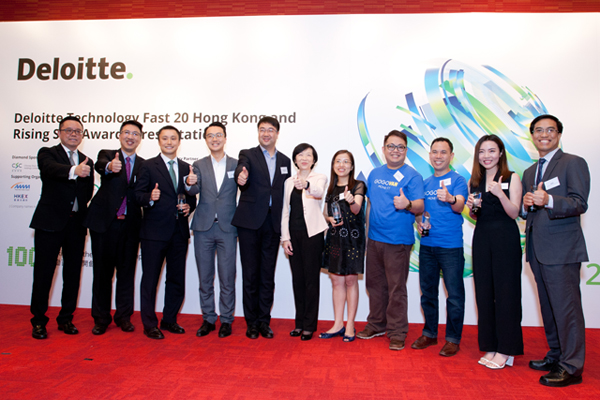
Mr. Hank Lo (first from the left) and the representatives of the top five winners of the TF20 program
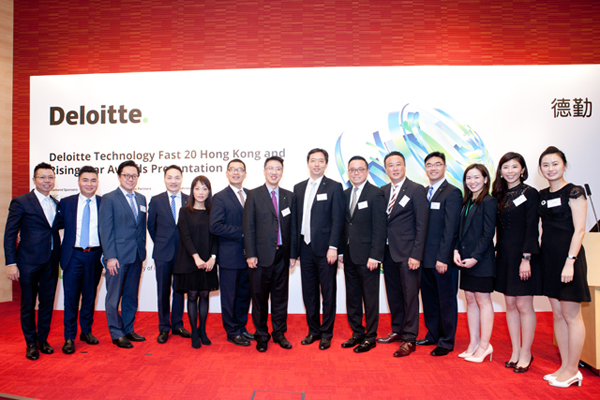
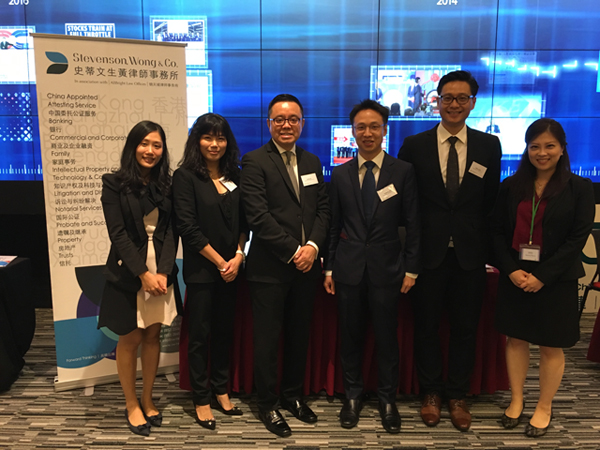
From left to right: Ms. Cecilia Wong, Ms. Cornelia Chu, Mr. Hank Lo, Mr. Terence Lau, Mr. Peter Loo, and Ms. Christine Cheung
“Stevenson, Wong is proud to be the diamond sponsor of the TF20 program. We are convinced that technology is only going to play a more and more important role in the ecosystem and competitiveness of a business. We want to be part of the process and support tech start-ups in Hong Kong leveraging on our wealth of experience in fund raising and IPOs,” said Mr. Lo.
Please contact Mr. Hank Lo, Ms. Cornelia Chu or Mr. Terence Lau for any enquiries or further information about this event.
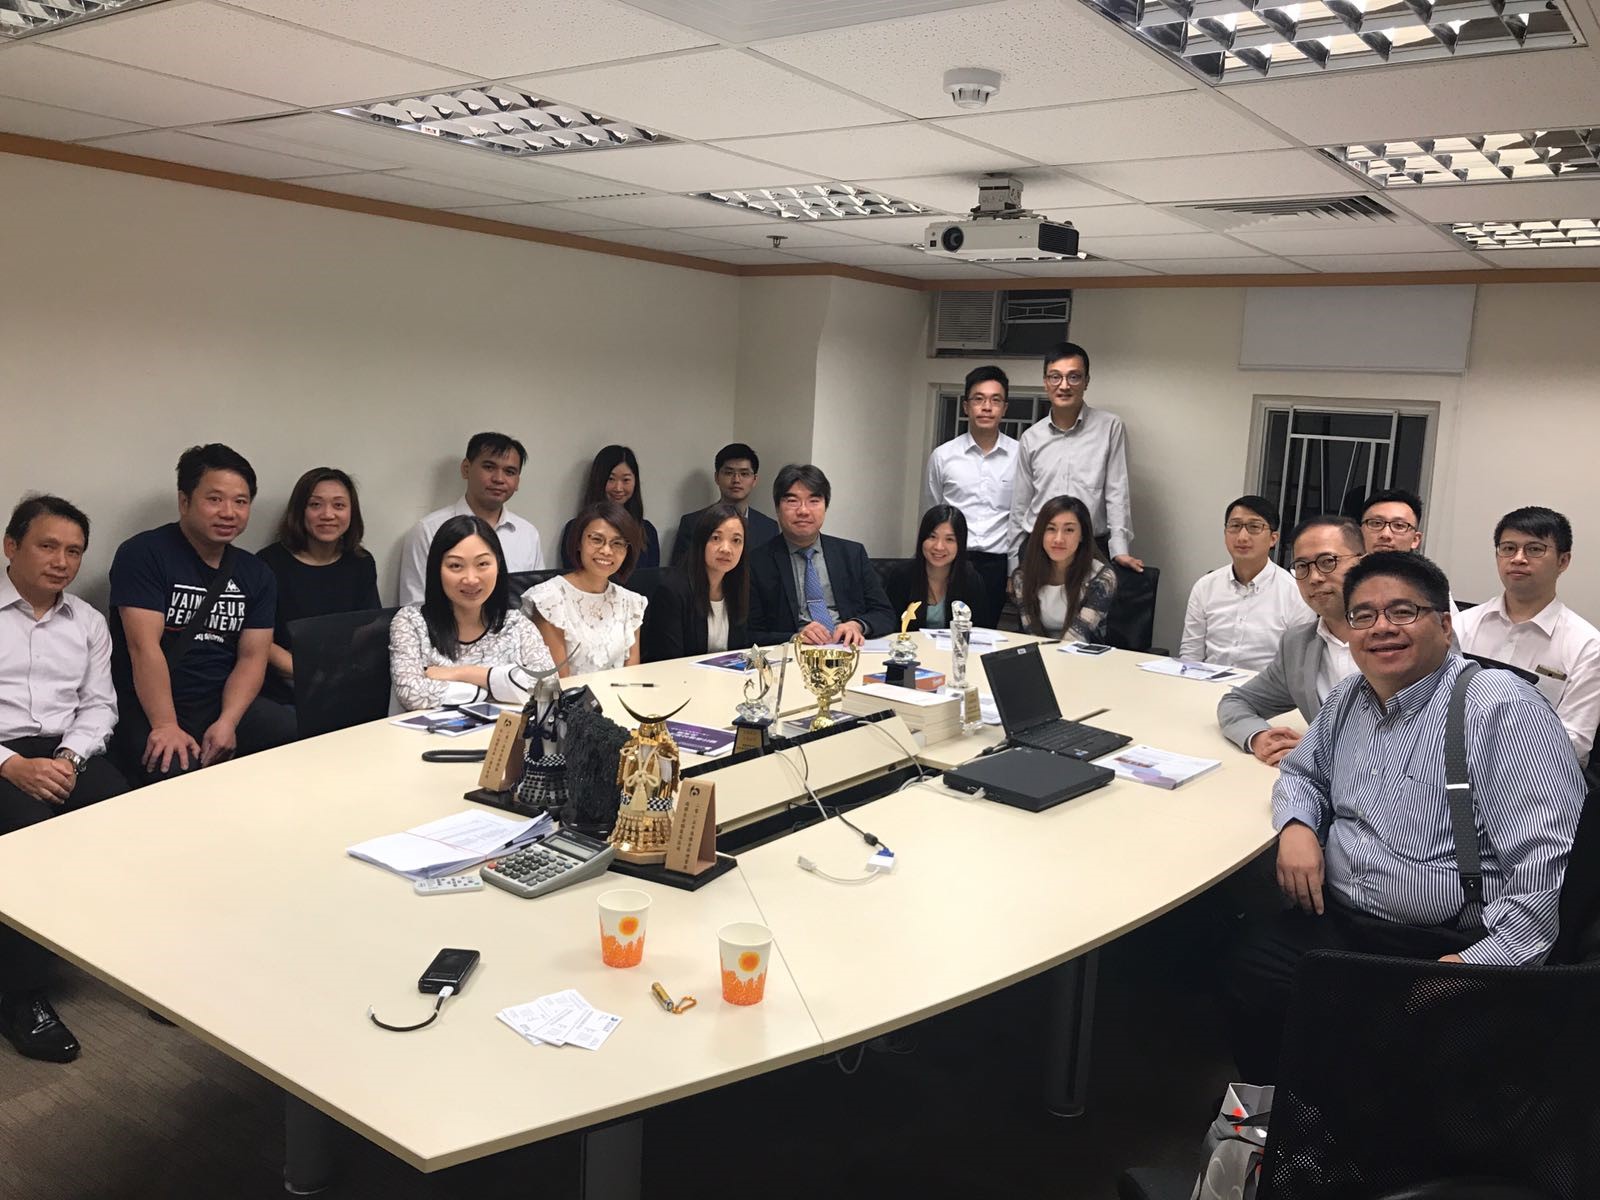
On 25 September 2017, our legal executives from our Banking Department, Mr. Man Wong and Ms. Hebe Au were invited by Bank of Communications (Kowloon Business Services Centre) to present the topic of “The Risk and Consideration for Banks in respect of Mortgages for Village Houses in New Territories”. The seminar was attended by approximately 20 Business Services Managers. The seminar covered issues when acquiring small houses in the New Territories such as building procedures, risk assessment of mortgage, rights-of-way, illegal acquisition of small houses and unauthorized building works.
Please contact our Mr. Eric Lui or Mr. Wong for any enquiries or further information about this event.