News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.

News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
On 19 December 2022, the Financial Services and the Treasury Bureau (“FSTB”) published a consultation paper (the “Consultation Paper”) on proposals relating to enhancing regulation of crowdfunding activities in December 2022. In particular, the FSTB seeks to establish a Crowdfunding Affairs Office (“CAO”) to govern and coordinate the approval, registration and administrative framework of crowdfunding activities i. The FSTB is seeking market feedback on its proposals by 20 March 2023.
…
Definition of “crowdfunding”
“Crowdfunding activities” refers to “those conducted by an individual, a group or an organisation for openly appealing to a large number of individuals or organisations to each contribute usually a small amount of money for a specific fundraising purpose, so that the fundraiser may have sufficient funding to carry out a project, a business or meet the needs in respect of that purpose” ii.
The receipt of certain benefits or returns upon a competition of a crowdfunding activity is not a definitive feature. Some fund contributors may not expect any personal returns if they care only about the pursuit of the purpose of the activity iii .
A non-exhaustive list of the major common types of crowdfunding activities is set out as follows iv:
(1) Equity or debt crowdfunding: fund contributors invest in a project or a business, usually a start-up, in return for equities or debts issued by a company, or profits or income of a Collective Investment Scheme (“CIS”);
(2) Peer-to-peer lending (“P2P lending”): fund contributors provide unsecured loans to individuals or projects through online platforms that match them with borrowers, from which interests are earned;
(3) Donation-based crowdfunding: fund contributors make donations to (non-) charitable activities or causes they support without getting any specific returns; and
(4) Reward/pre-sale crowdfunding: fund contributors give funds to fundraisers to help them develop or produce physical goods or services, while receiving in some form the goods or services in return.
Background Issues
Hong Kong has regulatory measures over fundraising activities that invite fund contribution from the general public. Depending on the actual mode of operation of the fundraising activity, fundraisers may be required to obtain a permit or licence. Currently charitable fundraising activities, non-charitable fundraising activities conducting in public places, sale of goods in public places for the purpose of fundraising and lottery fundraising activities are subject to regulations v . It should be noted that other crowdfunding activities may or may not be regulated by the current regulatory measures.
Online crowdfunding activities, which allow fundraisers to raise funds conveniently and at lower costs and to attract a larger pool of potential fund contributors in a flexible manner, have been catalysed as a result of the widespread use of communications technology and online platforms. Given the more diverse nature and contexts of application involved in crowdfunding, the risks of conducting online crowdfunding activities are stated below vi :-
| Risks of crowdfunding platforms | Both the fundraisers and fund contributors may not be able to recover their funds if the online crowdfunding platform cease operation due to various reasons. |
| Risks of information asymmetry | Fund contributors could not help but to rely on the information provided by fundraisers in making their decisions to contribute funds which can be inaccurate and thus suffer losses in the case of a delayed or unsuccessful projects. |
| Risks of fundraising outcome not in line with fundraising purpose | Fund contributors may not be able to hold anyone accountable if the funds so raise are eventually used for purposes other than those committed by the fundraisers if the crowdfunding activity does not necessarily have to undergo due diligence and continuous supervision. |
| Risks of breaching the law | In the absence of regulation, fund contributors may have to bear criminal liability if the crowdfunding activity is used as a means to raise funds or launder money for illegal activities. |
The risks of online crowdfunding activities magnify the underlying issue that Hong Kong does not have a dedicated regulatory authority to deal specifically with the more diverse types of crowdfunding activities, in particular the online ones. The FTSB therefore identifies the necessity to enhance regulations over crowdfunding activities.
Proposed Measures to Regulate Crowdfunding Activities
A Crowdfunding Affairs Office (“CAO”) is proposed to be established to centrally process and coordinate regulatory and administrative matters, and monitor the conduct of crowdfunding activities vii. The key function of the CAO is to process crowdfunding applications not covered by the existing legislation. In other words, all fundraising activities, be they online or offline, are required to apply in advance to the CAO.
The CAO as the central authority will take up the responsibility to receive all the applications submitted for conducting crowdfunding activities, refer them to the relevant government departments by their types, coordinate the approval process, issue guidelines and collect the completion records of crowdfunding acitivites and publishing these records for public inspection as appropriate viiii .
Under the proposed regime, a fundraiser who intends to publicise a crowdfunding activity that raises funds from individuals or entities of Hong Kong, or individuals or entities located in Hong Kong, must make an application to and obtain a prior approval from the CAO before conducting the activity, regardless of whether he is not in Hong Kong or not, or whether the fundraiser is an entity established in Hong Kong or not ix .
If a person starts to conduct a crowdfunding activity before applying to the CAO in accordance with the established procedures or before obtaining a prior consent, a prohibition order to discontinue the activity will be issued to the fundraiser. As the case requires, a fine can be imposed on and prosecution action can be taken against the fundraiser x .
When processing applications, the CAO will take into account reliability of the individuals involved, the risks of the activity that might give rise to illegal conducts or endangering public interests, public safety and national security before giving approvals. The honesty, reputation and reliability of the applicant will particularly be placed with more emphasis if the fund size the number of fund contributors are large xi .
In making an application, an applicant shall bear in mind the following obligationsxii :-
(1) State clearly the set-up and arrangement of the activity based on the purpose and nature of the fundraising activity;
(2) Keep proper records of fund movements and disclose the use of funds raised;
(3) Provide relevant records and other information related to the crowdfunding activities upon the requests made by the CAO and relevant law enforcement agencies; and
(4) Actively consult and seek assistance from the relevant financial institutions in regard to the practical operation of the requirement for fund contributors making donations in their real name, upon the request from the CAO.
Upon getting an approval, the applicant must publish the approval number on all documents or advertisements related to the crowdfunding activity, and obtain information on the identities of persons donating funds from any crowdfunding platforms, financial institutions or payment service providers they cooperate with xiiii .
Set out below are the fundraising activities that are regulated under the existing regulatory regimes and hence excluded from the proposed regulatory regime:-
(1) Fundraising activities that are regulated by the Securities and Futures Commission (the “SFC”) under the Securities and Futures Ordinance (Cap 571), including any fundraising via issuance of equity or debt “securities”, P2P lending business involving “CIS” and any fundraising which amount to “regulated activities” that falls under the statutory regulation functions of the SFC xi ; and
(2) Fundraising activities that are regulated by the Monetary Authority under the Banking Ordinance (Cap 155), including banking activities such as deposit-taking and the making of loans and advances xv .
Other fundraising activities in the community that are substantially different in nature from the crowdfunding activities intended to be subject to the enhanced regulation are also excluded:-
(1) Calls that religious bodies make to their followers for donations on religious grounds, such that the calls for making regular donations on contributing to festive activities held on the ground of religious doctrines xvi ;
(2) Activities that recognised associations solicit funds from members, with a view to promoting the welfare and needs of respective trade members xvi ;
(3) Buying and selling of goods or services readily available in the market, even though the buying and selling may be conducted online and may involve recruiting people to buy as a group xvii ; and
(4) Commercial activities on online media and the like that involve income from subscriptions or online awards xix .
It should be noted that even if the crowdfunding activity falls under any of the above exemption categories, the CAO nevertheless reserve the right to direct it to apply for the conduct of such activity following the normal procedures. In any event the exclusion of the above exemption categories from the crowdfunding approval and registration system does not mean they will not be regulated, for instances, those involving other criminal conducts such as fraud xx.
Proposed Registration System for Online Crowdfunding Platforms
The FSTB is inviting public views to consider whether a registration system should be established for online crowdfunding platforms to register with the CAO given that many of them are set out outside Hong Kong.
Set out below are the functions the proposed registration system for crowdfunding platforms is expected to perform xxi :-
(1) Providing adequate background information of the company, organisation or individual operating the platform for reference by crowdfunding participants;
(2) At least one person with a physical address in Hong Kong will be designated as the representative of the company, organisation or individual operating the platform in Hong Kong; and
(3) The CAO can follow up with the company, organisation or individual operating the platform for information which is necessary to regulate the crowdfunding activities in Hong Kong.
Analysis and Takeaways
Newly emerging crowdfunding activities are picking up steam in the market but often remain as a lacuna within the current regulatory regime over fundraising activities. It is therefore appropriate to develop a regulatory regime to cover the online crowdfunding activities. Under the newly proposed regulatory regime by the FSTB, all fundraising activities that raise funds from the general public in Hong Kong are required to apply to and obtain prior approval from the CAO, whether they are based in Hong Kong or not, unless otherwise excluded. The CAO is suggested to publish guidelines as to the actual implementation of the one-stop crowdfunding approval, registration and administrative framework for the sake of market compliance.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
IConsultation Paper p. 10
IIConsultation Paper p. 2
IIIConsultation Paper p. 3
IVConsultation Paper p. 6
VConsultation Paper p. 3
VIConsultation Paper p. 8-9
VIIConsultation Paper p. 10
VIIIConsultation Paper p. 13
IXConsultation Paper p. 10
XConsultation Paper p. 12
XIConsultation Paper p. 16-17
XIIConsultation Paper p. 18
XIIIConsultation Paper p. 17
XIVConsultation Paper p. 11
XVConsultation Paper p. 11
XVIConsultation Paper p. 15
XVIIConsultation Paper p. 15
XVIIIConsultation Paper p. 15
XIXConsultation Paper p. 15
XXConsultation Paper p. 15
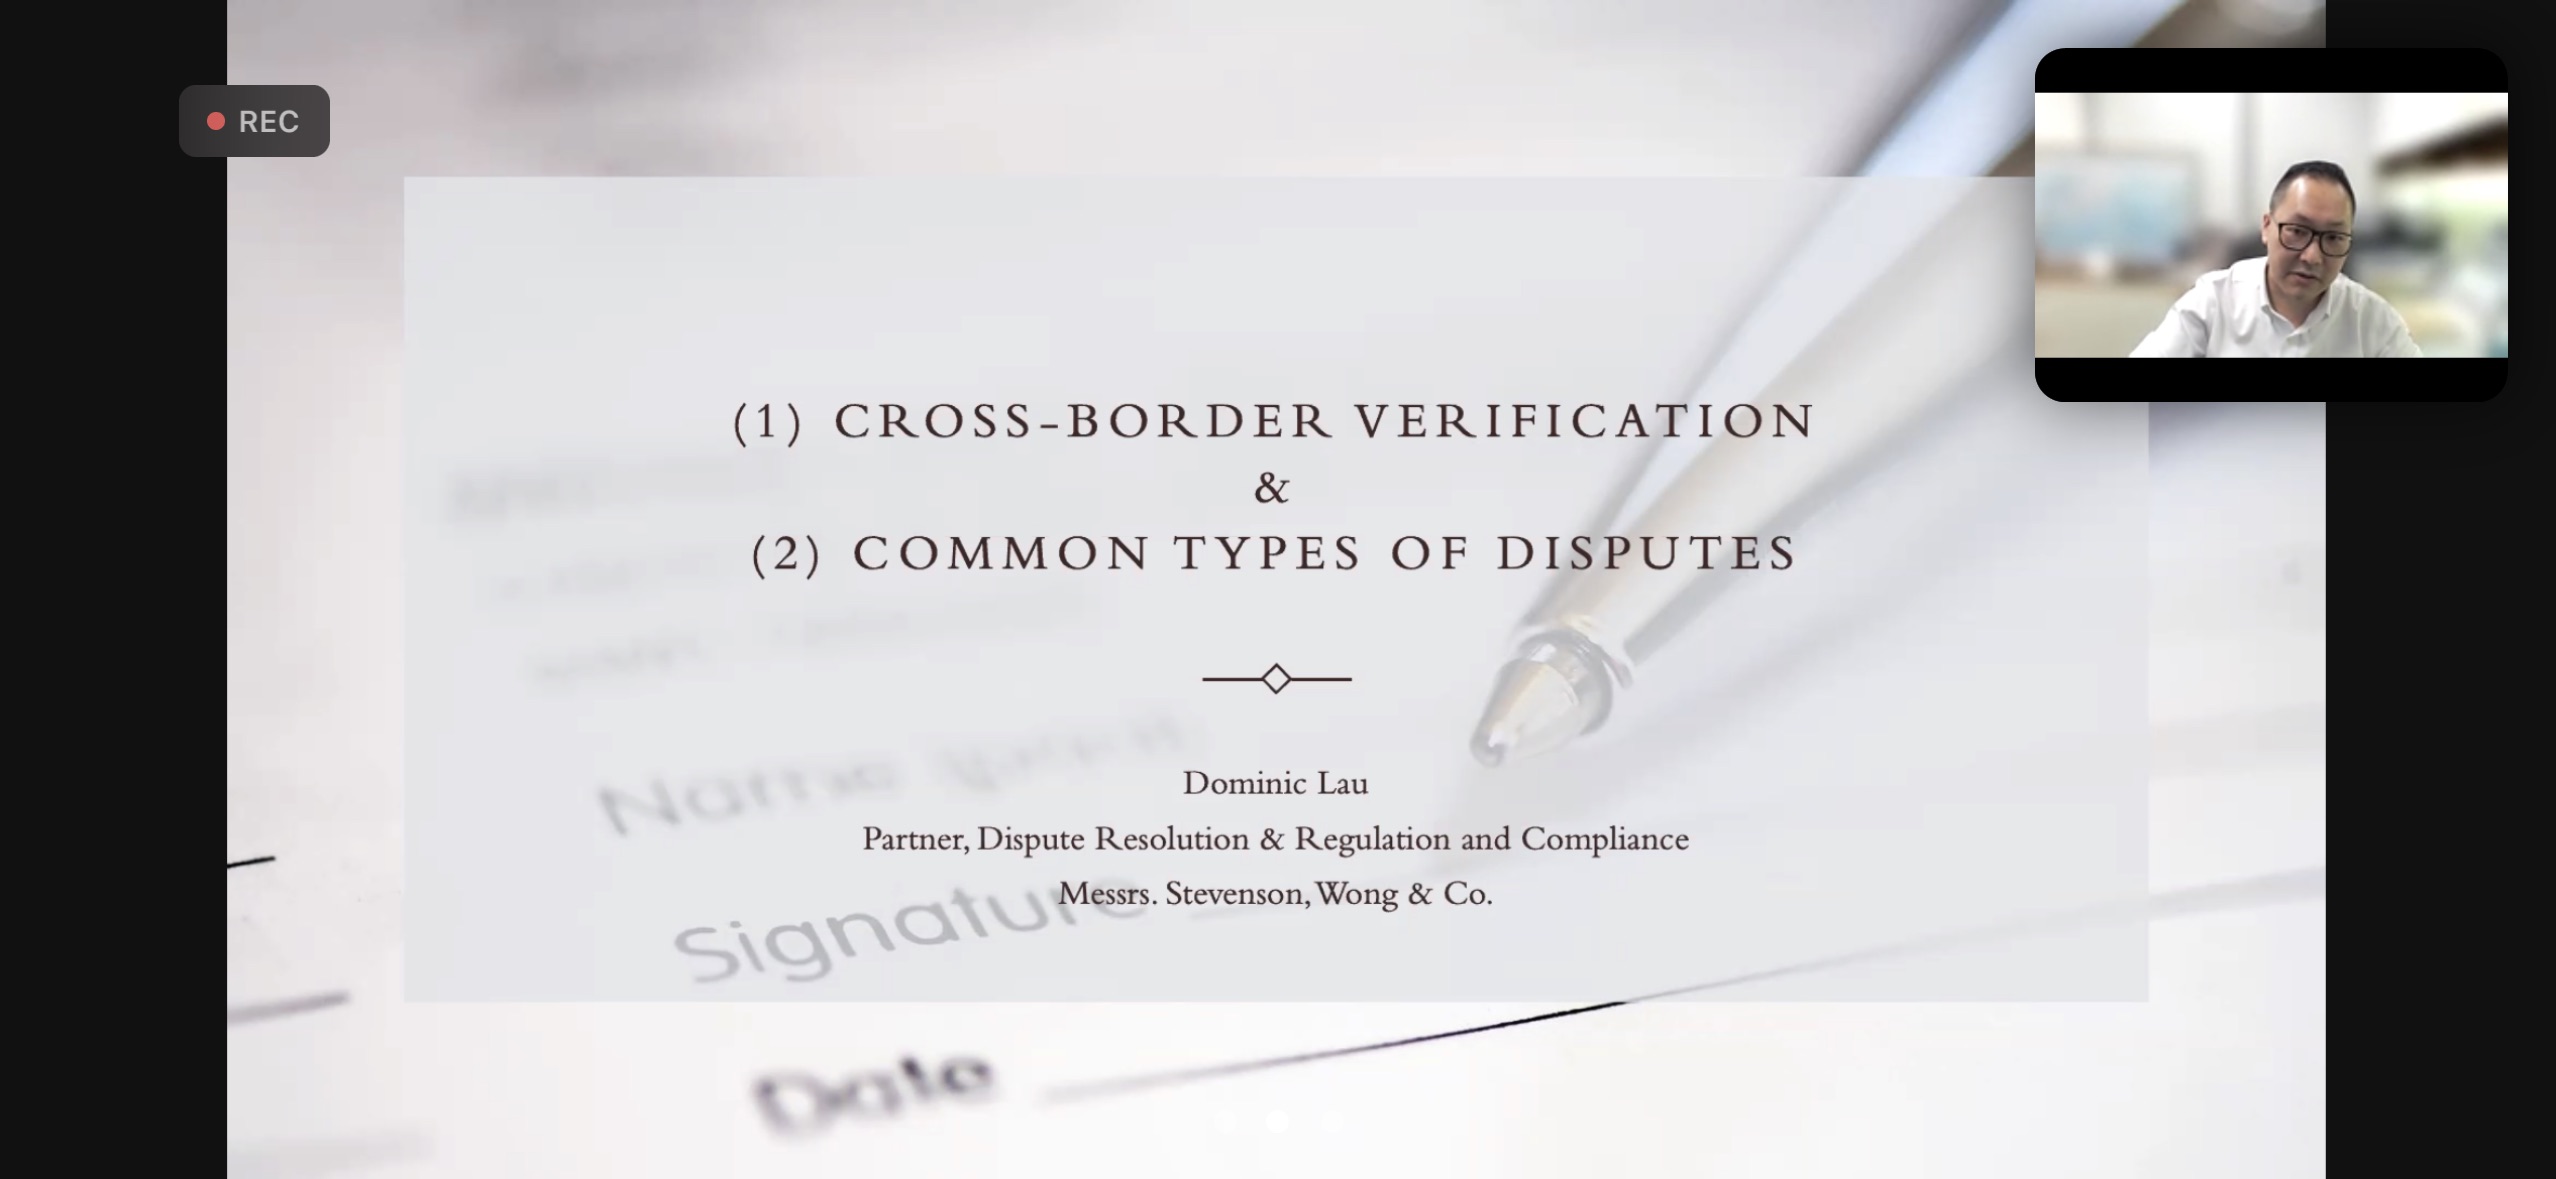
On 22 December 2022, our Partner Dominic Lau, was invited by Accounting Development Foundation to give a CPD course to its members on the topic of “Cross-Border Verification & Common Types of Disputes”.
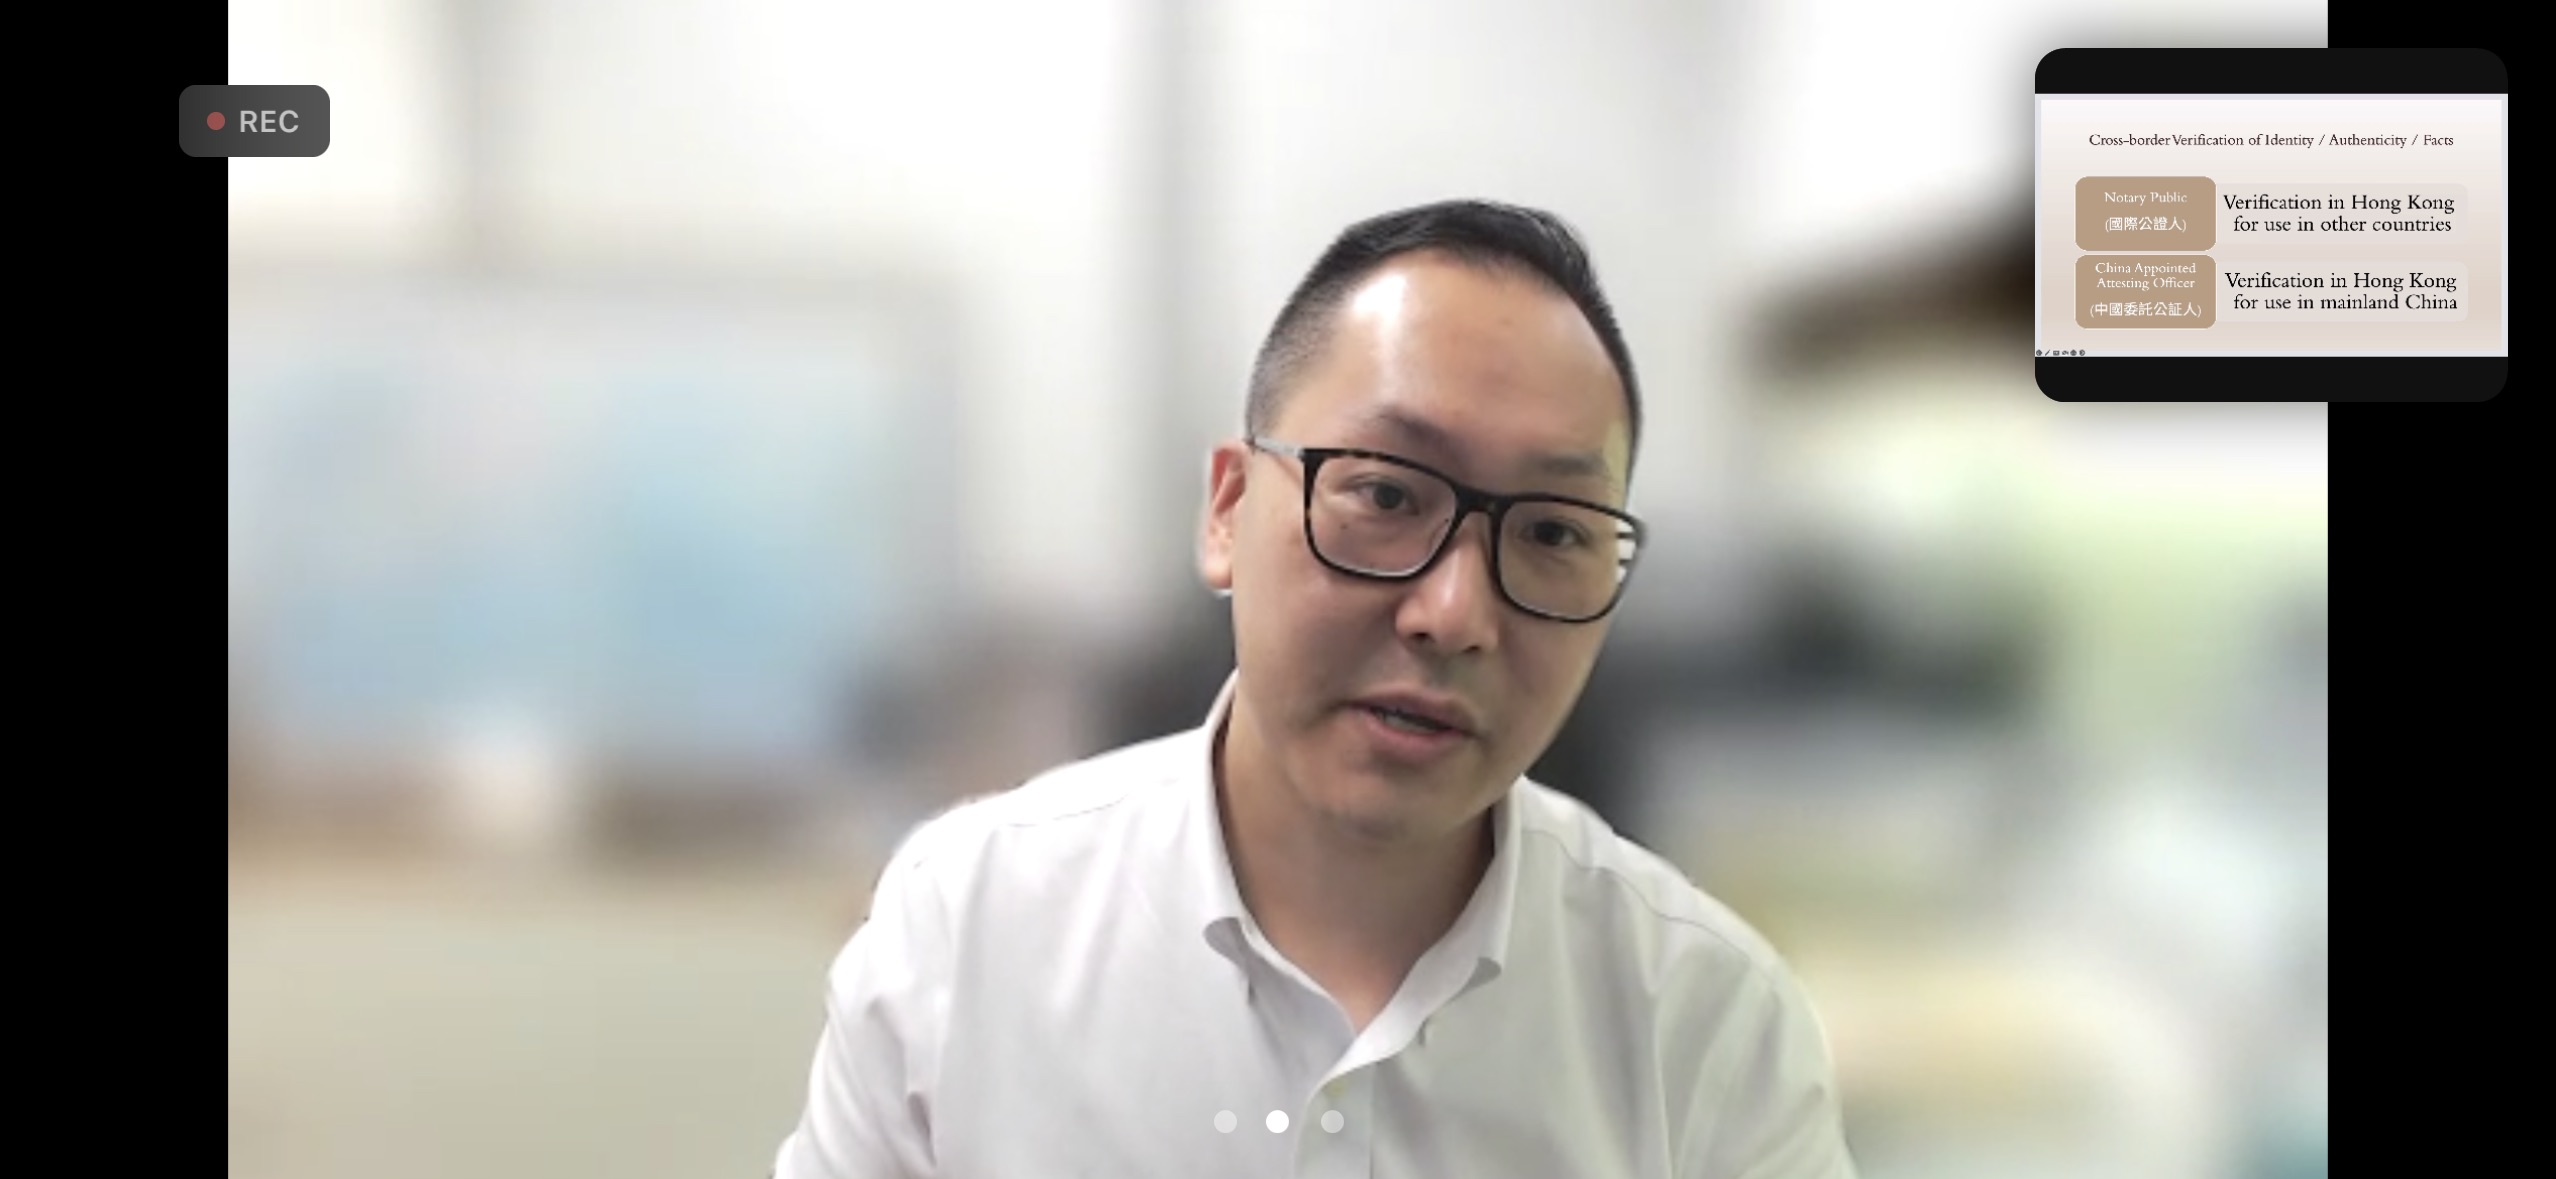
…
During the webinar, Dominic shared the key takeaway points for cross-border verification and the common types of disputes. He explained the different roles and duties of a Notary Public and China Attesting Officer, common notarial tasks, and examples of legalisation of documentation. He also discussed the common types of disputes involving breach of restrictive covenants, shareholder disputes and investment/ acquisition of business.

Please contact our Partner Dominic Lau for any enquiries or further information about this course.
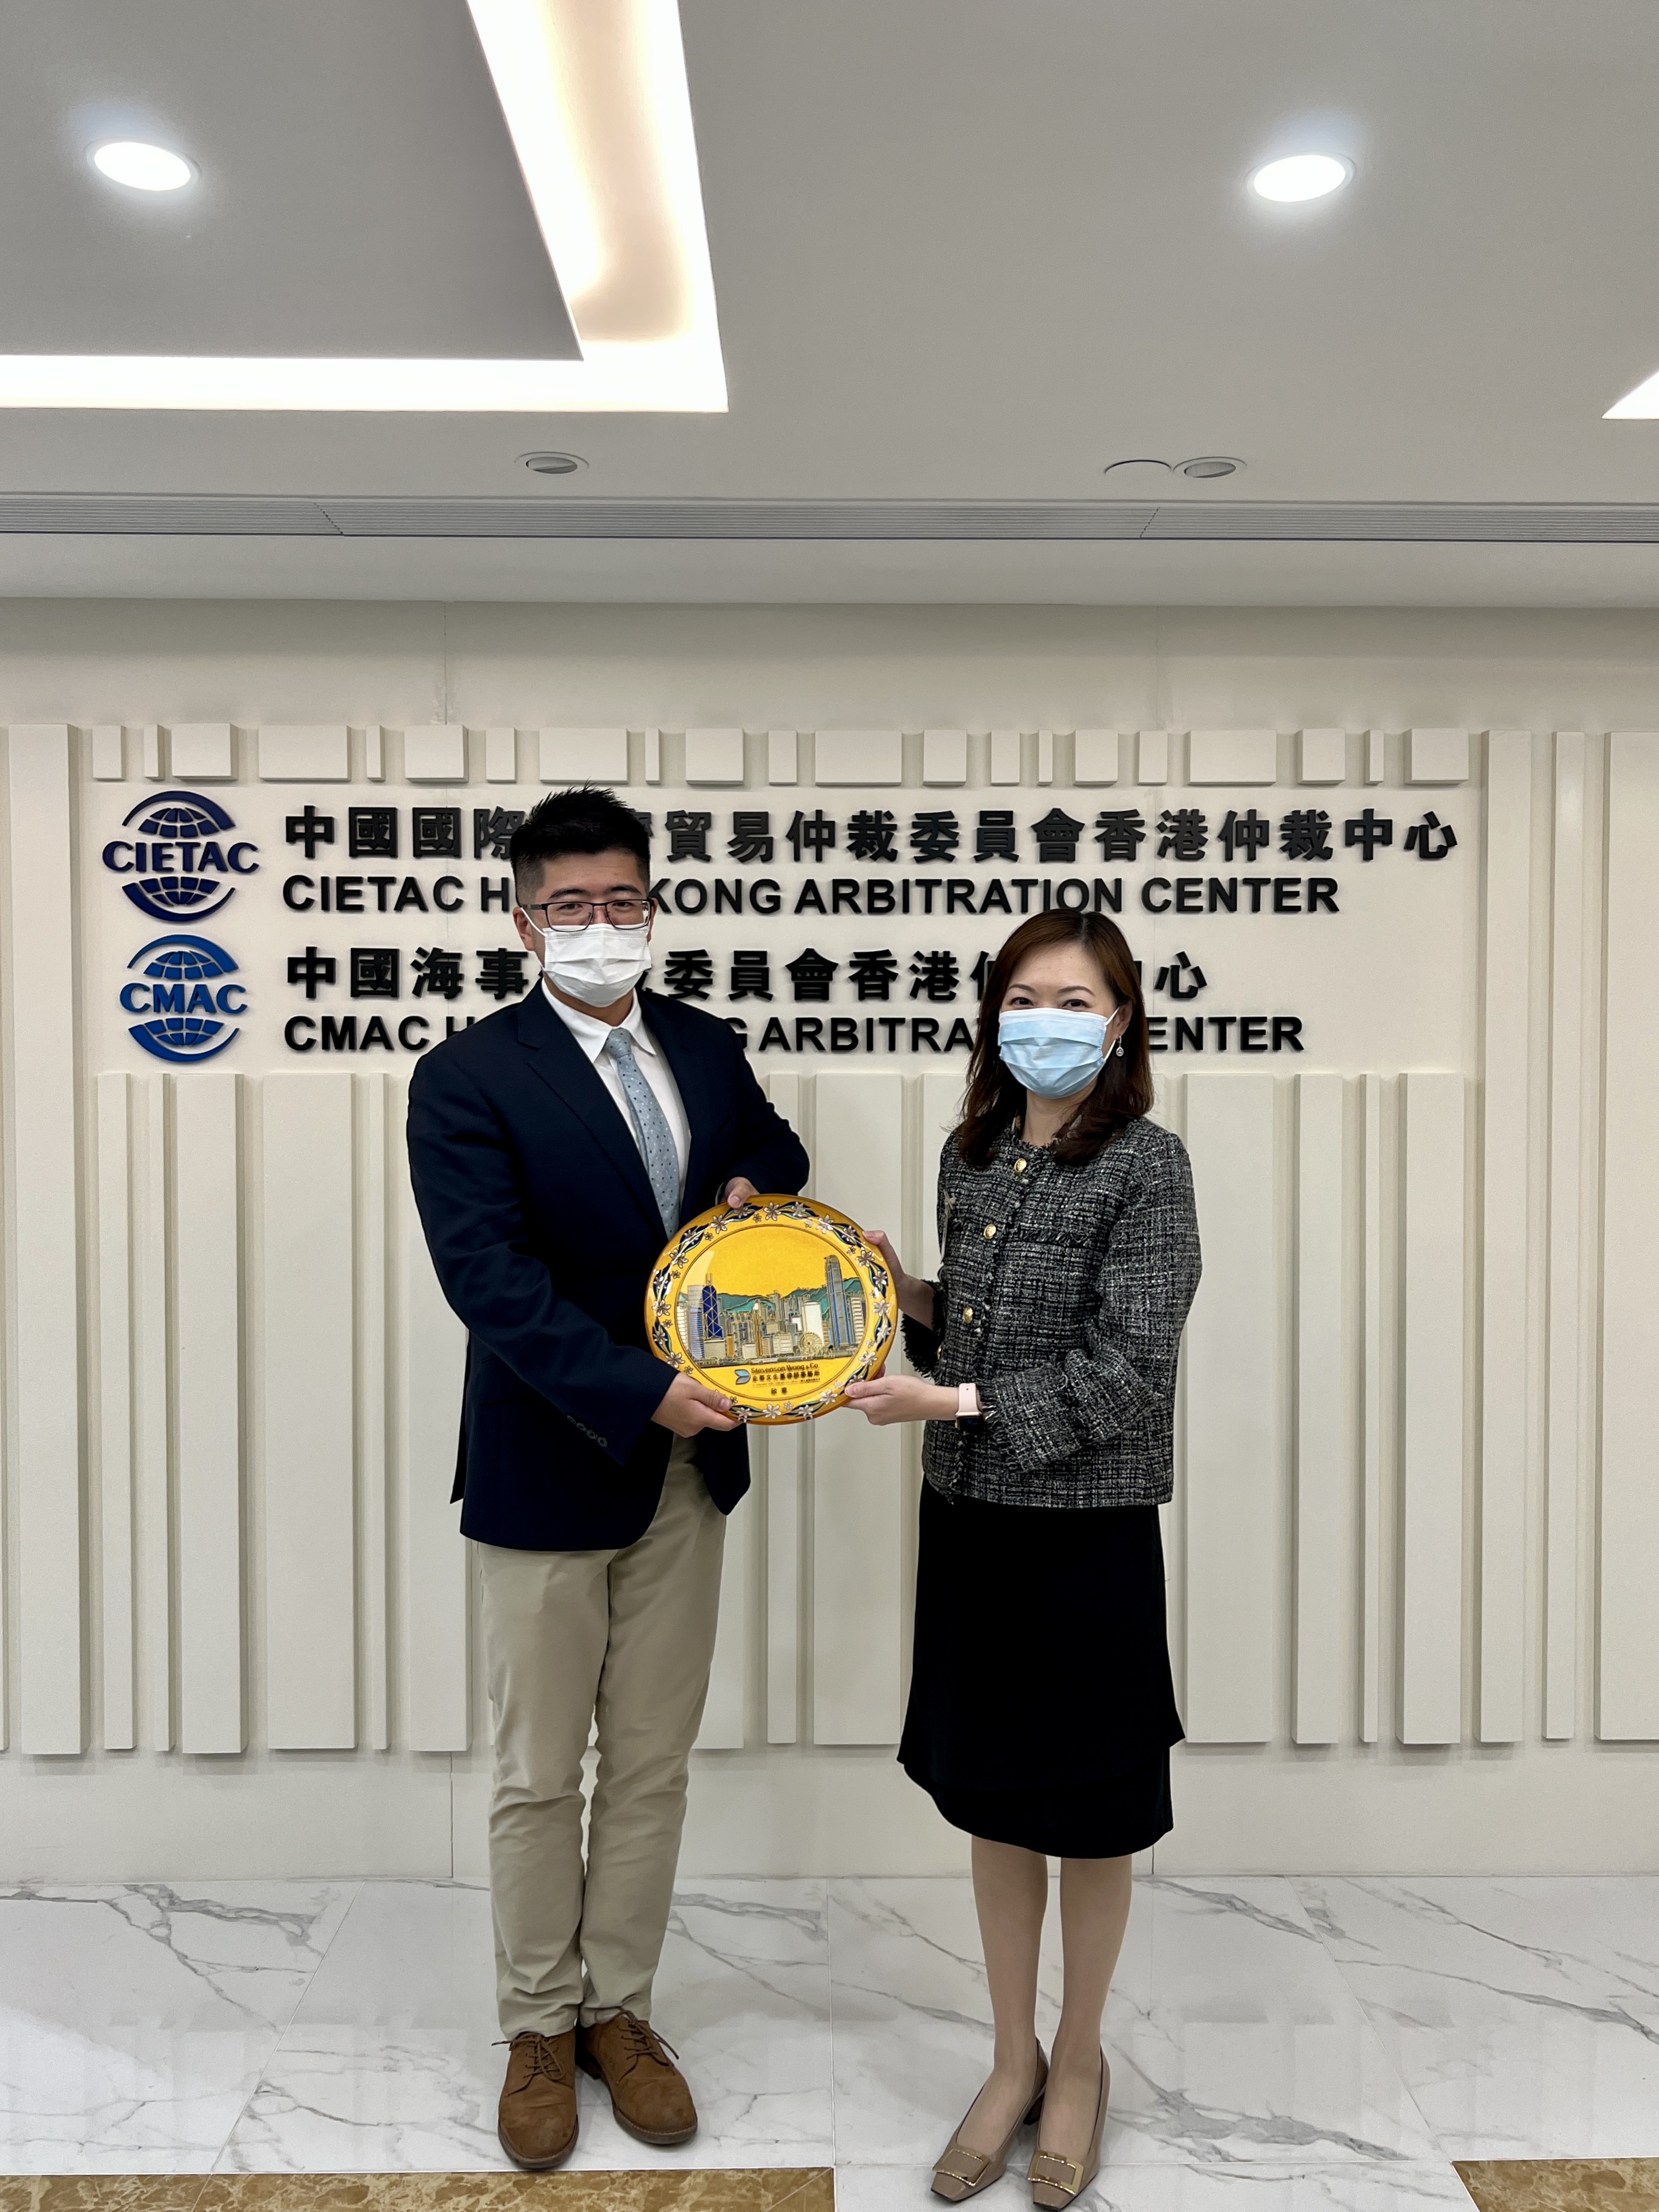
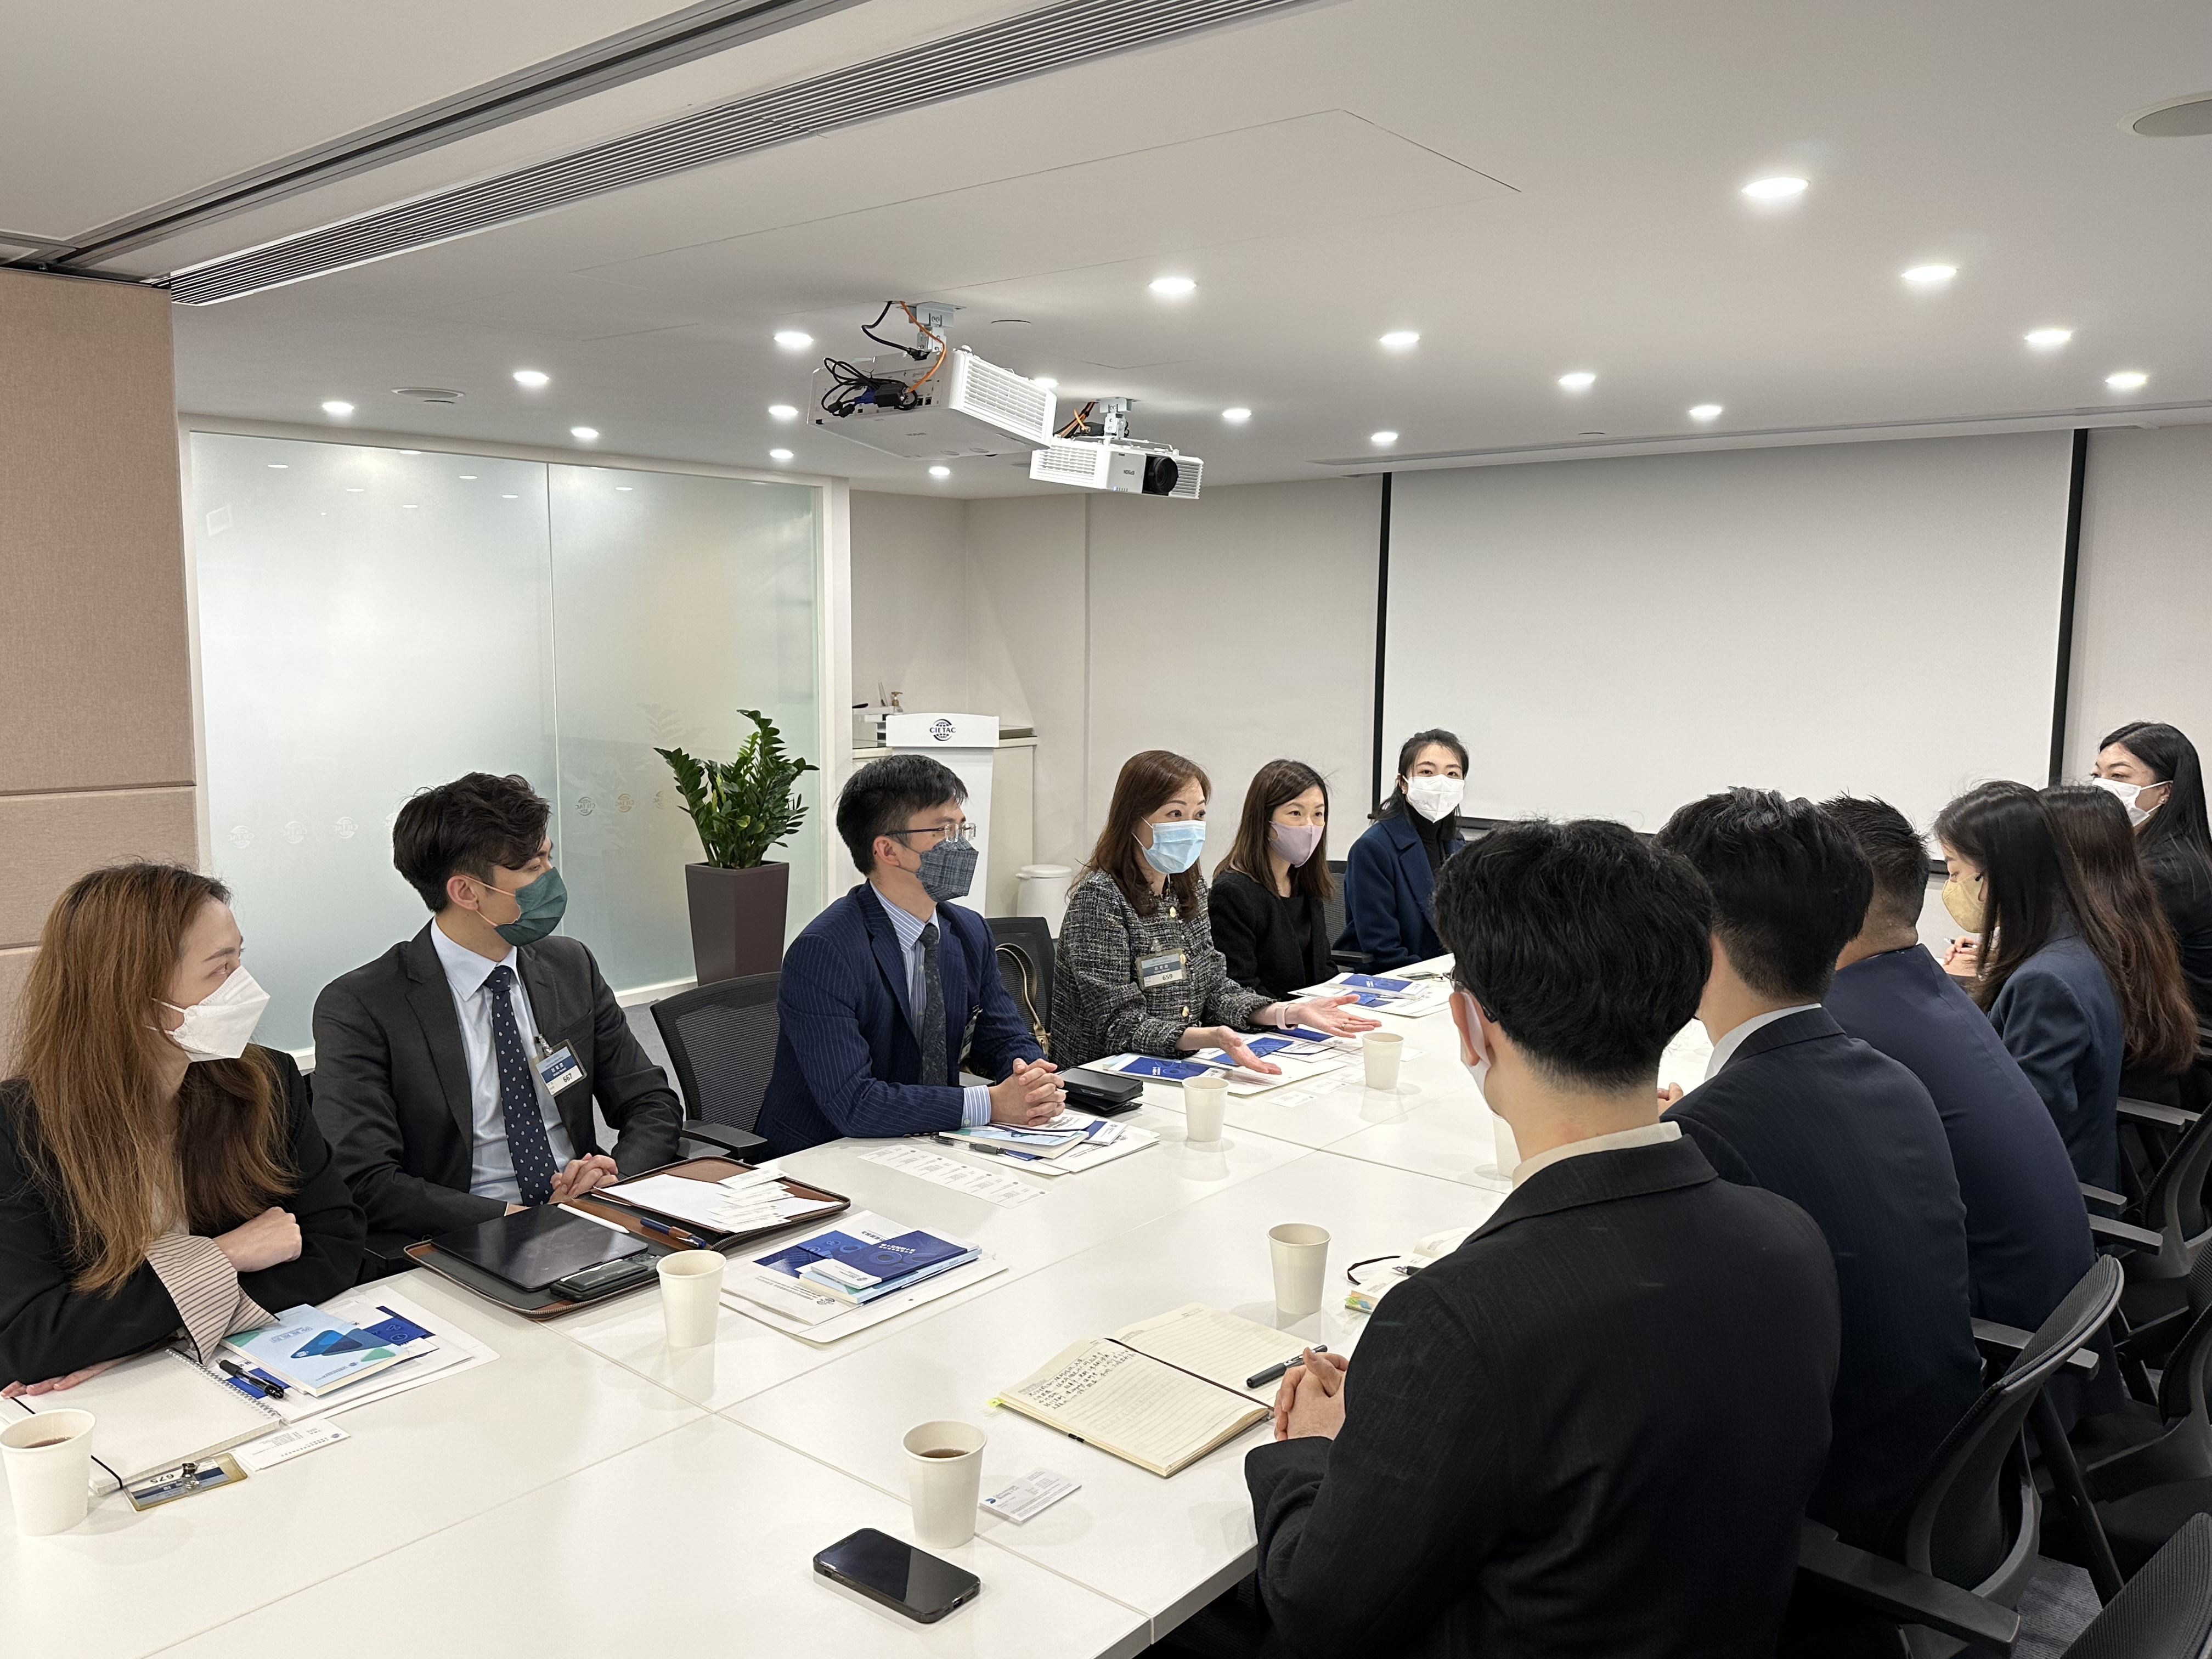
On 12 January 2023, our Partner and Head of our Litigation and Dispute Resolution Department, Ms. Heidi Chui and her team visited the China International Economic and Trade Arbitration Commission Hong Kong Arbitration Center (CIETAC Hong Kong Arbitration Center). CIETAC Hong Kong Arbitration Center’s Deputy Secretary General, Mr. Brad Wang, and other members warmly welcomed Ms. Chui and the team.
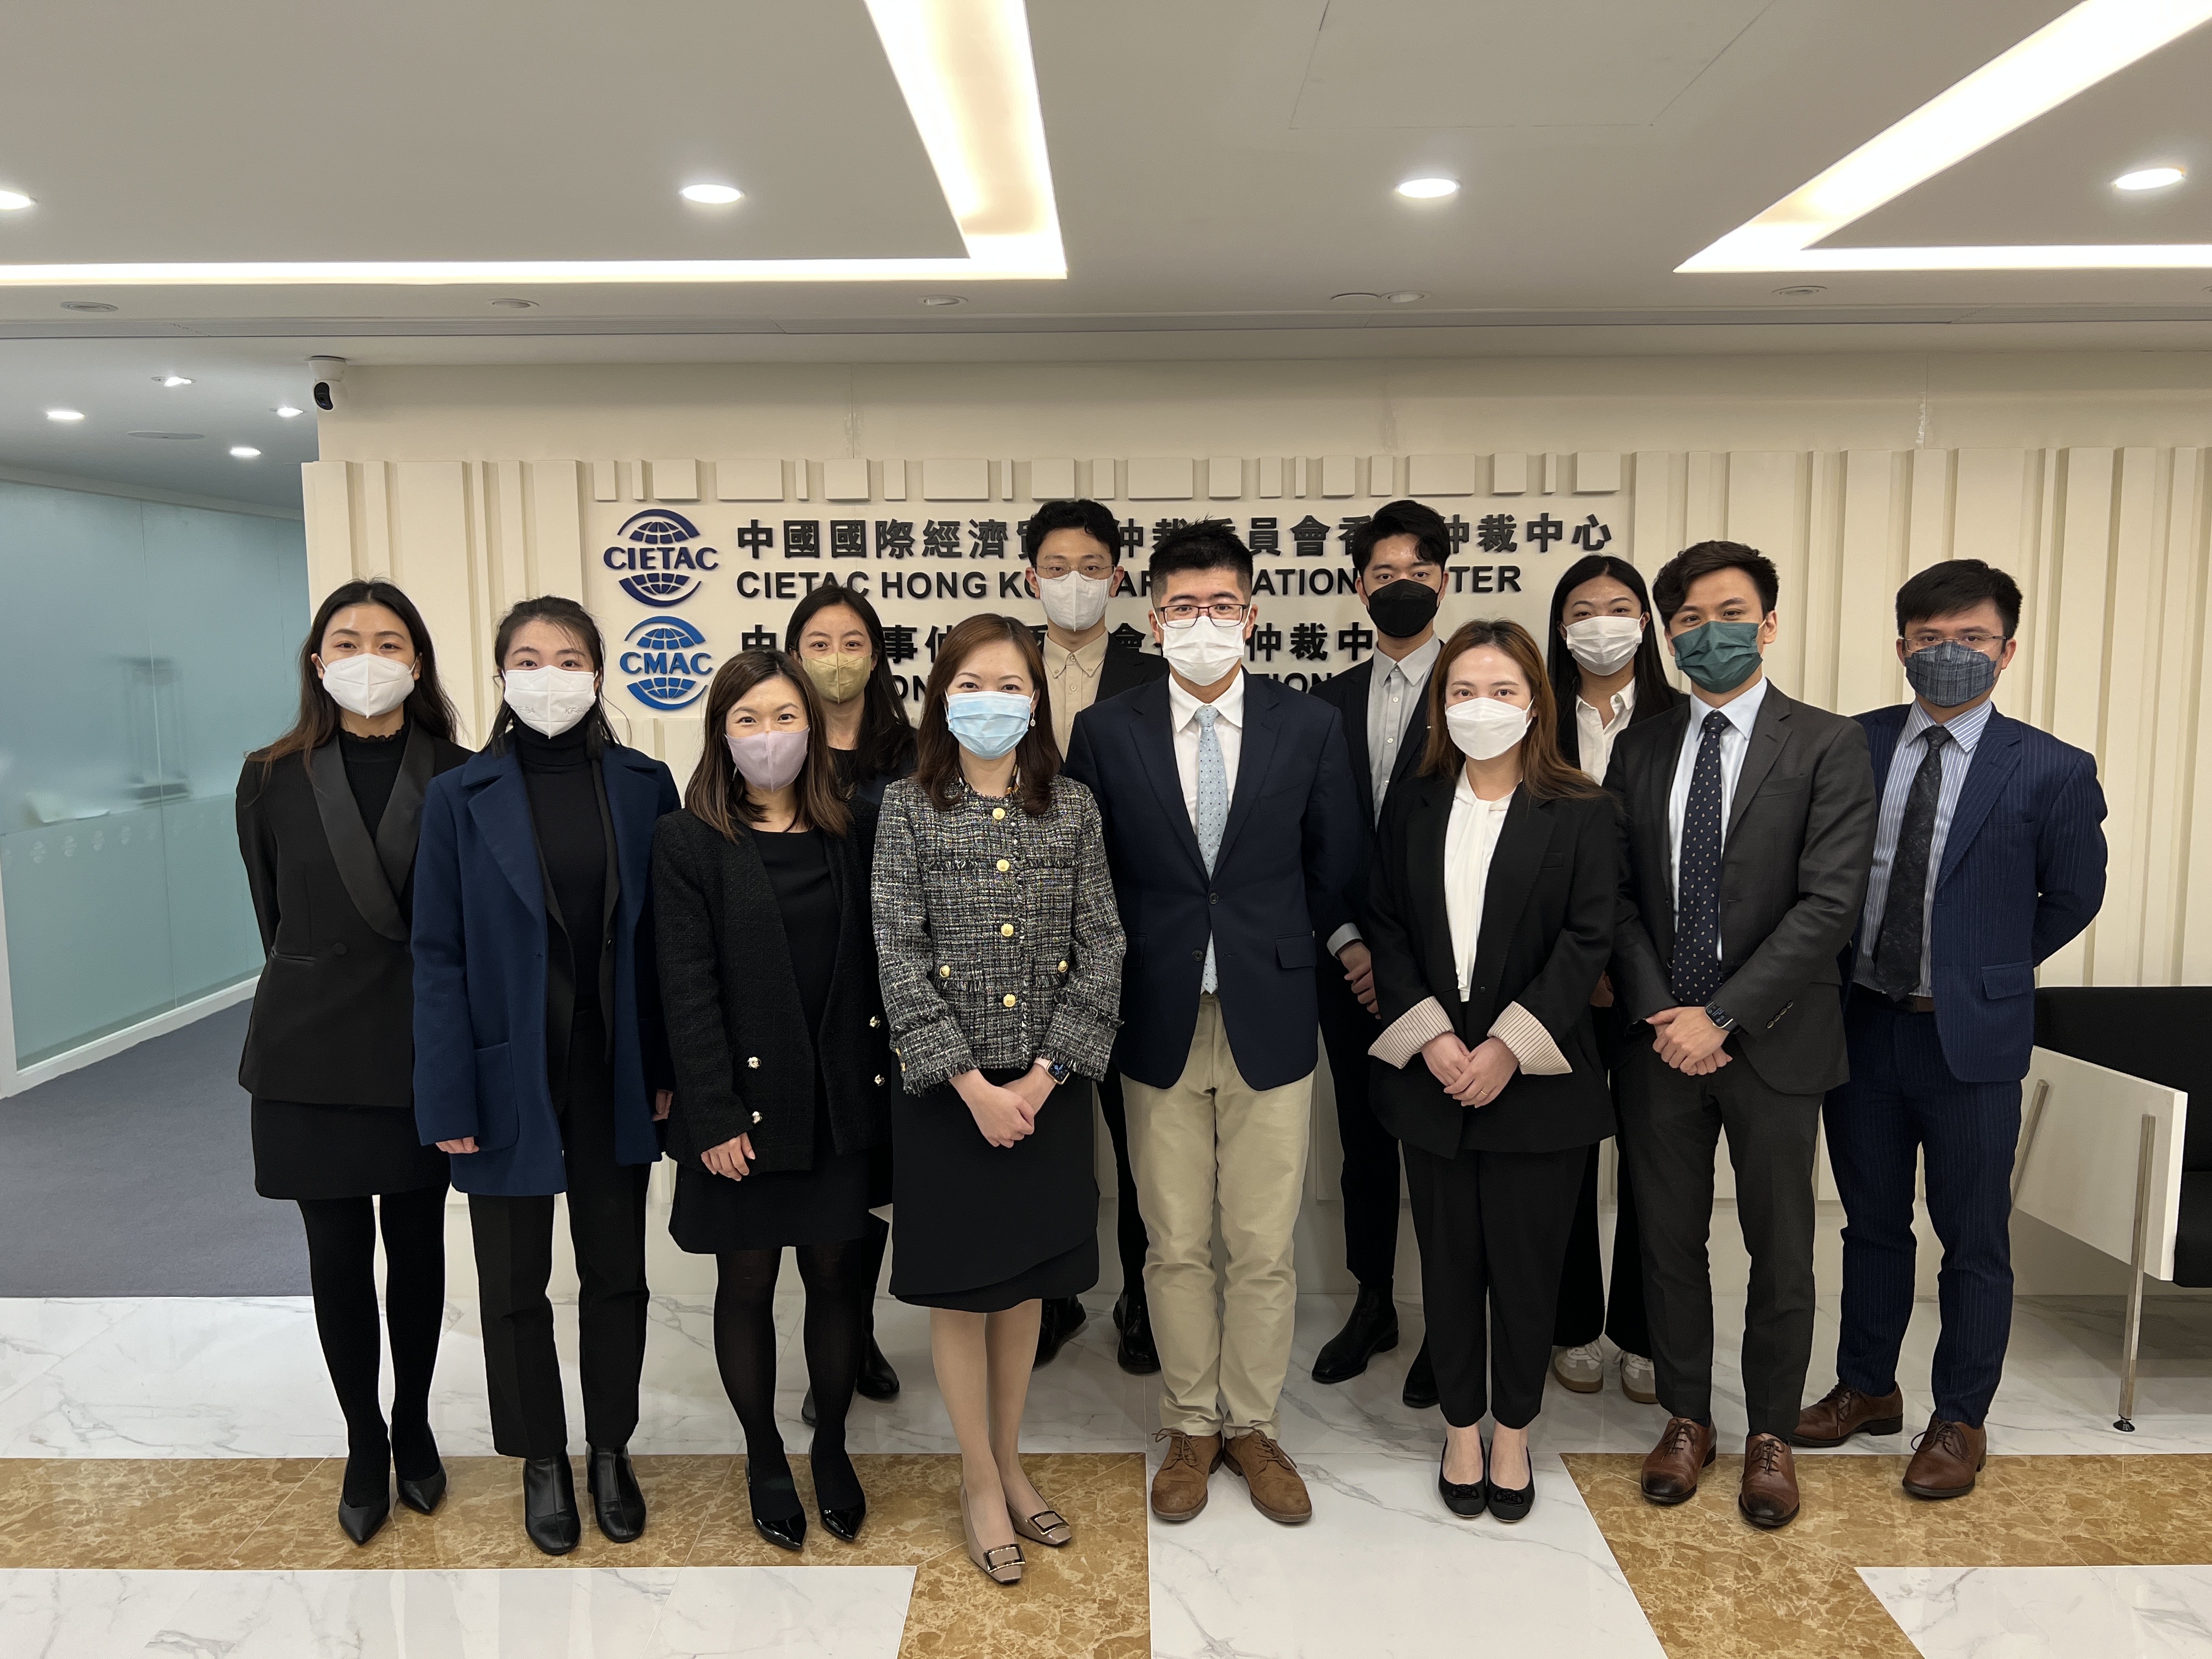
…
We would like to take this opportunity to thank CIETAC Hong Kong Arbitration Center for the kind invitation and hospitality. We look forward to future opportunities to connect and collaborate.
Please contact our Partner Ms. Heidi Chui for any inquiries.


Our Partner Hank Lo, Head of our firm’s Corporate Finance Department, and Partner Heidi Chui, Head of Banking and Finance and the Litigation and Dispute Resolution Departments, have been recognised on “The A-List China’s Elite Lawyers (Foreign Lawyers)” (The A-list) by China Business Law Journal (CBLJ) for their extensive experience and recognition by clients. The A-list acknowledges the top private practitioners excelling in the Chinese market.
…
Ms. Haiyan Gu, General Manager of Sina Group, recognised our Partner Ms. Chui as: “A key person capable of leading the process of dispute resolution. [Ms. Chui] has extensive experience and extraordinary legal skills in cross-border dispute resolution and international arbitration” she said. “[Her] services and opinions are very practical.”

*Photo from China Business Law Journal.
The A-List was selected by the editorial team of CBLJ after months of independent research over 10,000 nominations and feedbacks received from in-house counsel and corporate executives.

![]() |
Hank Lo|Partner Head of Corporate Finance |
| I am honoured to be recognised by CBLJ for 4 consecutive years. I wish to thank all our clients for their support and the hard work of our team. We will continue to expand and enhance our services in China’s growing legal market. | |
![]() |
Heidi Chui| Partner Head of Banking and Finance and Litigation and Dispute Resolution |
| It is an honour to be recognised by CBLJ’s again on “The A-List China’s Elite 100 Lawyers”. Thank you CBLJ for the recognition and our team members for their dedication, especially the long-term trust and support of our clients. I look forward to having closer collaborations with our clients in China’s legal market, particular in the Greater Bay Area, to provide innovative and pragmatic solutions. | |
For any inquiries, please contact our Partners, Hank Lo or Heidi Chui, or visit “The A-List” here .
The Top Talent Pass Scheme (“TTPS”) is a work visa aimed to attract top talents with rich work experience and good academic qualifications from all over the world to explore opportunities in Hong Kong. These top talents include high-income talents and graduates from the world’s top universities.
Following the announcement of the Chief Executive’s 2022 Policy Address, the Hong Kong Government has launched the TTPS on 28 December 2022 in response to the decline in the local workforce over the past few years.
The scheme is projected to run for a period of two years. Applicants admitted under the TTPS will normally be granted an initial stay of 24 months without other conditions of stay, provided that normal immigration requirements are met.
…
Eligible talents
Applicants may apply for the TTPS under one of the three categories listed below:
Interested candidates with relevant skills and talents should seize this good opportunity to seriously consider coming to Hong Kong to pursue their career dreams.
Our Immigration Team are on standby to help interested applicants understand the requirements and walk through the application process.
Please contact our Partner Willy Cheng or Associate Arial Ng for any further enquiries or information.
This newsletter is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
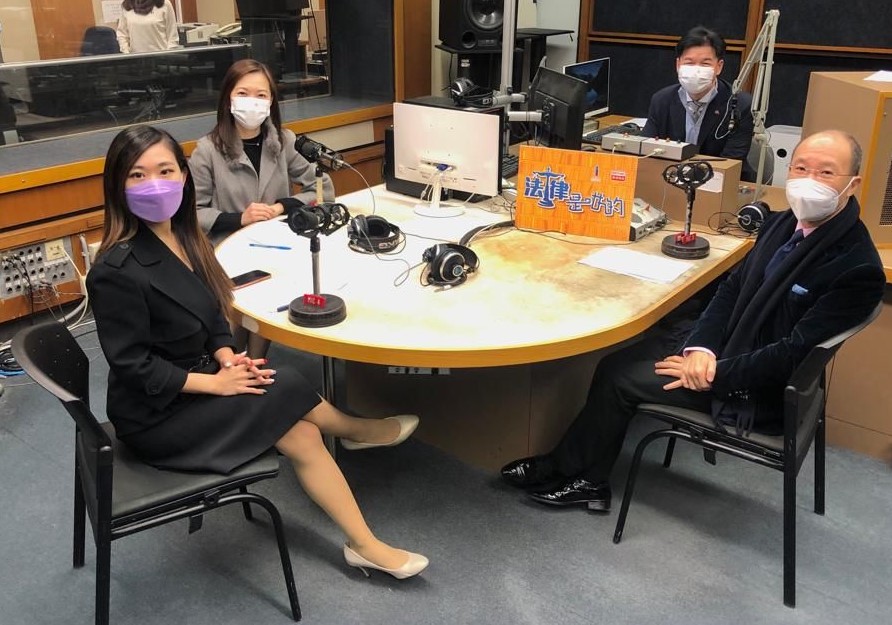
(中文) 2022年12月21日,本所合伙人﹑银行及金融部和诉讼及争议解决部主管徐凯怡律师,受邀为香港电台第一台节目《法律是咁的》担任受访嘉宾,探讨粤港澳大湾区与青年律师作为专业人士的机遇。《法律是咁的》由香港律师会与香港电台第一台共同合作推出,旨在向大众分享法律界之发展并探讨未来之机遇,暂定于2023年1月1日开始播放。
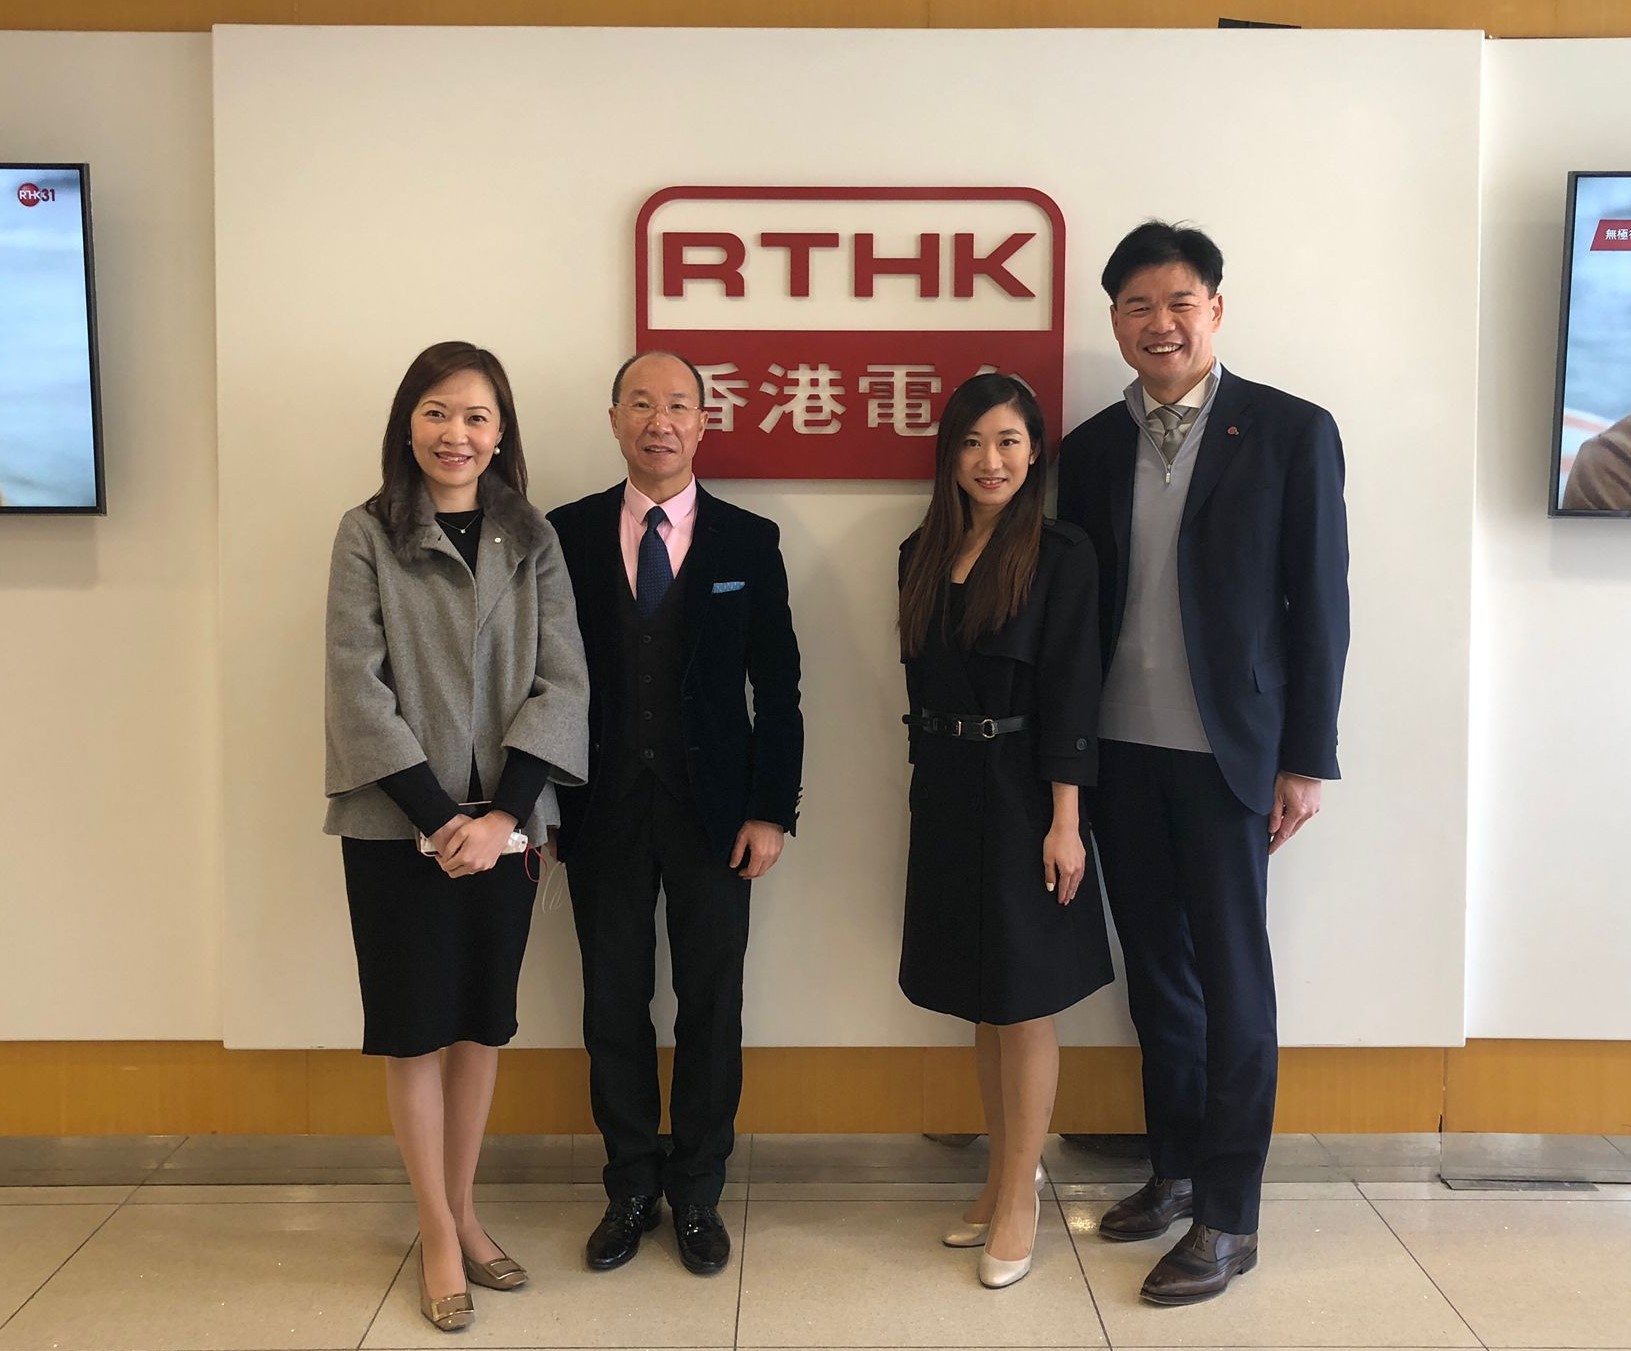
由左起: 本所合伙人徐凯怡律师﹑黄江天律师﹑谭雪欣律师和汤文龙律师
2019年2月,国务院发布了「粤港澳大湾区发展规划纲要」,支持建设香港为亚太区国际法律及争议解决服务中心,为法律服务等专业服务业界带来巨大机遇。徐律师作为香港律师会《两岸四地青年律师论坛》筹委会副主席,和首批通过「粤港澳大湾区律师执业考试」 (“大湾区考试“) 的香港律师,向听众分享了大湾区的发展前景和大湾区考试带来的机遇。累计执业五年的香港法律执业者,在通过大湾区考试和取得相关执业证书后,将可以在广州、深圳、珠海等大湾区内地九市办理适用内地法律的部分民商事法律事务(含诉讼业务和非诉讼业务)。
如阁下有任何查询或想了解更多详情,请联络本所合伙人徐凯怡律师。