News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
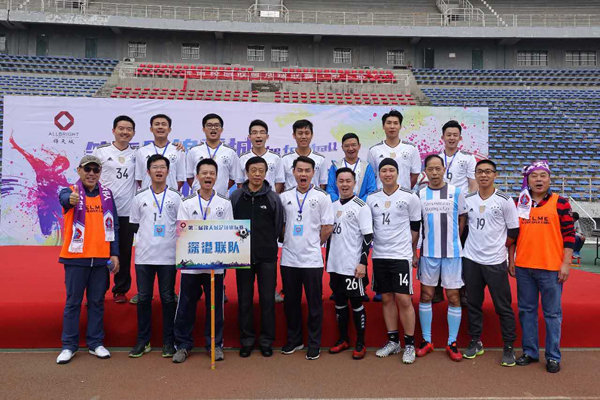
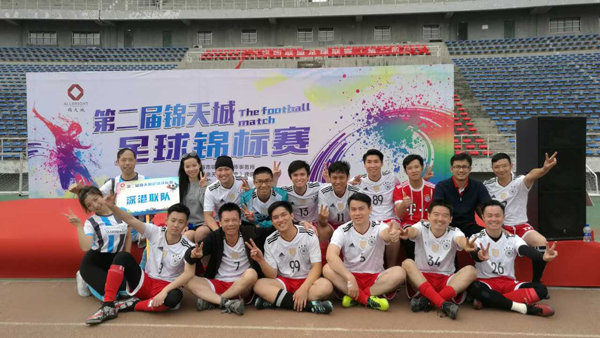
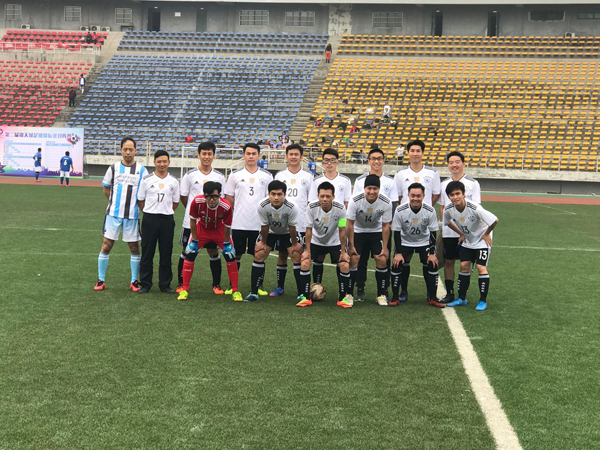
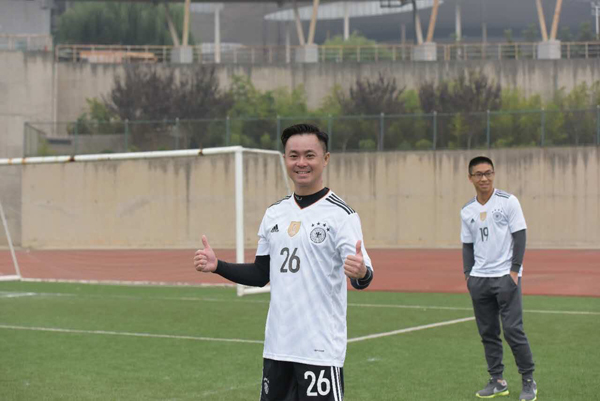
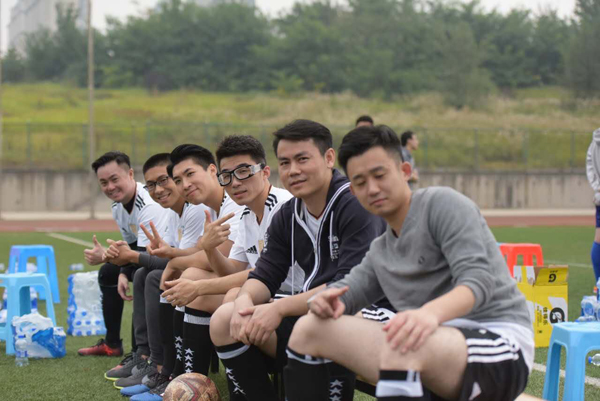
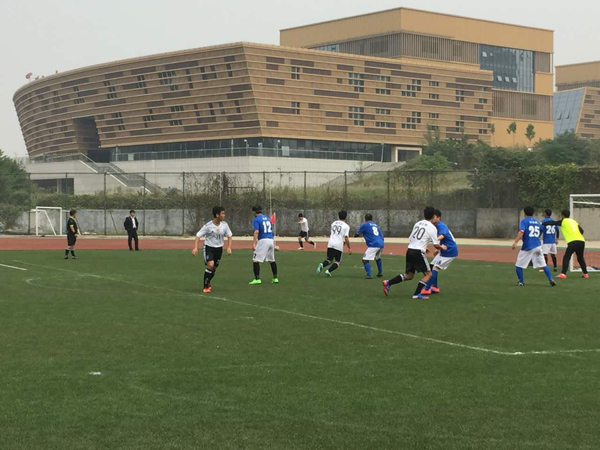
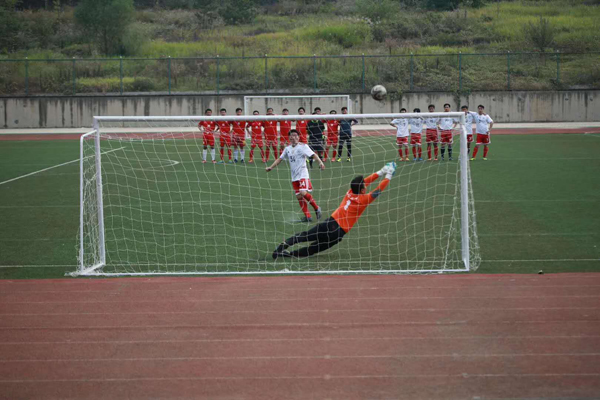
The Second AllBright Football Championship was successfully held in Jinan on 15 October 2017. It was first time for AllBright (Shenzhen) Office and Stevenson, Wong & Co. to be joint team participating in the competition. Shanghai team and our team had nip-and-tuck battle in the 3rd place. The match was finished by penalty shoot-out finally and the second runner-up was Shanghai team. The winner of the championship was Jinan team and the Qingdao team was first runner-up.
Please contact Mr. Stephen Wong for any enquiries or further information about this event.
The Ceremony for “The First Batch of National Lawyers in Hong Kong and Macau in Joint Venture Law Firms” to receive practising certificates was successfully held in China (Guangdong) Pilot Free Trade Zone Nansha Area of Guangzhou on 16th October 2017. More than 100 guests being lawyers from Hong Kong, Macau and Guangzhou, and corporate representatives from Nansha Free Trade Zone attended the ceremony. Director-General of the Department of Justice of Guangdong Province Mr. Zeng Xianglu presented practising certificates to a total of 42 lawyers, 33 from Hong Kong and 9 from Macau. Deputy Director of the Department of Justice of Guangdong Province Mr. Liang Zhen, President of Guangdong Lawyers Association Mr. Xiao Sheng Fang, Deputy Director of Justice Bureau of Guangzhou Municipality Mr. Tan Xian Ping and District Chief of Guangzhou Nansha People’s Government Mr. Ceng Jin Ze also attended the ceremony.
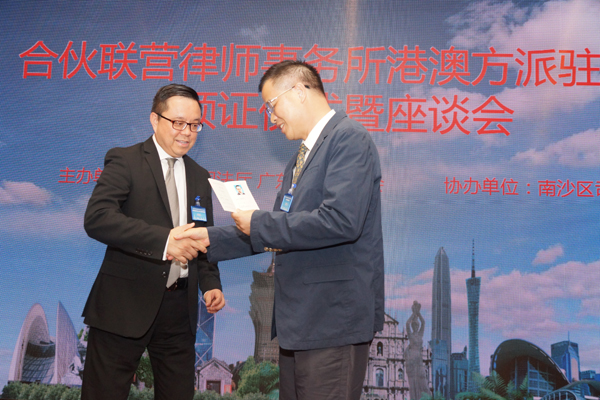
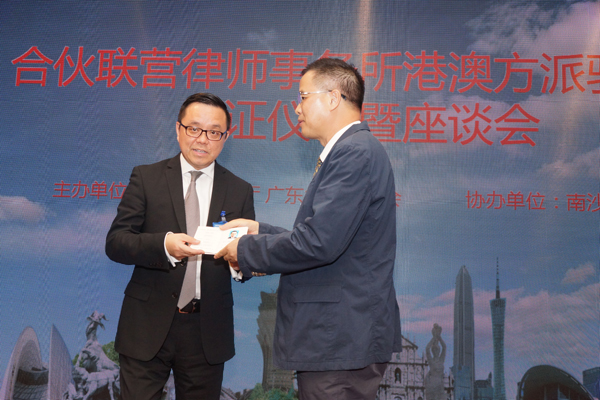
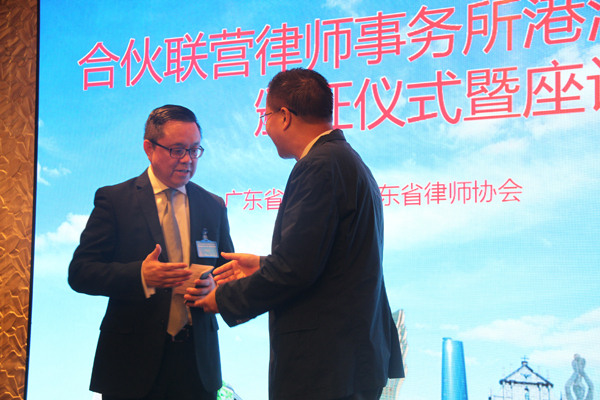
SW Partners Mr. Willy Cheng, Mr. Hank Lo and Mr. Eric Lui all received their practising certificates. “It is an honour for us to receive practising certificates and encourages Stevenson, Wong & Co. to promote our joint venture law firm.” The joint venture law firm set up by AllBright Law Offices and Stevenson, Wong & Co. in Qianhai (“ABL&SW”) opened its doors in January 2016. ABL&SW’s office is located in the heart of the Qianhai modern service industry cooperation zone and is one of the first batch of joint venture law firms to operate in Qianhai. ABL&SW are well positioned to give legal advice from both Hong Kong and PRC law.
Please contact Mr. Willy Cheng, Mr. Hank Lo, or Mr. Eric Lui for any enquiries or further information about this event.
On 13-14 October 2017, Stevenson, Wong & Co. Partner, Ms. Sherlynn Chan attended the symposium on Special Needs Financial Planning, organized by The University of Hong Kong Faculty of Law. The Symposium discussed three important topics relating to financial planning for people with special needs i.e. special needs trust, adult guardianship and the enduring power of attorney.
The symposium started with the opening remarks from the Commissioner of Rehabilitation from HKSAR Government, Mr. David Leung, JP. In the two-day symposium with more than 10 experts including Professors University of Canberra, Hanyang University, University of Hong Kong, Chuo University, University of Sydney and Singapore Management University, lawyers, managers and the former Senior Judge of the UK. Court of Protection – Mr Denzil Lush.
Please contact Ms. Sherlynn Chan for any enquiries or further information about this event.
(中文) 首届陆港两地仲裁实务研讨交流会于2017年10月13日在廊坊开发区新绎七修酒店完满举办。是次研讨交流会由廊坊仲裁委员会(简称廊仲)、其辖下的廊仲青年组织及史蒂文生黄律师事务所主办,并得到金诚同达律师事务所、协力律师事务所、四川东方大地律师事务所、北京市环中律师事务所、锦天城律师事务所、河北张克锋律师事务所、河北律绎律师事务所、河北听韬律师事务所、河北乾翔律师事务所、河北若石律师事务所和河北红杉律师事务所鼎力支持。
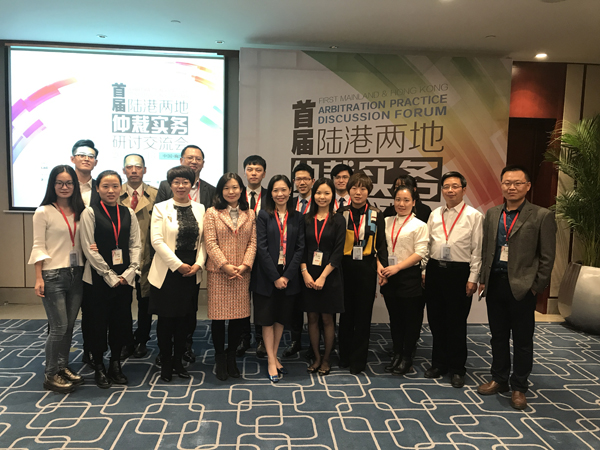
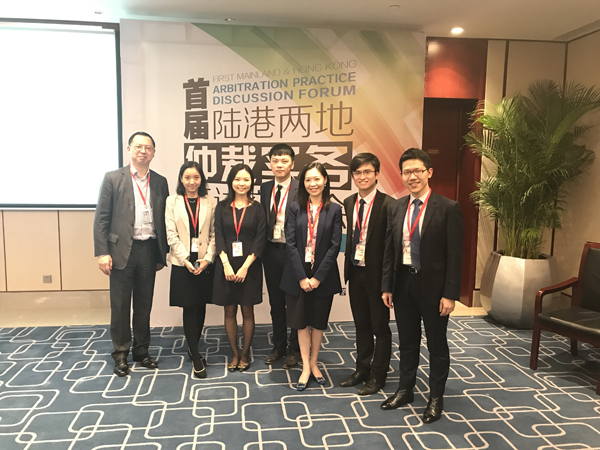
由左至右:吕志豪律师、马子蕙律师、莫薏筠律师、黄晊晄实习律师、徐凯怡律师、卢家俊律师及张俊燊律师助理
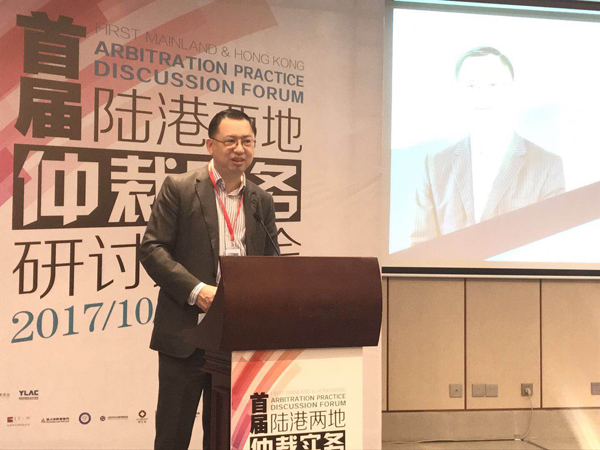
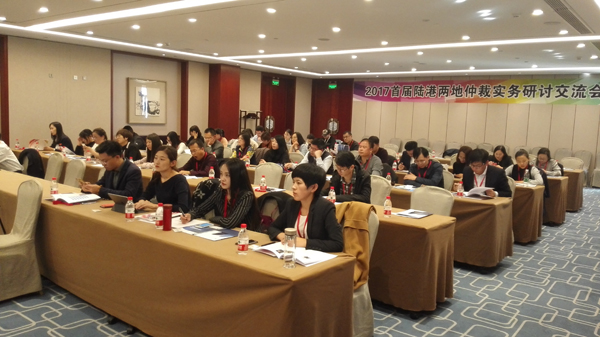
是次研讨交流会吸引近80名人士出席。活动由廊仲副主任兼秘书长程文女士致欢迎辞揭开序幕。本所合伙人吕志豪律师获邀出席,并为活动致辞。吕律师表示很高兴来到廊坊,自上次廊仲拜访本所后,一直期待大家再次会面,这次实在是一个难得的机会,并能与廊仲共同举办两地仲裁实务研讨交流会。吕律师期望在未来能与廊仲有更多合作,为促进陆港两地仲裁事宜努力。
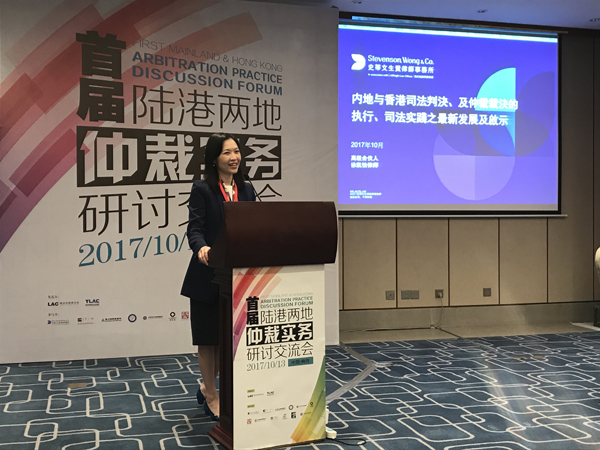
本所另一合伙人、诉讼及争议解决部门的主管律师徐凯怡律师获邀出席,并发表了关于「内地与香港司法判决、及仲裁裁决的执行、司法实践之最新发展及启示」的主题演讲。徐律师和与参加人士分享了中港跨境诉讼的实战攻略,激发了听众对于跨境诉讼的兴趣。徐律师的实战攻略以中港平行诉讼和香港资产冻结的司法实践为基础,充分分析跨境诉讼、仲裁的优势及风险,分享了可行的解决方案。充实鲜活的案例展示更是促进了台上台下的积极交流,活跃了整个研讨交流会的气氛。
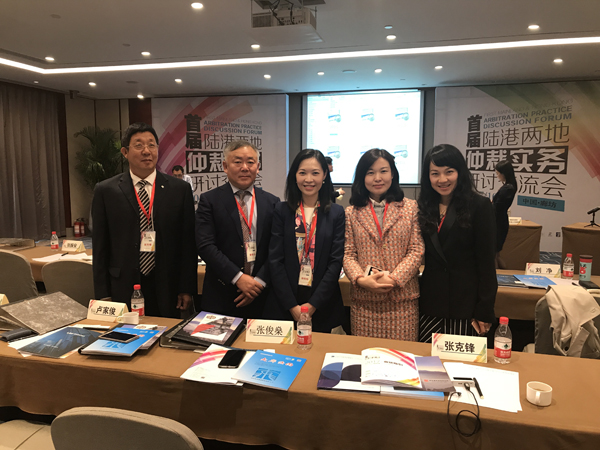
由左至右:张克锋主任、董绪公主任、徐凯怡律师、程文秘书长、刘凈律师
除了徐律师的分享外,莅临本次活动的嘉宾亦与在场人士互相交流,分享也是精彩纷呈,当中包括锦天城(北京)律师事务所合伙人彭立松先生、北京市环中律师事务所资深合伙人刘凈女士、四川东方大地律师事务所主任、高级律师董绪公先生、上海市协力律师事务所高级合伙人张振安先生、以及金诚同达(上海)律师事务所主任、高级合伙人赵平先生。
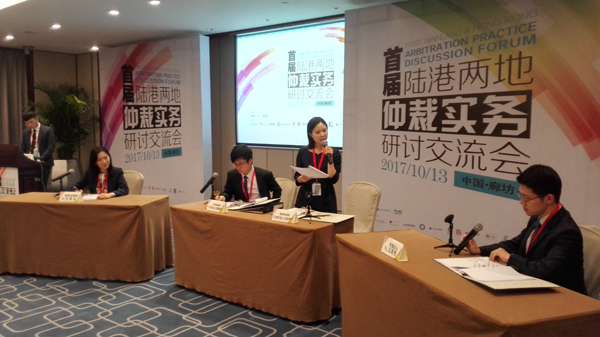
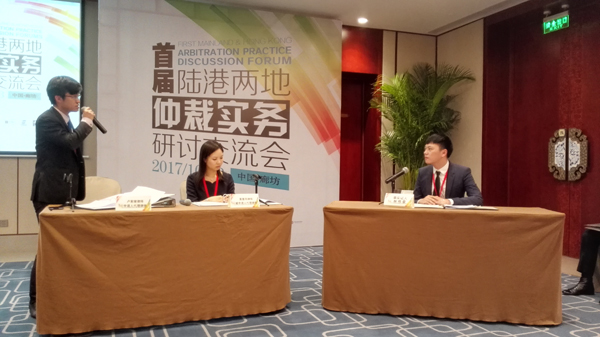
徐律师与团队包括卢家俊律师、莫薏筠律师、张俊燊律师助理及黄晊晄实习律师经过精心准备和排练,现场为与会的嘉宾和观众生动演绎了一场精彩纷呈又专业的模拟香港仲裁,展示了争议双方如何通过按香港国际仲裁中心仲裁规则进行的仲裁解决纷争。模拟仲裁主要展示证人接受盘问这一特色主题。香港普通法体系下的盘问会给对方机会进行发问,以尝试推翻或质疑证人的证供。几位律师在台上展现了出庭律师雄辩滔滔的风采,唇枪舌剑的交锋让台下观众看得津津有味,完全沉浸在仲裁的氛围当中。活动完结后,参加人士纷纷表示模拟仲裁非常精彩,令他们别开生面,更确切感受到香港的仲裁模式。
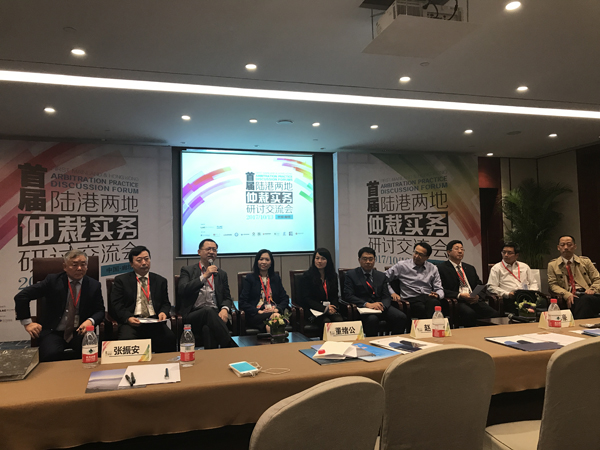
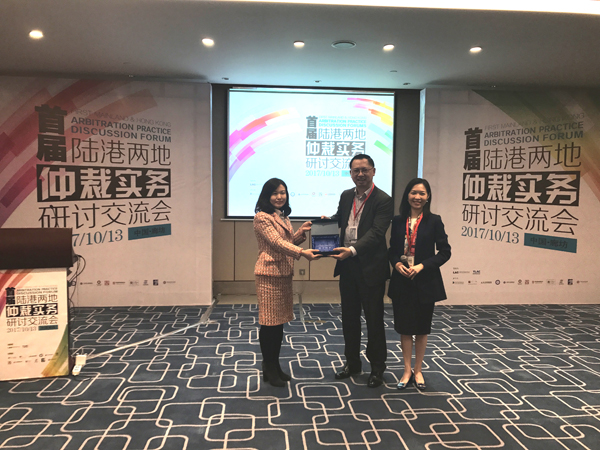
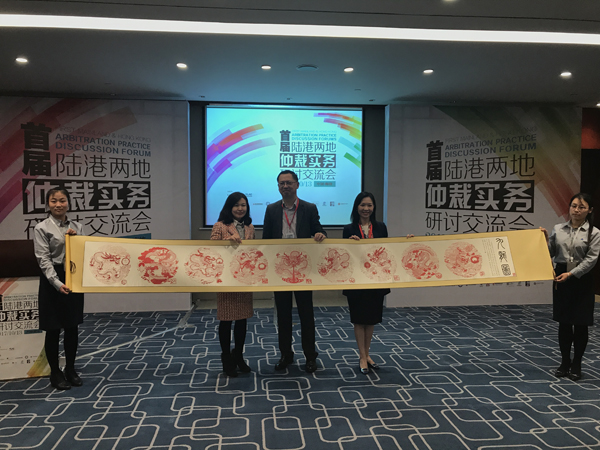
在座谈交流环节中,嘉宾们逐一分享对是次活动的感想,亦感谢本所诉讼团队带来精彩的仲裁表演。在场人士纷纷把握机会向嘉宾们问及有关陆港两地的仲裁事宜,互相交流。及后,吕律师及徐律师代表史蒂文生黄給廊仲赠送刻有维多利亚港景色的水晶摆设,摆设刻上「同心协力」,寓意本所与廊仲将团结一致,共同努力做好仲裁事务。廊仲秘书长程文女士亦向本所赠送一幅「九龙图」。
First Time Recognition by a PRC Court of Enforcement of a U.S. Commercial Judgment
Recently, the Wuhan Intermediate People’s Court (“Wuhan Court”) recognized and enforced a commercial judgment awarding damages entered by the Los Angeles County Superior Court, California, USA (“CA Court”).
Case Background
Wuhan Court Verdict: (2015) 鄂武汉中民商外初字第00026号
(http://wenshu.court.gov.cn/content/content?DocID=498d1508-6e7a-4f61-9a54-a7b6012dafaa&online: KeyWord=2015)
The applicant and the respondents agreed that the respondents would transfer to the applicant a 50% equity interest held in an American corporation for USD 125,000. After the consideration was paid, the respondents absconded with the money and the applicant sued the respondents in the CA Court. CA Court sided with the applicant and ordered the respondents to refund the sum of USD 125,000 with interest. As the respondents were domiciled and had assets available for enforcement in Wuhan, the applicant filed the case in Wuhan Court.
Held:
Procedural
A certified copy of the U.S. judgment and its Chinese translation were submitted by the applicant.
Substantive
Under Article 282 of Civil Procedural Law of the People’s Republic of China, PRC courts shall rule on recognition and enforcement if the PRC court “concludes, upon examination and pursuant to an international treaty which includes the People’s Republic of China or in accordance with the principle of reciprocity, that the basic principle of the laws of the People’s Republic of China or the sovereignty, security or public interest of the State is not violated”,
Pursuant to Article 282, Wuhan Court issued the decision on the following grounds:
1. China and USA have not reached any international treaty relating to the recognition and enforcement of court judgments.
2. There is a precedent of U.S courts recognizing and enforcing civil judgments rendered by PRC courts. Therefore, Wuhan Court held that there is a reciprocal relationship between China and the U.S in respect of mutual recognition and enforcement.
3. The CA Court’s judgment intended to resolve a dispute arising out of an equity transfer agreement between individuals. As a result, such judgment is not in violation of PRC principles.
However, there is no clearly established definition under PRC law regarding reciprocity. Therefore, PRC courts have discretion, albeit limited, to determine what constitutes reciprocity and whether there is a reciprocal relationship in a case. Unlike courts under the common law legal system, a judgment made by local courts is not binding on lower courts in China.
The U.S court judgment acted as a precedent in this case which was not based on the reciprocity principle, but on the Uniform Foreign Money Judgments Recognition Act. The lesson is that it is still worth spending time and effort to review a dispute resolution clause very closely.
Introduction
Amid the high level of interest relating to the Belt and Road (一带一路) Initiative of the Chinese Central Government, the Securities and Future Commission (“SFC”) delivered a statement in April 2017 regarding its approach to listings of certain infrastructure project companies on The Stock Exchange of Hong Kong Limited (“SEHK”). Infrastructure project companies are generally recognised by the SFC as having special risks attached to them, and are accorded greater levels of scrutiny during the listing application process to ensure that the infrastructure project companies are suitable for listing on the SEHK. The recent statement from the SFC aims to provide a measure of clarity regarding its view of such listings and to enhance the attractiveness of Hong Kong’s capital market by permitting more listings of infrastructure project companies, in particular those falling within the Belt and Road Initiative.
Statement of the SFC
The SFC has set out a list of mitigating factors which, if one or more are present, will improve the risk profile of an infrastructure project company and reduce the likelihood of the SFC in exercising its discretionary power to reject the proposed listing:
1. large shareholding by a relevant PRC SOE, sovereign wealth fund, substantial listed company or substantial and globally-active institutional investor;
2. committed project financing from a sizeable PRC, Development or International bank;
3. overnment where the project assets are located has direct involvement or shareholding; and
4. the project is located in a jurisdiction that is a signatory to the IOSCO MMOU, or where the SFC has sufficient comfort that it can obtain relevant public and non-public information about the activities of the company in the jurisdictions in which it operates.
This list of factors is not exclusive and other attributes may be proposed in substitution. It is also likely that not all of these attributes will be applicable in any one case.
SEHK Listing Rules and Waiver Conditions
On the other hand, under the current SEHK Listing Rules, a Main Board listing applicant normally must (i) have a minimum track record period of three financial years and (ii) meet certain minimum financial standards requirements (such as the profit test of at least HK$20 million in the latest financial year and at least a total of HK$30 million in the first two financial years, and a Growth Enterprise Market (“GEM”) applicant generally must (i) have a minimum track record period of two years and (ii) satisfy different financial standard requirements (such as possessing operating cashflow of at least HK$20 million in aggregate for the two financial years) in order to qualify for a listing on the SEHK.
With newly-formed infrastructure project companies, however, Main Board Listing Rules (Main Board Listing Rule 8.05B) and GEM Listing Rules (GEM Listing Rule 11.14) in fact allow the SEHK to accept shorter track record period and/or waive such financial listing requirements if certain conditions are met. A summary of such waiver conditions are set out below:
|
SEHK Listing Rules Waiver Conditions |
| – Listing applicant must be a party to and have the right to build and operate (or participate in the results from the operation of) the infrastructure project(s) (Note)
– At the time of listing, listing applicant must not be engaged in any businesses other than those stipulated in the infrastructure project mandate(s) or contract(s) – The infrastructure project(s) must be: ● carried out under a long term (at least 15 years) concession or mandate awarded by a government; and ● of a substantial size (i.e. company’s share of the total capital cost of the projects is at least HK$1 billion) -If the listing applicant is involved in more than one project, the majority of its projects are in the pre-construction or construction stage – The bulk of the proceeds of the offering must be used to finance the construction of the project(s), and not to repay indebtedness or acquire other non-infrastructure assets – The list applicant is restricted from acquiring other type of assets or engage in activities which will result in a change of business in the first three years after listing – The listing applicant’s substantial shareholders and management must have the necessary experience, technical expertise, track record and financial strength to carry out the project(s) to completion and to operate the project(s) thereafter. In particular, its directors and management must have sufficient and satisfactory experience of at least three years in the line of business and industry of the new applicant – Enhanced disclosure requirements may be imposed, such as the inclusion into the listing document of business valuations, feasibility studies, sensitivity analyses and cash flow projections Note: Examples of infrastructure projects include the construction of roads, bridges. tunnels, railways, mass transit systems, water and sewage systems, power plants, telecommunication systems, seaports and airport |
Implications
It appears from the current listing rules that Hong Kong regulators place a high priority on protecting the interests and investments of retail investors. The statement from the SFC can be seen as its desire to open up Hong Kong’s primary stock market to different infrastructure project companies, particularly those relating to the Belt and Road Initiative. Coupled with the New Board proposals, it could represent an opportunity for Hong Kong to capture the future growth from the Belt and Road, becoming a more attractive listing venue for infrastructure projects in Asia as well as playing a key role in bridging the infrastructure funding gap.
This newsletter is for information purposes only. Its content does not constitute legal advice, and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage.
Please contact our Eric Lui or Rodney Teoh for any enquiries or further information.