
Corporate Law Updates
Find out all about our firm’s latest Corporate Law Updates below. To learn more about any individual item, please contact us here.
Corporate Law Updates
Find out all about our firm’s latest Corporate Law Updates below. To learn more about any individual item, please contact us here.
 …
On 28 November 2024, the Hong Kong Monetary Authority (“HKMA”) has officially launched the Digital Bond Grant Scheme (“DBGS”), a key initiative announced in the 2024 Policy Address. The scheme aims to accelerate the development of the digital securities market and encourage the adoption of tokenisation technology in capital market transactions. By providing financial incentives to eligible issuances, the DBGS seeks to position Hong Kong as a global leader in digital finance.
The DBGS offers funding to cover 50% of eligible expenses for digital bond issuances, up to:
| Type of grant | Amount | Conditions |
| Half Grant | HK$1.25 million | If the issuance meets the basic requirements (as discussed below) |
| Full Grant | HK$2.5 million | If the issuance meets the basic requirements and all additional requirements (as discussed below) |
To ensure a broad distribution of resources, each issuer and its associates can receive subsidies for a maximum of two digital bond issuances.
To qualify for the scheme, digital bonds must meet the following criteria:
(1) The bond must be issued in Hong Kong, with at least 50% of the lead arrangers recognised as Hong Kong-based; and
(2) The issuance must either:
– involve a digital team with substantial operations in Hong Kong (assessed based on factors such as team size, composition, and seniority); or
– take place on a distributed ledger technology (“DLT”) platform operated by the Central Moneymarkets Unit (“CMU”).
Issuances seeking the Full Grant must meet the following additional requirements:
The scheme also provides reimbursement for various issuance-related costs, including fees paid to DLT platform providers, arrangers, legal advisers, auditors, accountants, and rating agencies, provided these service providers are based in Hong Kong and are independent of the issuer. Listing fees for SEHK or SFC-licensed VATPs, as well as lodging and clearing fees charged by the CMU, are also covered under the scheme.
For issuances classified as green, social, sustainability, or transition bonds, the DBGS may work in conjunction with the GSF Grant Scheme to cover issuance costs. However, issuers must ensure that the same expenses are not claimed under both schemes, as dual funding for identical cost categories is prohibited.
Applications for the DBGS are now open and will be accepted for the next three years. Detailed guidelines have been published by the HKMA, outlining the eligibility criteria, application process, and reimbursement procedures. The HKMA has also indicated that it will monitor market developments closely and may refine the scheme’s structure if necessary. All decisions regarding eligibility and subsidy amounts will be at the sole discretion of the HKMA.
The launch of the DBGS underscores Hong Kong’s commitment to advancing its position as a global leader in digital securities. By fostering innovation and promoting tokenisation technology, the scheme is expected to attract issuers and investors, contributing to the long-term development of the city’s capital markets.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
A. Introduction
The Securities and Futures Commission (“SFC”) has released a circular (the “Circular”) detailing expectations for licensed corporations (“LCs”) adopting generative artificial intelligence language models (“AI LMs”). While being supportive of the use of AL and AL LMs by LCs, the SFC also acknowledges that AI LMs are susceptible to risk and require necessary safeguards. In particular, the uses of AL LM for providing investment recommendations, investment advice or investment research to investors are considered to be high-risk use cases.
B. Scope of the Circular
The scope of the Circular is intended to cover LCs offering services or functionality provided by AI LMs or AI LM-based third-party products in relation to their regulated activities, irrespective of whether the AL LM is developed by the LC itself, its group company, an external service provider or sourced from open platforms.
C. Core Principles for Managing AI LMs
The SFC emphasises four core principles to guide LCs in the responsible adoption of AI LMs:
1. Senior Management Oversight
Senior management is responsible for ensuring proper governance throughout the AI LM lifecycle, from development and deployment to decommissioning. They should establish effective policies, procedures, and internal controls to manage risks and oversee the implementation of AI systems.
Senior management should also ensure qualified staff from business, risk, compliance, and technology functions are involved in overseeing AI LM adoption. Staff should possess competence in AI, data science, and regulatory compliance to address risks effectively. For high-risk use cases, such as investment recommendations or financial advice, heightened governance and additional risk controls are required to protect clients and investors.
While LCs may delegate certain functions, such as model validation, to their group companies, ultimate responsibility for compliance with legal and regulatory requirements remains with the LC.
2. AI Model Risk Management
An LC should implement a robust AI model risk management framework to ensure AI LMs remain fit for purpose. Key measures include conducting thorough validation before deployment and when significant changes are made to the model’s design or inputs, testing the model’s performance across all processes, including input, output, and any related systems and regularly monitoring and reviewing AI LM performance to address potential drifts or degradations over time.
For high-risk applications, LCs should adopt additional safeguards, such as human oversight of AI outputs and testing for consistency across variations in input prompts. Comprehensive documentation of all testing, validation, and monitoring activities is required.
The SFC distinguishes between off-the-shelf AI LM products and models developed or customised by LCs. While off-the-shelf products also require proper model management, customised models demand more rigorous oversight.
3. Cybersecurity and Data Risk Management
AI LMs are susceptible to adversarial attacks, data breaches, and other cybersecurity threats. LCs should implement robust controls, such as periodic adversarial testing, encryption of sensitive data, and measures to prevent data leakage through browser extensions or user inputs.
To ensure data integrity, LCs should mitigate biases in training data and comply with data protection laws. Particular care should be taken to protect sensitive information, such as client data, from being inadvertently exposed or exploited through AI LM training or use.
4. Managing Risks of Third-Party Providers
The SFC advises LC to exercise due skill, care and diligence to assess third party providers’ expertise, controls, and risk management frameworks.
The LC should evaluate the whether the third party provider itself has an effective model risk management in place and if the performance of the AL LM is appropriate for the LC’s specific use. The LC should also assess the third-party providers’ data management and consider if a breach by the third party provider of applicable personal data privacy or intellectual property laws could have a material adverse impact on the LC.
LCs should also prepare contingency plans to address service disruptions or operational failures stemming from third-party dependencies. Supply chain vulnerabilities and data leakage risks should be carefully monitored.
D. Notification and Compliance Requirements
LCs intending to use AI LMs for high-risk applications are reminded to comply with the notification requirements under the Securities and Futures (Licensing and Registration) (Information) Rules. Notifications are required significant changes in the LC’s nature of business and types of services provided. Early engagement with the SFC during the planning and development stages is recommended to address potential regulatory implications.
The SFC expects LCs to review and update their existing policies to comply with the circular’s requirements. Although immediate compliance is required, the SFC acknowledges that some LCs may need time to fully implement the necessary measures.
E. Conclusion
The SFC’s guidance underscores the importance of balancing innovation with responsibility in adopting AI LMs. By implementing robust governance, risk management, and cybersecurity measures, LCs can harness the benefits of AI while safeguarding against potential legal, operational, and reputational risks.
LCs are encouraged to engage proactively with the SFC to ensure alignment with regulatory expectations.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
Stevenson, Wong & Co. acted for Xichang Haihe Cultural Tourism Investment Development Co., Ltd. (the “Issuer”) as international counsel in its successful listing and issuance of US$10,000,000 7% guaranteed bonds due 2027 (the “Bonds”). The Bonds were listed on Chongwa (Macao) Financial Asset Exchange Co., Limited (“MOX”) on 16 December 2024 (MOX Bond Code: MOXTB24323).
 …
The Issuer is a state-owned company which is indirectly controlled by Xichang Finance Bureau and ultimately controlled by Xichang People’s Government. The main business scope of the Issuer includes building materials sales, scenic spot operation and maintenance services, urban transportation services, house rental and management services, travel services and other services.
Our team was led by Partner Rodney Teoh, supported by Associate Angela Lau, Paralegal Austin Kot (pending admission), Trainee Solicitor Trendy Leung and Paralegal Jay Lee.
Please contact our Partner Rodney Teoh for any enquiries or further information.
Background
The Securities and Futures Commission (the “SFC”) and The Stock Exchange of Hong Kong Limited (the “Exchange”) have jointly unveiled a new Enhanced Application Timeframe for the listing process in Hong Kong. The initiative aims to offer greater clarity, efficiency, and transparency during listing application processes, and bolster Hong Kong’s competitive edge as a leading international listing venue.
 …
Enhanced Application Timeframe
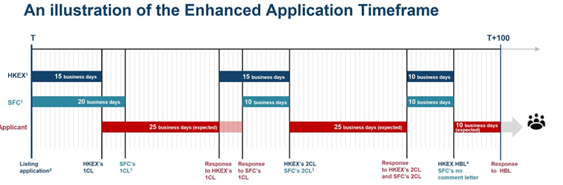
The Enhanced Application Timeframe is designed to give applicants more certainty regarding the timeline for reviews. For applications that fully meet all applicable requirements, both the SFC and the Exchange will provide their regulatory assessments within 40 business days, after a maximum of two rounds of comments. Applicants are expected to take around 60 business days to address all comments and complete the application process within the six-month validity window.
An illustration of the Enhanced Application Timeframe is extracted from the joint statement and set out as follows:
Accelerated Timeframe for A-share Listed Companies
A company may qualify for an accelerated process if it has already been listed in Mainland China (A-share listed) with a market capitalisation of at least HK$10 billion, and complied, in all material respects, with the laws and regulations applicable to it’s A-share listing for the past two full financial years. In this case, the review process will be completed in just one round of comments, with the regulators completing their assessments within 30 business days.
Applications Requiring Longer Review
For applications where material regulatory concerns arise, or where responses are incomplete, the review process may take longer. In such circumstances, the regulators will engage closely with the applicant and their advisers, offering further guidance to address concerns. If problems persist after two rounds of comments, a formal requisition letter may be issued, lengthening the process.
Strengthening Hong Kong’s Capital Markets
Both the SFC and the Exchange are confident that the Enhanced Application Timeframe will improve the listing experience by offering greater predictability for applicants. The new process will help Hong Kong maintain its competitive edge as a top destination for companies seeking to go public. Regulatory leaders emphasise their commitment to working with applicants and their advisers to ensure efficient, high-standard listings.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
Stevenson, Wong & Co. acted for the joint lead managers in the successful listing and issuance of US$55,000,000 7.5% guaranteed Bonds due 2027 (the “Bonds”) by Renshou Urban Investment Group Co., Ltd. (the “Issuer”). The Bonds were listed on Chongwa (Macao) Financial Asset Exchange Co., Limited (“MOX”) on 26 September 2024 (MOX Bond Code: MOXTB24227).
 …
The Issuer is a directly wholly-owned company of Renshou County State-owned Assets and Financial Work Bureau. The Issuer is an important investment and management entity of state-owned property and a main operation entity for production and sales of electronic products and wire and optical cable, transfer of own land, water affairs, agent construction service fees, and engineering product in Renshou.
Our team was led by Partner Rodney Teoh, supported by Associates Angela Lau and Audrey Ng, Paralegal Austin Kot (pending admission), Trainee Solicitor Trendy Leung and Paralegal Jay Lee.
Please contact our Partner Rodney Teoh for any enquiries or further information.
Introduction
On 14 June 2024, the Stock Exchange of Hong Kong Limited (the “Exchange”) of the Hong Kong Exchanges and Clearing Limited published a consultation paper (the “Consultation Paper”) inviting public feedback on the proposed enhancements to the Corporate Governance Code (the “CG Code”) and related amendments to the Listing Rules by 16 August 2024. It is proposed that the amendments will apply to corporate governance reports (“CG Reports”) and annual reports for financial years commencing on or after 1 January 2025, with a 3-year transition period for specified proposals pertaining to independent non-executive directors (“INEDs”).
 …
The main areas of focus in the Consultation Paper are: (i) board effectiveness, (ii) independence of INEDs, (iii) board and workforce diversity, (iv) risk management and internal controls, and (v) dividends.
Board Effectiveness
Enhancing board effectiveness is essential for strengthening corporate governance. This involves ensuring that the board composition reflects a well-balanced blend of skills, experience, and diverse perspectives, enabling it to function effectively in an ever-changing market environment.
| Proposals | Details | |
| Designation of a Lead INED | To better facilitate communication between investors and the board; among INEDs; and between INEDs and other directors, the Exchange propose to state that issuers should designate one INED as a Lead INED.
For issuers with an independent board chair (i.e. a board chair who is an independent director) – the board chair will fulfil the role of the Lead INED, unless the issuer designates another INED as the Lead INED. For issuers without an independent board chair (i.e. a board chair who is not an independent director, including board chairs who is also the chief executive) – designate one INED as the Lead INED. Where an issuer does not designate a Lead INED, it may provide reasons to explain, for example, the issuer already has in place alternative shareholder communication channels. Roles and responsibilities of a Lead INED: · is primarily responsible for strengthening communication between INEDs, the board, and shareholders, to enable shareholders to better understand the decisions made by INEDs; |
|
| Mandatory director training and disclosure | For all directors of issuers listed on the Exchange | Mandatory continuous professional training: All such directors must participate in mandatory continuous director training on specific topics. There is no specified minimum training hours or training format requirement.For directors appointed to fill a casual vacancy, the proposed training requirements will apply from the issuer’s full financial year following the appointment.Disclosure requirement: Issuers must confirm that directors have participated in the required training, and disclose the following:· the number of hours; · the topics of the training attended; · the format of the training (e.g. by physical attendance or remotely); and · the names of relevant training providers (if external). |
| For first-time directors (i.e. directors who are appointed as a director of an issuer listed on the Exchange for the first time, or have not served as a director of an issuer listed on the exchange for a period of 3 years or more prior to their appointment)
(with a 3-year transition period) |
Mandatory 24-hour training requirement: First-time directors must undergo a minimum of 24 hours of training, to be completed within the first 18 months of the date of appointment.If a first-time director leaves the issuer before completing the 24-hour training, the requirement resets for the subsequent appointment.Additional Disclosure requirement: Issuers must confirm that first-time directors have completed the minimum of 24 training hours within 18 months following their appointment. |
|
| Board performance review and disclosure | A board performance review must be conducted at least once every 2 years, with specific disclosures in the CG Report, on a “comply and explain” basis.
Format: Issuers has discretion to determine the format of the review, including whether it is conducted internally or through external providers. Content: The review should focus on the board’s performance as a whole, rather than assessing each director individually. |
|
| Board skills matrix and disclosure | Issuers must maintain a board skills matrix in the CG Report, with enhanced disclosures on the following information:
(i) the existing skills mix of their boards; |
|
| Overboarding INED and directors’ time commitment
(with a 3-year transition period) |
A hard cap will be imposed on INEDs such that INEDs can only take up a maximum of six Hong Kong-listed issuer directorships.
The nomination committee must annually assess and disclose each director’s time commitment and contribution to the board, taking into account their listed issuer directorships and other significant external time commitments. |
|
Independence of INEDs
The proposed amendments aim to promote periodic board refreshment and strengthen independent voices on issuers’ board. This is intended to bring in fresh perspectives and maintain the objectivity of INEDs.
| Proposals | Details |
| Cap on Long Serving INED (“INED who has served for more than nine years on the board of a listed issuer”)
|
It is proposed to impose a hard cap of nine years on the tenure of INEDs. |
| Two-year cooling off period | An INED will be allowed to serve as an INED of the same issuer again after a 2-year cooling off period. During this cooling-off period, such individual must not serve as a director of the issuer, its holding company, any of their subsidiaries, or any core connected persons of the issuer. |
| Three-year transition period | The proposed rule will apply from 1 January 2028 onwards. A three-year transition period is proposed for the implementation of this regulation to ensure board continuity and provide sufficient time for affected issuers to conduct proper succession planning and adjust their board composition. |
Board and Workforce Diversity
In order to facilitate unique perspectives, robust discussions and resilient decision-making, the Exchange focuses on improving diversity and inclusion in the boardroom as well as all levels of the company.
| Proposals | Details |
| Nomination Committee Composition
|
The nomination committee must comprise directors of different genders. |
| Diversity Policies | Issuers are required to establish and disclose a diversity policy for their workforce (including senior management).
Issuers are required to make separate disclosure of the gender ratio of senior management and the workforce (excluding senior management). |
| Arrangements during temporary deviations from board gender composition requirements | if an issuer fails at any time to have directors of different genders on the board (e.g. where the only female director resigns), it would be required to immediately publish an announcement containing the relevant details and reasons. |
Risk Management and Internal Controls
The proposed amendments aim to improve market quality and corporate governance through continuous monitoring, periodic reviews and reporting on risk management and internal controls (“RMIC”).
| Proposals | Details |
| Annual review of RMIC systems | The requirement to conduct (at least) an annual review of RMIC systems of the issuer and its subsidiaries will be upgraded to a mandatory requirement. It will be the responsibility of the board to ensure that the necessary reviews are conducted, and for management to confirm to the board the effectiveness of these systems. |
| Detailed disclosures | The board is required to make detailed disclosures on the following:
(a) the RMIC systems in place (including any significant changes made to the RMIC Systems); (b) the process through which the review of the RMIC Systems was conducted; (c) a confirmation from the board on the appropriateness and effectiveness of the RMIC Systems, as well as information supporting the board’s conclusion (including confirmations received (as applicable) from management, the relevant board committee(s) with responsibility for the issuer’s RMIC Systems, any other internal departments, the issuer’s independent auditors and/or other external providers); and (d) details of any significant control failings or weaknesses identified during the review and/or previously reported but unresolved, and any remedial steps taken or proposed. |
Dividends
The Exchange proposes imposing an enhanced disclosure requirement in the CG Report on an issuer’s dividend policy (or an explanation as to the reasons for not having such policy) and its board’s dividend decisions, in order to promote transparency and facilitate shareholders and investors in making informed investment decisions.
| Proposals | Details |
| For issuers with a dividend policy | It is required to (i) disclose the aim/objective of the policy and the key considerations in deciding whether to declare, recommend or pay any dividend; and (ii) confirm board adherence to the dividend policy (or otherwise, explanation for any deviations). |
| For issuers without a dividend policy
|
A statement of the absence of a dividend policy and the reasons. |
| In relation to the board’s dividend decisions | Disclosure is required of (i) an explanation for any material variations in dividend rates during the reporting period as compared to the previous corresponding period; and (ii) the reasons for non-declaration of dividend and the planned measures to enhance investors’ return (if any). |
Analysis and takeaways
The Consultation Paper reflects the Exchange’s dedication to fortifying corporate governance practices across multiple key areas. The focus on board effectiveness, INED independence, and diversity indicates a strong commitment to enhancing governance structures. Furthermore, the proposals on the review of RMIC systems and the enhanced disclosures in relation to RMIC and dividend policies signal a move towards greater transparency in these vital areas, underscoring the importance of investor and shareholder protection and market quality.
Overall, these proposed amendments demonstrate a proactive approach to promoting robust corporate governance practices that prioritize transparency, accountability, diversity, and sustainability in Hong Kong’s listed companies.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.