Corporate Law Updates
Find out all about our firm’s latest Corporate Law Updates below. To learn more about any individual item, please contact us here.

Corporate Law Updates
Find out all about our firm’s latest Corporate Law Updates below. To learn more about any individual item, please contact us here.
On 24 March 2023, The Stock Exchange of Hong Kong Limited (the “Exchange”) published the consultation conclusions (the “Conclusions”) on the new listing framework for Specialist Technology Companies (“STCs”). The Conclusions were issued in response to the two-month consultation (the “Consultation”) in respect of the consultation paper (the “Consultation Paper”) published by the Exchange on 19 October 2022 (see our news update on the Consultation).
The new listing regime will be added as Chapter 18C of the Rules Governing the Listing of Securities on The Stock Exchange of Hong Kong Limited (the “Listing Rules”), and the corresponding amendments, together with the Guidance Letter on Specialist Technology Companies (the “Guidance Letter”) will come into effect on 31 March 2023. Commencing on the same day, companies may submit a formal application for listing under the new regime.
The Exchange will implement the proposals as set out in the Consultation Paper, subject to certain amendments. Set out below are the key features of the new listing regime.
…
Definition of “Specialist Technology Companies”
The Exchange will adopt the proposed definitions of STCs without amendment,1 which is defined as “a company primarily engaged (whether directly or through its subsidiaries) in the research and development of, and the commercialisation and/or sales of, Specialist Technology Products (“STPs”) within an acceptable sector of a Specialist Technology Industry”.
STP is defined as “a product and/or service (alone or together with other products or services) that applies Specialist Technology”, and “Specialist Technology” is defined as “science and/or technology applied to products and/or services within an acceptable sector of a Specialist Technology Industry”.2
List of Specialist Technology Industries and acceptable sectors
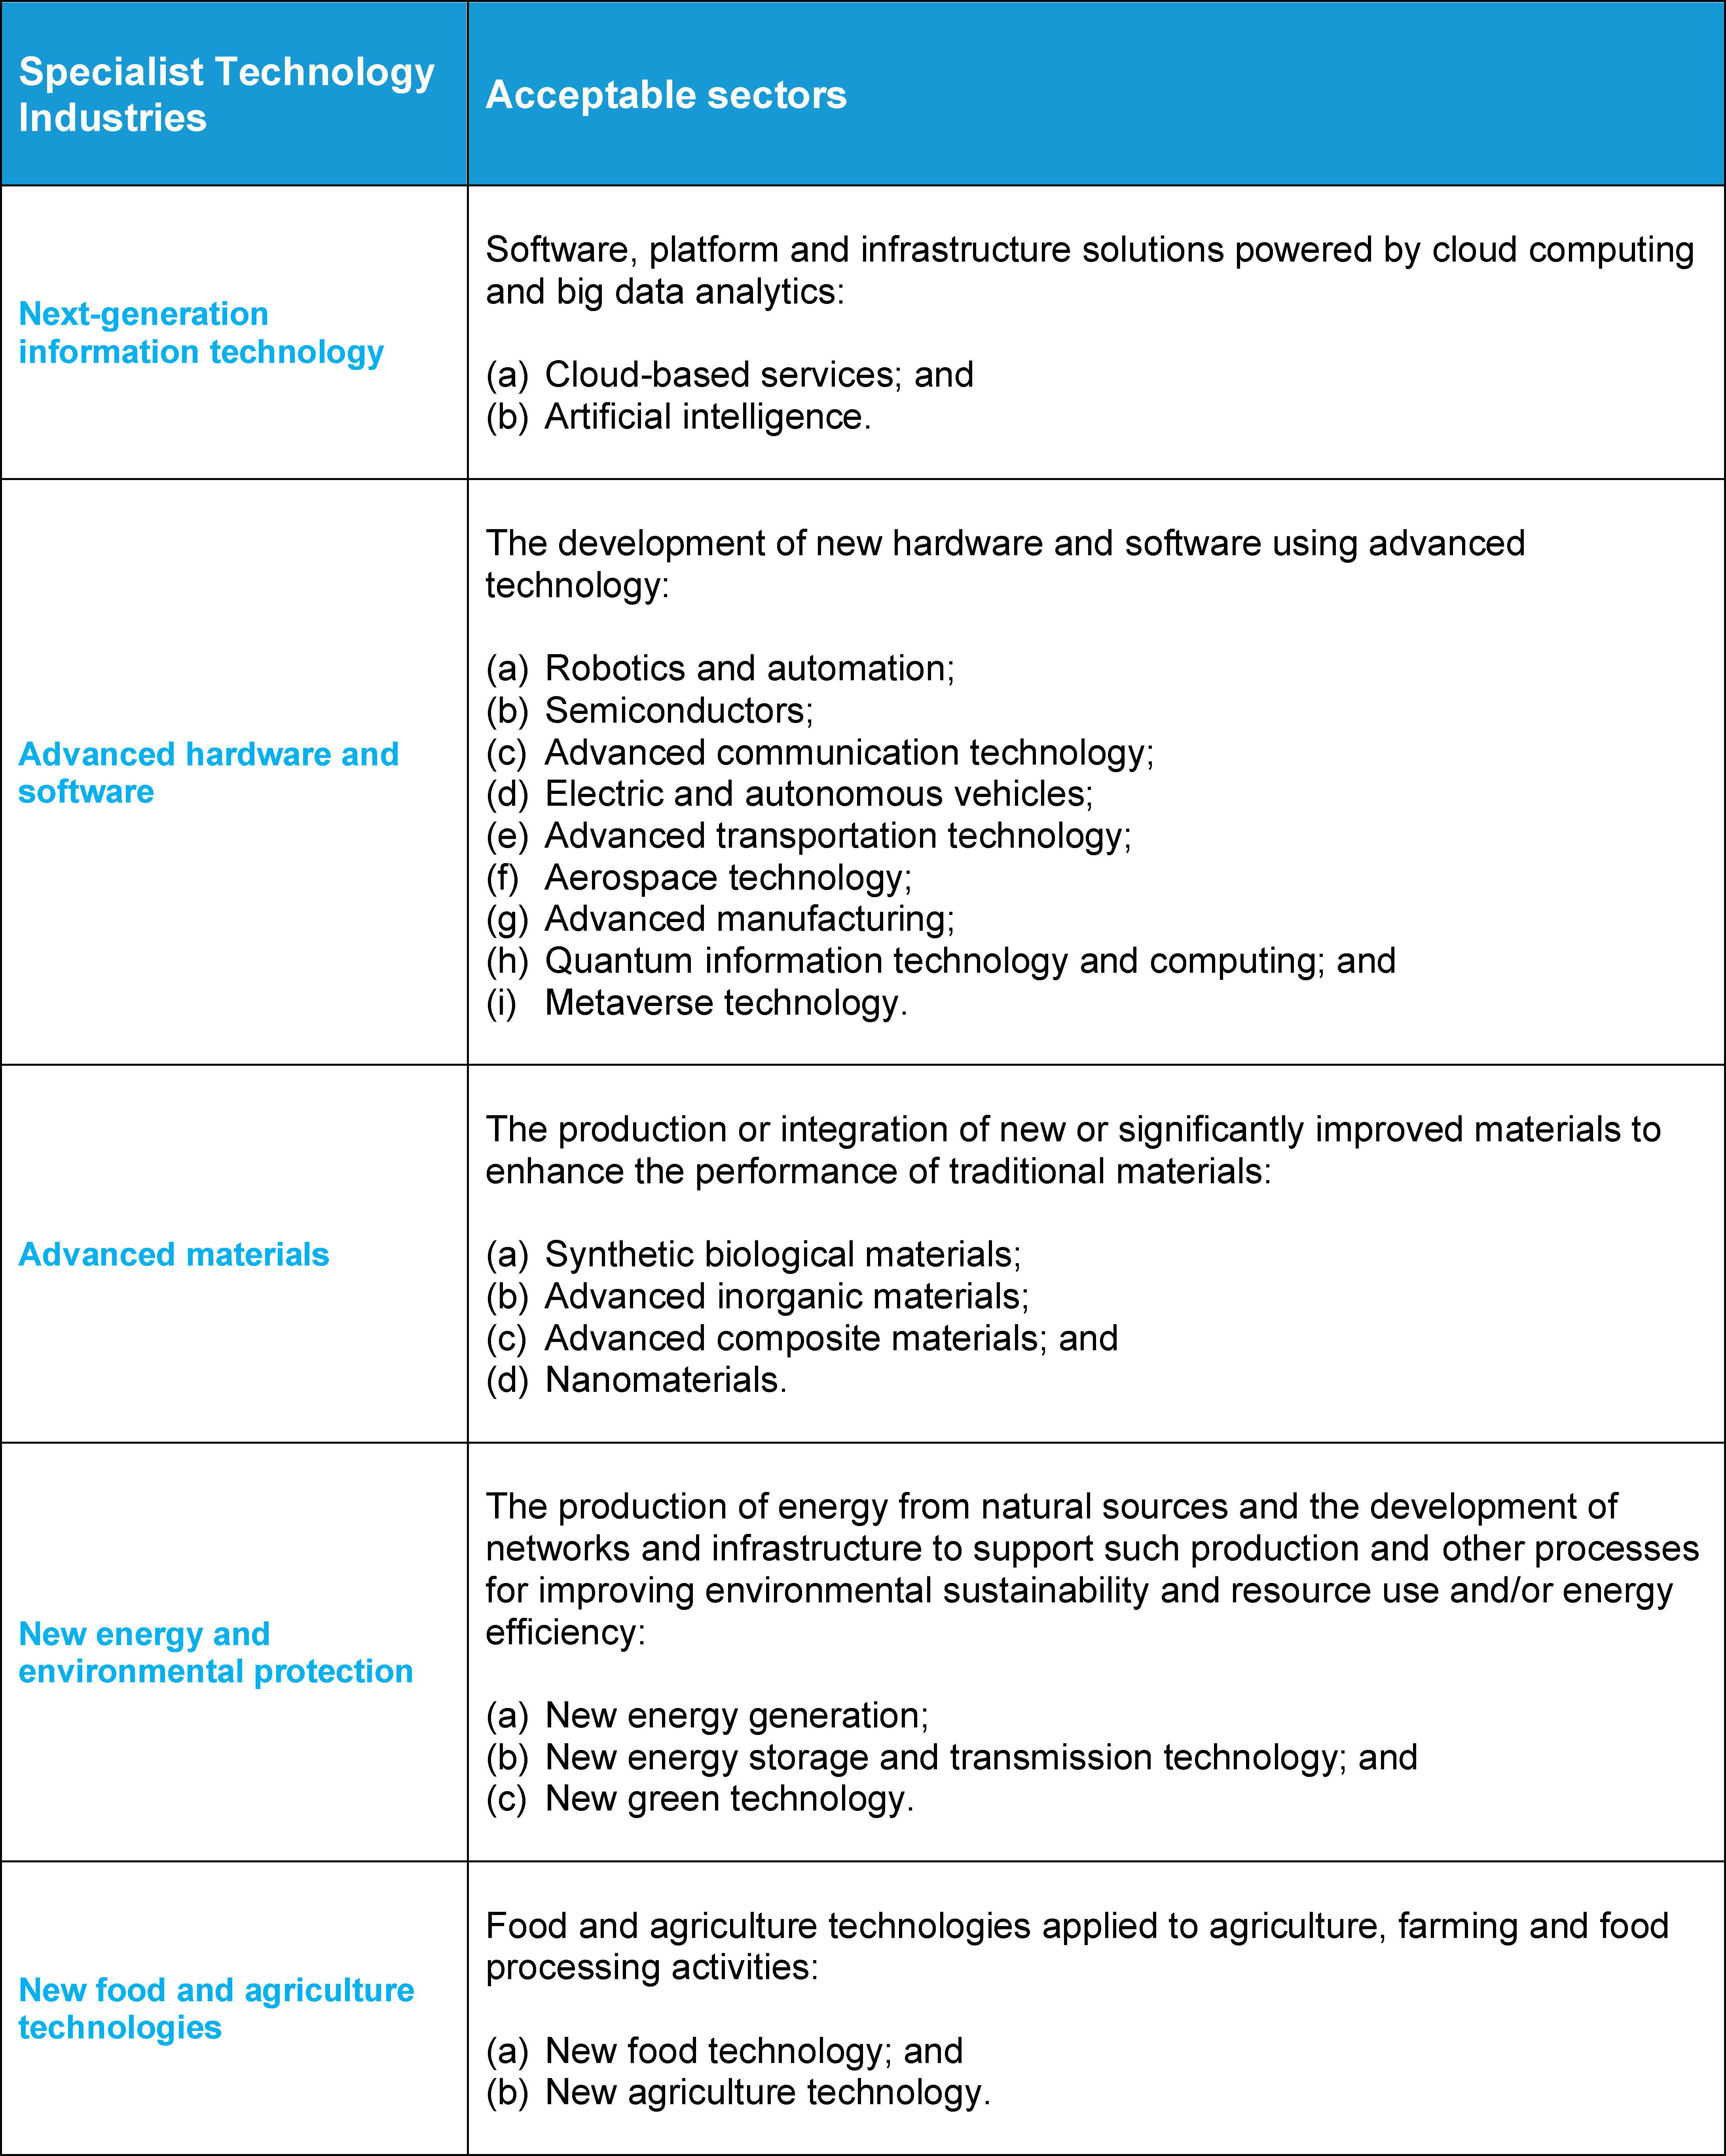
In respect of the Specialist Technology Industries and acceptable sectors, the Exchange will adopt the proposed list set out in the Consultation Paper with amendments, and the list will be published in the Guidance Letter to be updated from time to time by the Exchange after consultation with the Securities and Futures Commission and with its approval.3 Summary of the list of Specialist Technology Industries and the non-exhaustive acceptable sectors are as follows:4

The Exchange has specifically excluded blockchain and digital asset related business in the list as such companies’ success is considered generally attributable to the expansion of mining capacity, rather than the application of new technology, with minimal contribution of research and development (R&D) to the companies’ expected value5 .
Applicants falling outside the existing list of Specialist Technology Industries and acceptable sectors
An applicant falling outside the list of Specialist Technology Industries or acceptable sectors above may still be considered as “within an acceptable sector of a Specialist Technology Industry” for the purpose of the definitions of STC and “Specialist Technology” if it can demonstrate that:6
(a) it has high growth potential;
(b) its success can be demonstrated to be attributable to the application, to its core business, of new technologies and/or the application of the relevant science and/or technology within that sector to a new business model, which differentiates it from traditional market participants serving similar consumers or end users; and
(c) research and development significantly contributes to its expected value and constitutes a major activity and expense.
Such applicant must submit a pre-IPO enquiry to the Exchange before submitting a listing application under Chapter 18C of the Listing Rules7 , and the Exchange will assess by taking into account all relevant facts and circumstances and consult with the SFC and seek its approval.8
Companies with multiple business segments
In respect of applicants with multiple business segments, the Exchange will adopt a holistic assessment of the non-exhaustive factors set out in the Guidance Letter and take into account the following additional factors when assessing whether an applicant is eligible for listing under Chapter 18C:9
(a) the proportion of the revenue (if any) generated by the Specialist Technology business segment(s) relative to the total revenue of the company (instead of prescribing a “bright line” percentage threshold); and
(b) the reason for retaining the non-Specialist Technology business segment(s) and the history of the company’s operations.
Categorisation of Commercial / Pre-Commercial Companies
The Exchange has adopted its proposal to accommodate the listings of Commercial Companies and Pre-Commercial Companies, with more stringent requirements imposed on Pre-Commercial Companies than Commercial Companies11 , and that all investors (including retail investors) be allowed to subscribe for, and trade in, the securities of Pre-Commercial Companies.12
Requirements
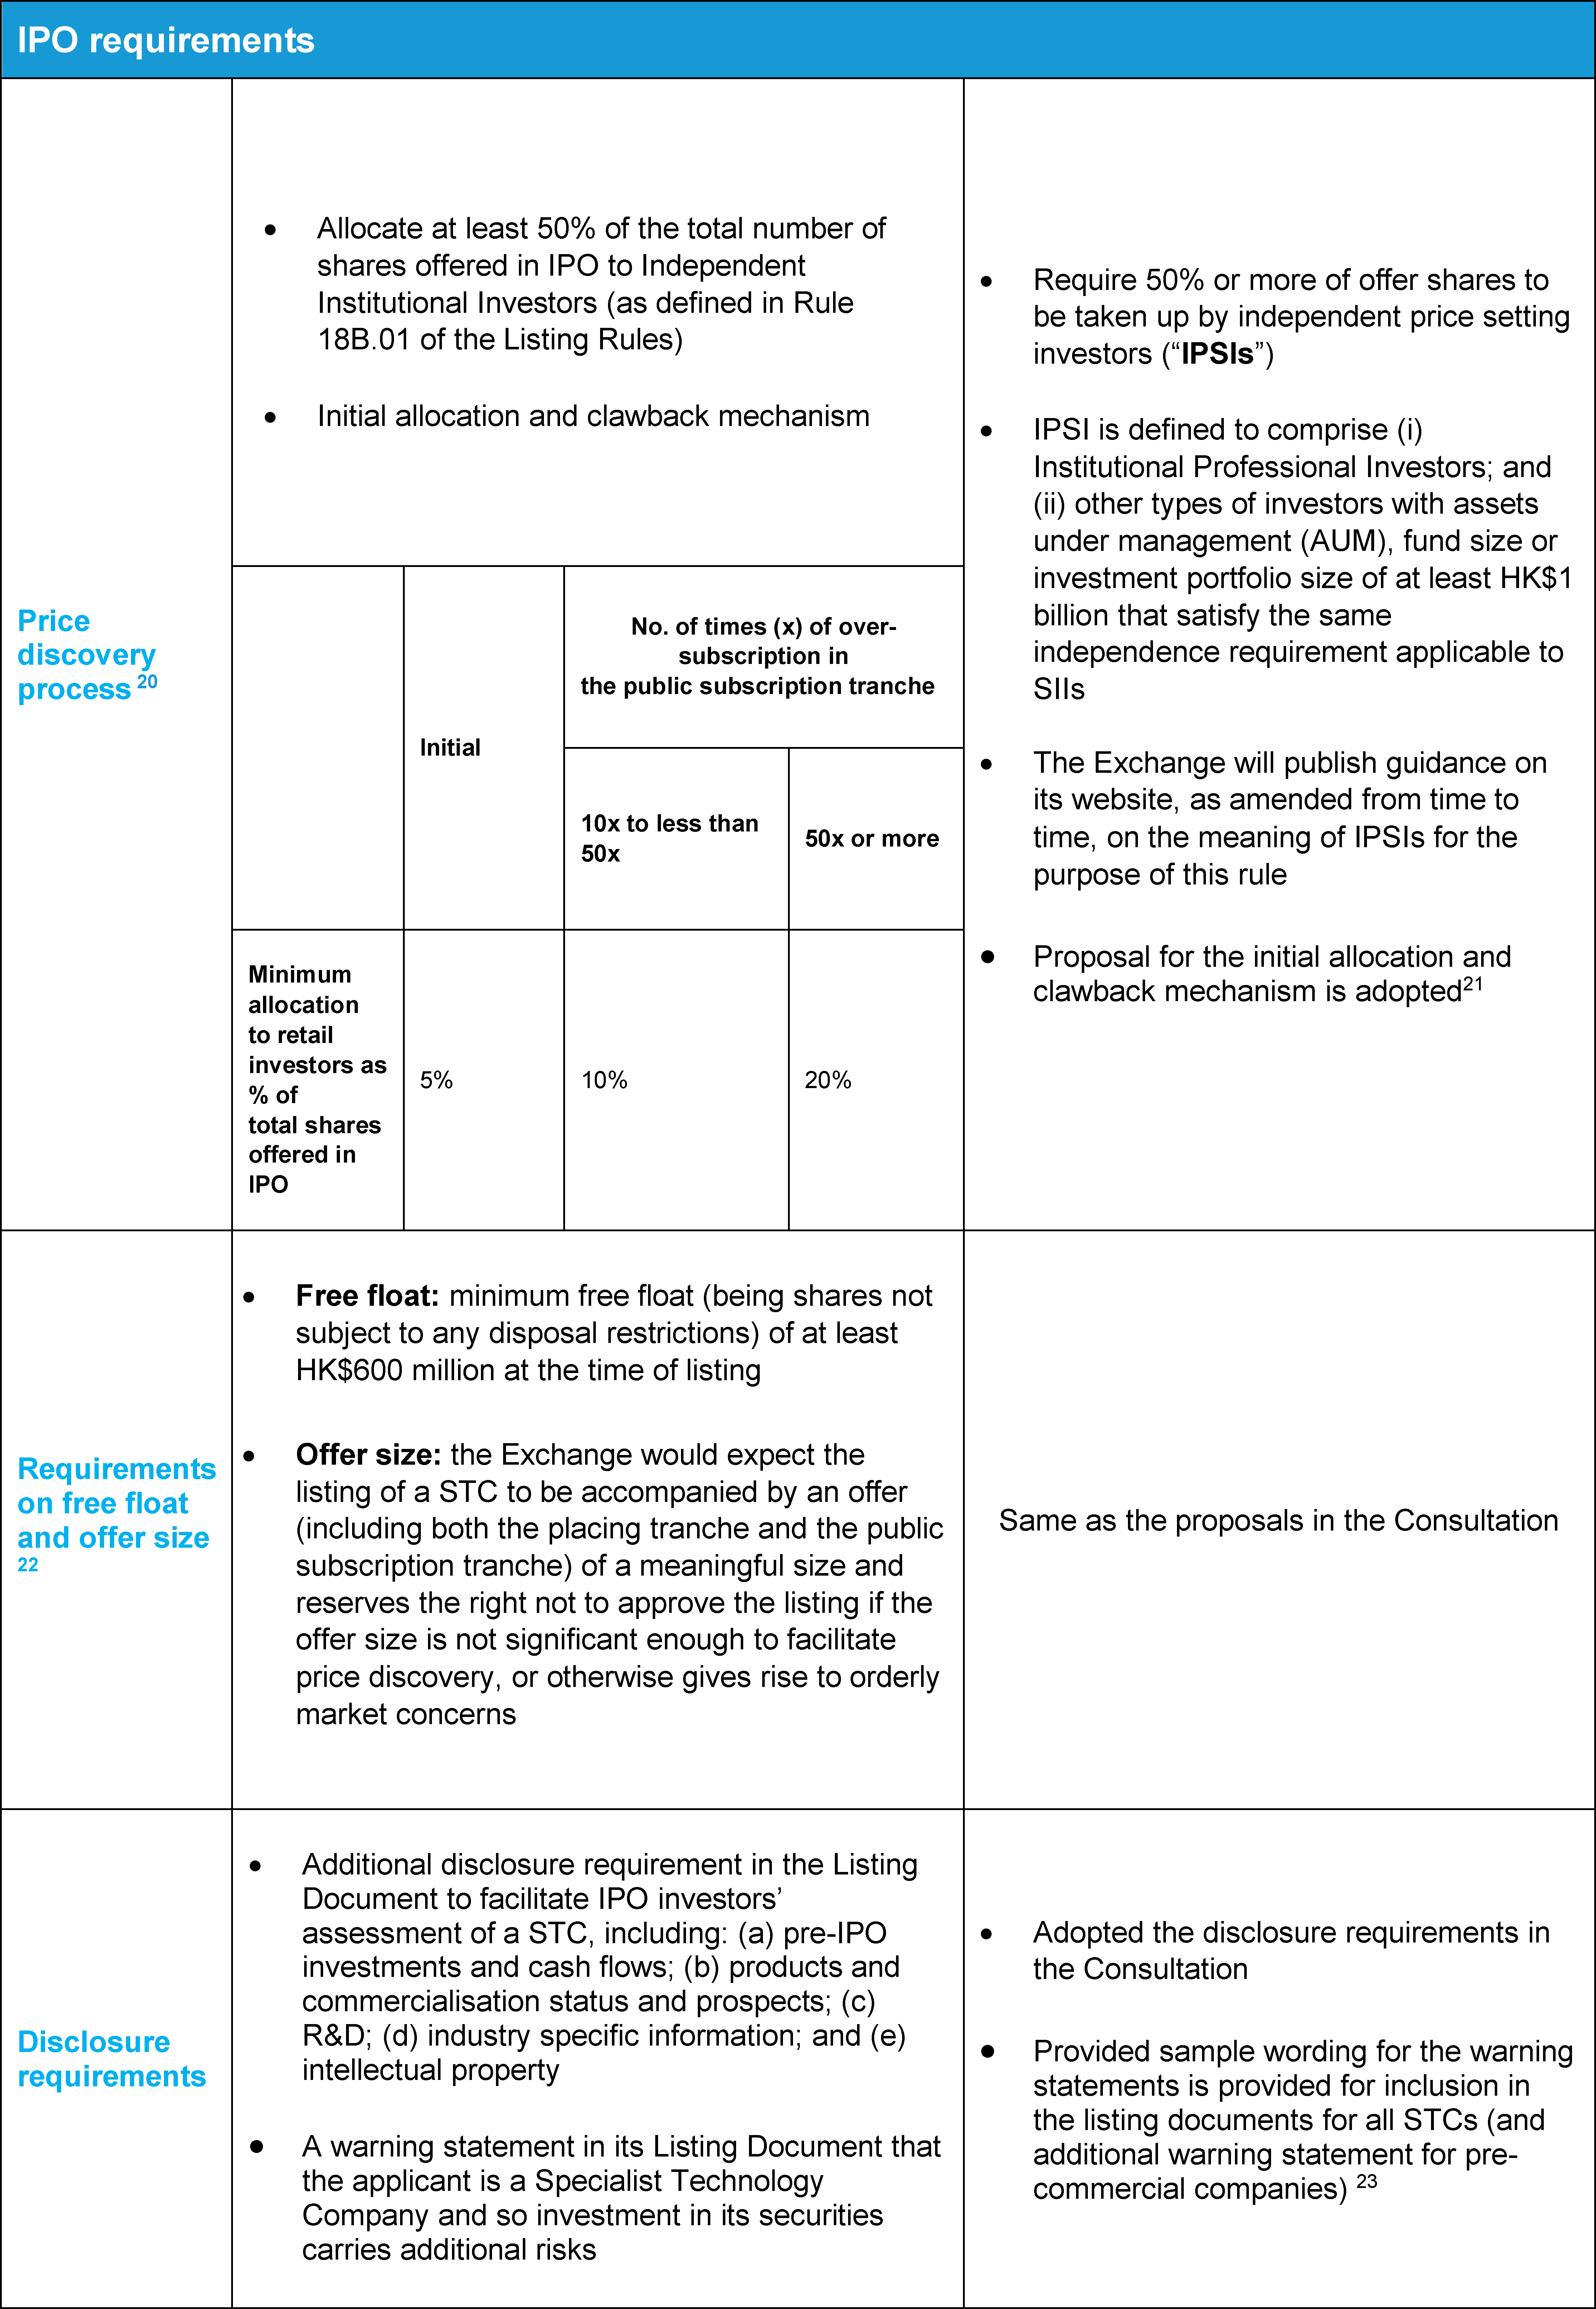
The below table sets out a comparison of the key requirements for Commercial Companies and Pre-Commercial Companies to be eligible for listing as set out in the Conclusions:


Additional qualification requirements for Pre-Commercial Companies24
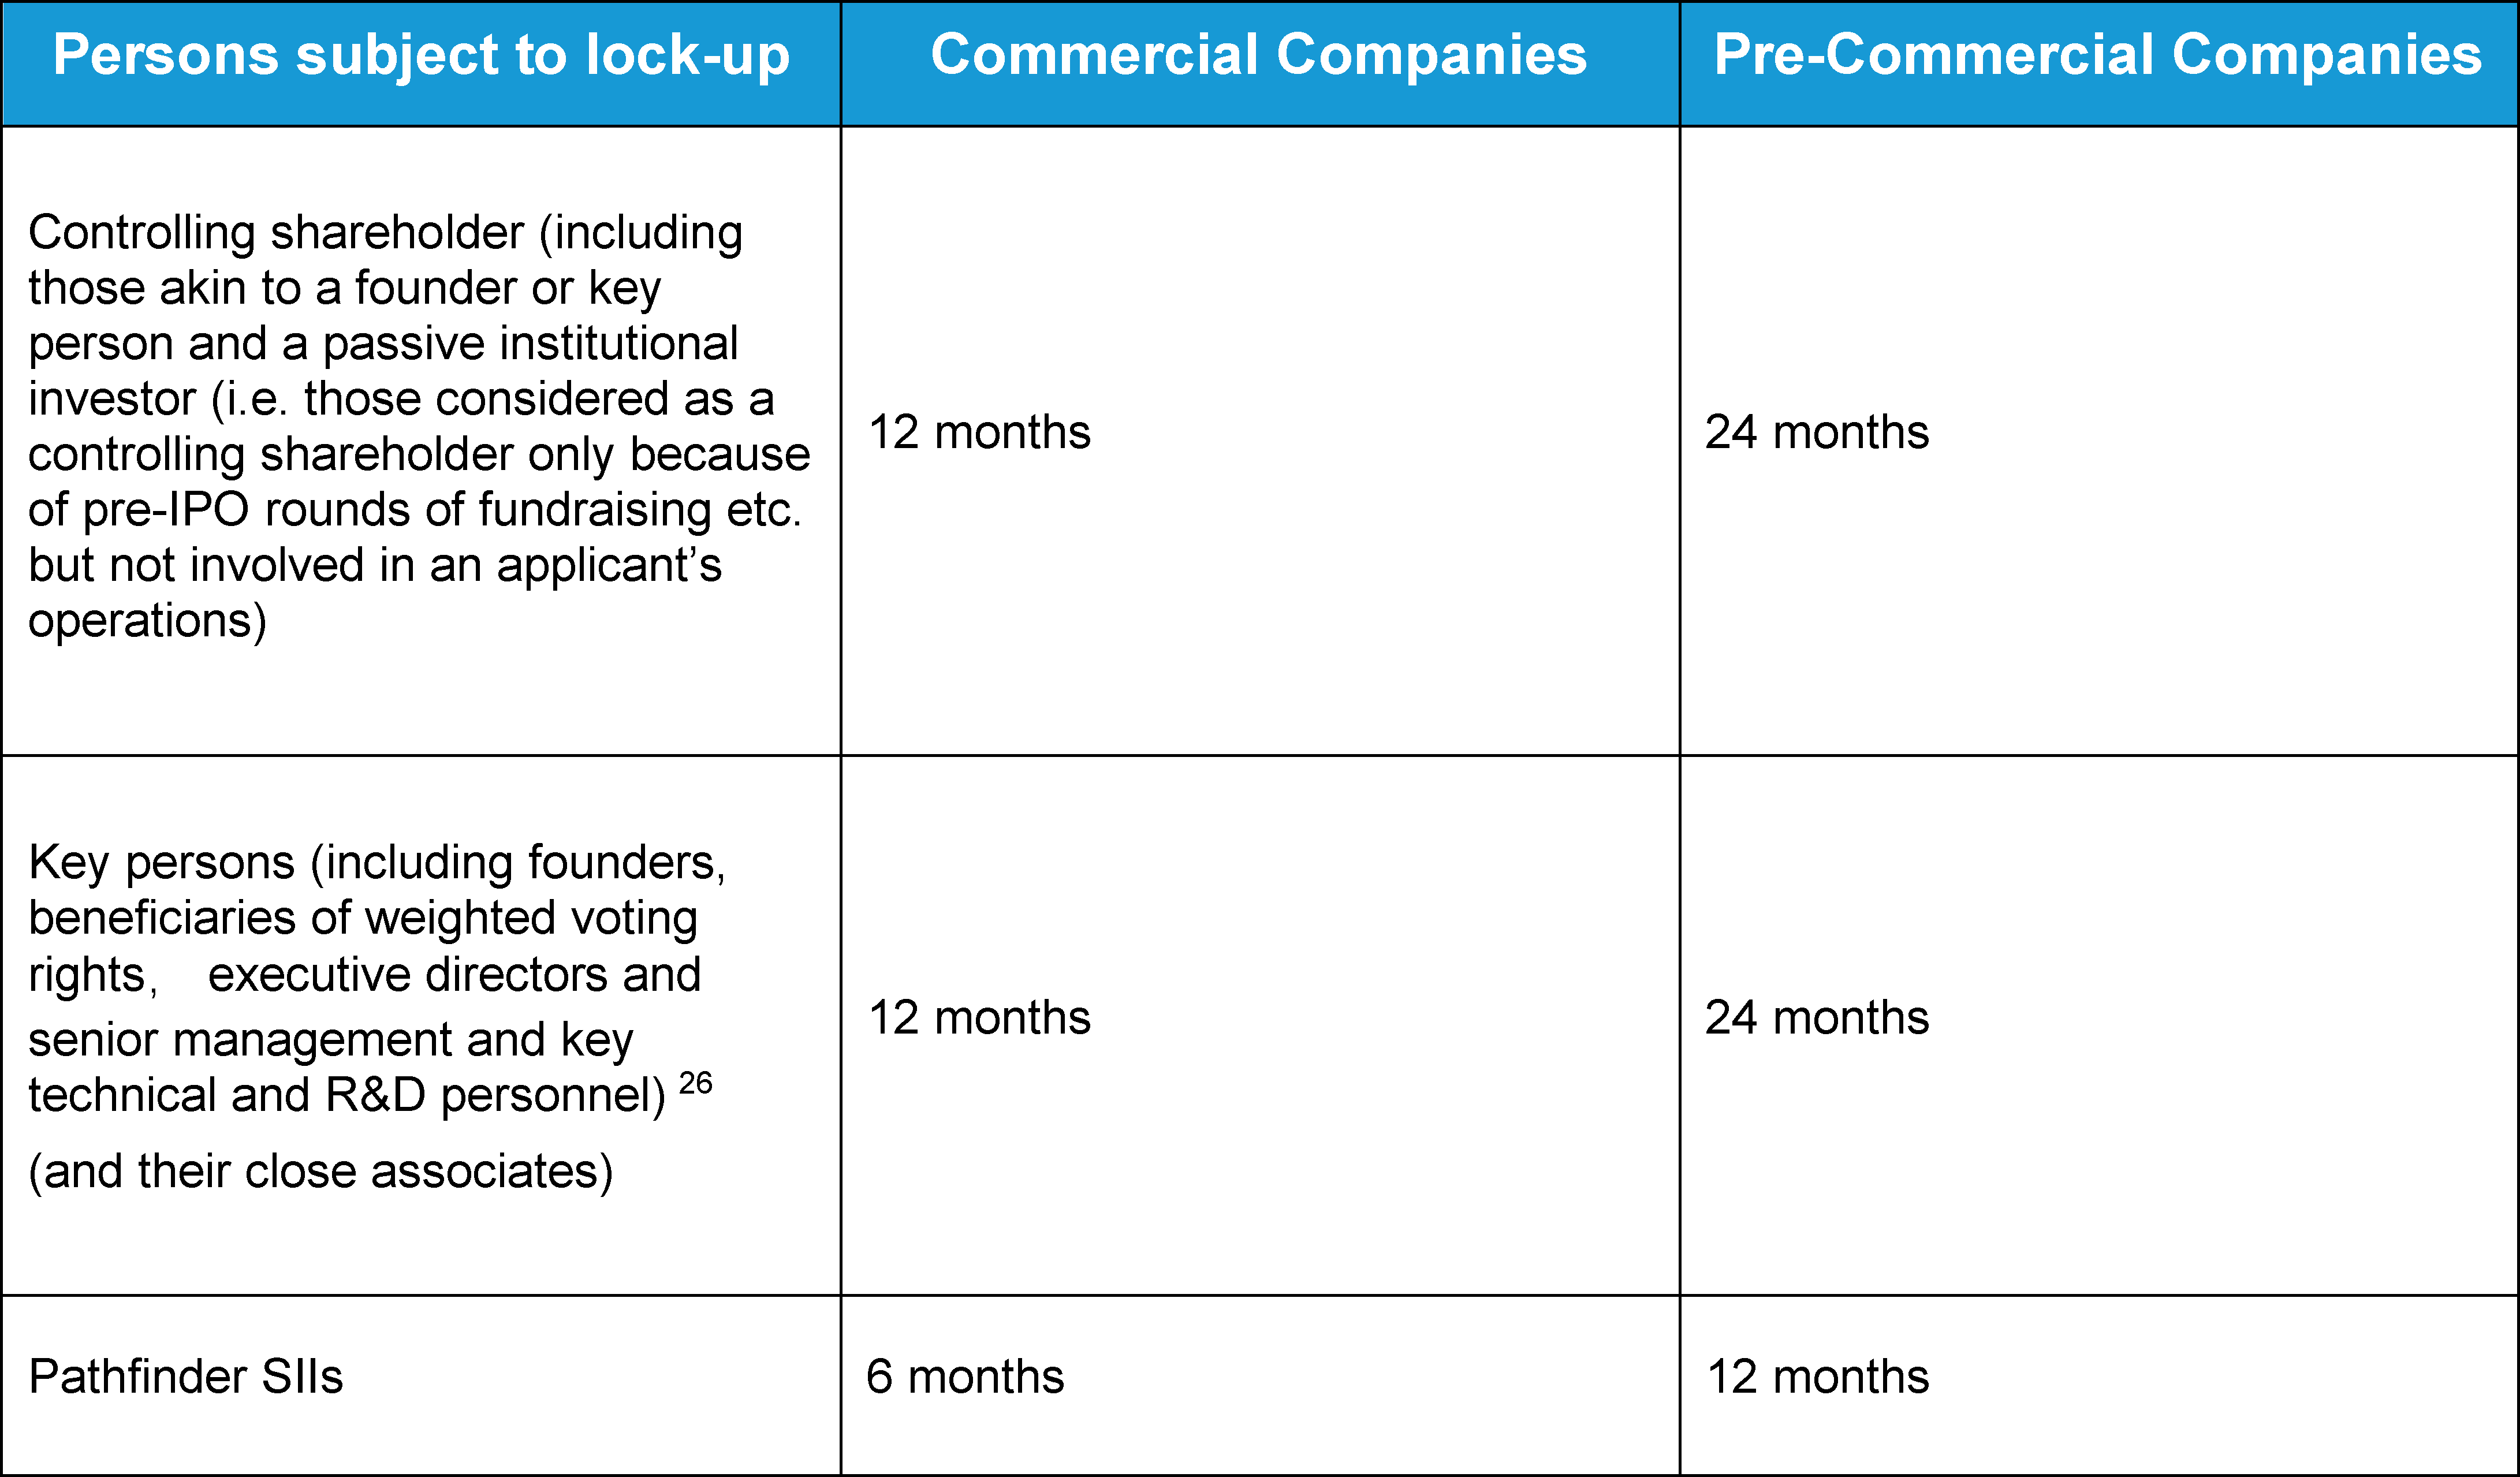
Post-IPO lock-up25
Scope of the target persons subject to post-IPO lock-up of STCs is wider than the main board issuers with a longer lock-up period. In particular, the applicable post-IPO lock-up for STCs is as follows:

Analysis and Takeaways
While the value of STCs may be difficult to estimate, due diligence and in-depth research on the capabilities of performance of STCs, as well as the participation of investors with professional experience and industry expertise are crucial to the price setting of shares of STCs. The IPSI mechanism, with a 50% share allocation percentage requirement, introduced by the Exchange in view of overcoming the difficulty in price-setting, has in fact created certain challenges for STC listing applicants as they lose some flexibilities in seeking general investors’ support.
Nevertheless, the introduction of the IPSI mechanism, together with other adjustments made after considering the market feedback, such as lowering the market capitalisation requirement for listing and modifying the requirements for the minimum R&D expenditure ratio, demonstrated the Exchange’s efforts in promoting the feasibility of the new listing regime without compromising the protection offered to investors.
This new route to the market is expected to support some of the most innovative and progressive companies of the future. Since the listing reforms implemented by the Exchange in 2018, Hong Kong has made a great leap forward in catching up with the international capital market’s development progress of regulatory framework to accommodate the ever-changing market needs. The introduction of such series of rules and regulatory frameworks, including this new Specialist Technology chapter, will greatly enhance Hong Kong’s competitiveness as a fundraising market in Asia, and Hong Kong would be able to make an even greater use of its connectivity with Mainland China.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
1 Conclusions, p. 6
2 Conclusions, pp. 6 and 7
3 Conclusions, p. 12
4 Conclusions, pp. V-2 to V-6, paragraph 7 of the Guidance Letter
5 Conclusions, pp. 10 to 11
6 Conclusions, pp. 11 and V-7, paragraph 10 of the Guidance Letter
7 Conclusions, p. V-7, paragraph 11 of the Guidance Letter
8 Conclusions, p. V-7, paragraphs 12 and 13 of the Guidance Letter
9 Conclusions, pp. 14 and V-8, paragraphs 16 and 17 of the Guidance Letter
10 Companies that have achieved meaningful commercialisation of their Specialist Technology Products and achieved a minimum revenue of HK$250 million in the most recent audited financial year, and are also expected to demonstrate year-on-year growth of revenue from the Specialist Technology business.
11 Conclusions, pp. 17-18
12 Conclusions, pp. 18-19
13 Conclusions, pp. 1, 22 to 29
14 Conclusions, pp. 29 to 31
15 Conclusions, pp. 2 and 39 to 42
16 Conclusions, pp. 42 to 43
17 Conclusions, pp. 45 to 62
18 Conclusions, pp. 58-59
19 Conclusions, p. 60
20 Conclusions, pp. 75-84
21 Conclusions, pp. 82 to 84
22 Conclusions, pp. 84 to 88
23 Conclusions, p. 90
24 Conclusions, pp. 63 to 70
25 Conclusions, pp. 93 to 100
26 Key personnel responsible for the STC’s technical operations and/or the R&D of its STP(s) (including the head and the key personnel of its R&D department) whose expertise is primarily relied upon by the company for the development of its STP(s), and the lead developer(s) of the core technologies in relation to the STP(s). In determining whether a person should be designated as a Key Technical and R&D Personnel, an applicant should consider factors including the shareholding of such personnel, his/her remuneration relative to other R&D staff, and his/her seniority.
Introduction
On 20 February 2023, the Securities and Futures Commission (the “SFC”) issued a consultation paper on proposed regulatory requirements for virtual asset trading platform operators licensed by the SFC (the “Consultation Paper”). The Consultation Paper is a follow-up consultation of the Anti-Money Laundering and Counter-Terrorist Financing (Amendment) Bill 2022 (the “Bill”) which was gazetted in June 2022 and passed in December on the same year, introducing a new licensing regime for virtual asset service providers (the “AMLO VASP regime”) (see our news update on the Bill). The Consultation Paper further explains and sets out the proposed changes in regulatory requirements and proposed transitional arrangements under the regime for centralised virtual asset trading platforms (the “VA Trading Platforms”) trading non-security tokens coming into effect on 1 June 2023. Industry and public proposals are invited on the applicable regulatory approach. The public comment period ends on 31 March 2023.
…
Key Regulatory requirements
A. Key proposed regulatory requirements for licensed VA Trading Platforms
Upon the commencement of the AMLO VASP regime, it is proposed that VA Trading Platforms licensed by the SFC shall comply with the Guidelines for Virtual Asset Trading Platform Operators (“VATP Guidelines”). Such VATP Guidelines will be based on the existing regulatory requirements applicable to SFO-licensed platform operators (“LPOs”), and particularly, the Terms and Conditions for VA Trading Platform Operators (VATP Terms and Conditions).
The proposed regulatory requirements under VATP Guidelines cover various aspects and areas, such as fit and proper requirement, compliance with the general principles, financial soundness, operations, prevention of market manipulative and abusive activities, dealing with clients, custody of client assets, management, supervision and internal control, cybersecurity, conflict of interests, record keeping, auditors, ongoing report obligations.1 The SFC also emphasise the “same business, same risks, same rules” approach, which requires VA providers of the same risk level to be subjected to the same obligations but adapted to address the specific risks of virtual assets (“VA(s)”), aiming to provide investors with more protection under the backdrop of the collapse of the Luna token and Terra stablecoin.2 After the AMLO VASP regime comes into effect, the VATP Terms and Conditions will be superseded. All platform operators, whether licensed under the SFO and/or the Anti-money Laundering Ordinance (“AMLO”), will be subject to the VATP Guidelines.
B. Dual Licences
Upon the commencement of the AMLO VASP regime, the SFC will regulate the trading of security tokens by VA Trading Platforms under the existing SFO regime and regulate the trading of non-security tokens by VA Trading Platforms under the AMLO VASP regime.
Given that a VA may evolve from a non-security token to a security token (or vice versa), VA Trading Platforms (together with their proposed responsible officers and licensed representatives) should apply for approvals under both the existing SFO regime and the AMLO VASP regime and become dually licensed and approved.
C. Proposal to allow retail access to licensed VA Trading Platforms3
When the existing SFO regime was introduced in 2018, it was more prudent to restrict SFO-licensed VA Trading Platforms to serve professional investors only. In this regard, the SFC notes the public’s diverse views on whether retail investors should be allowed access to the services of licensed VA Trading Platforms.
In January 2022, the SFC allowed for the first-time retail investors to access a limited suite of regulated virtual asset-related derivative products traded on conventional exchanges. Later in October 2022, the SFC put in place a regime for authorising virtual asset futures exchange-traded funds. Retail investors, thus, since then have indirect access to Vas through regulated products in Hong Kong (see our news update for details).
Since more global financial institutions and service providers have entered the market, the SFC proposes to allow all types of investors, including retail investors, to access trading services of “Eligible large-cap VAs” offered by LPOs, provided that the VAs are included in at least two “acceptable indices” issued by at least two independent index providers. LPOs should also take into account other general token admission criteria including the market capitalization, trading volume, security of protocols, and internal compliance of the VAs before admitting them for trading.4
D. Consultations Questions5
Some of the key questions set out by the SFC for industry and public feedback, together with their corresponding views, are extracted as follows:
| No. | Key Consultations Questions | Views of the SFC |
| 1. | Do you agree that LPOs should be allowed to provide their services to retail investors, subject to the robust investor protection measures proposed? |
|
| 2. | Do you have any comments on the proposals regarding the general token admission criteria and specific token admission criteria? |
|
| 3. | What other requirements do you think should be implemented from an investor protection perspective if the SFC is minded to allow retail access to license VA trading platforms? |
|
| 4. | Do you have any comments on the proposals to allow a combination of third-party insurance and funds set aside by the LPO or a corporation within its same group of companies? Do you propose other options? |
|
Key measures of the transitional arrangements and implementation details for the AMLO VASP regime
E. Eligibility for the transitional arrangements
To be eligible for the transitional arrangements, a VA Trading Platform must be pre-existing, i.e., in operation in Hong Kong prior to 1 June 2023 and with meaningful and substantial presence. To determine the same, the SFC will take to account the following non-exhaustive factors including (a) whether it is incorporated in Hong Kong; (b) whether it has a physical office in Hong Kong; and (c) whether its Hong Kong staffs have central management and control over the VA Trading Platform.10
F. Key dates and implementation details of the transitional arrangements
For pre-existing VA Trading Platform which intends to apply for a licence, it must submit a fully completed licence applicable online under the AMLO VASP regime between 1 June 2023 and 29 February 2024. It will be asked to confirm and demonstrate that it has been operating a VA Trading Platform in Hong Kong immediately before 1 June 2023 and it will comply with the applicable regulatory requirements.
For pre-existing VA Trading Platform that does not intend to apply for a licence, it should start preparing to close down its business in Hong Kong in an orderly manner. While the strict deadline for these platforms to close down is 31 May 2024, the SFC expects them to cease any active marketing of their services in Hong Kong.
By 1 June 2024, all VA Trading Platforms in Hong Kong must have been either deemed to be licensed or granted a licence by the SFC. The SFC will take immediate action against any unlicensed VA Trading Platforms.
Analysis and takeaways
Subsequent to the Government’s Policy Statement on its plan and approach for the VASP regime (see our news update), this Consultation Paper is a timely attempt to translate visions into practices and denotes a significant milestone in the global regulatory regime over VAs. SFC is committed to taking the forefront role in expanding the retail market for VAs in Hong Kong by implementing legal safeguards for different stakeholders. It helps retail investors acclimate to the volatile market and enables retail investors’ access to regulated trading platform under a protective and effective system. This Consultation Paper, together with the previously unveiled regulations, foster a new wave of market opportunities and capital investments while modernising Hong Kong’s financial market, which aligns with the global trajectory of further utilising VAs.
As such, we welcome the SFC’s proposals and would be happy our perspectives on the Consultation Paper for facilitating local VA services. We would also like to take the opportunity to encourage you to have discussion with us and share your views on this topic.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
1 Please see p.10-11 of the Consultation Paper for the full list and corresponding explanation of the existing regulatory requirements.
2 P.7 of the Consultation Paper.
3 P.12 of the Consultation Paper.
4 P.16 of the Consultation Paper.
5 P.12-23 of the Consultation Paper.
6 Please see p.15 of the Consultation Paper for the full list of general non-exhaustive token admission criteria suggested by the SFC.
7 Please see p.16 of the Consultation Paper for the specific token admission criteria, particularly on requirements for an “acceptable index”.
8 Please see p.17 of the Consultation Paper for the specific areas of due diligence required.
9 Please see p.17-18 of the Consultation Paper for the non-exhaustive list of disclosure obligations.
10 Please see p.24 of the Consultation Paper for full list of non-exhaustive factors in determining whether the firm has a meaningful and substantial presence.
On 31 January 2023, the Hong Kong Monetary Authority (the “HKMA”) published a Conclusion of Discussion Paper on Crypto-assets and Stablecoins (the “Consultation Conclusion Paper”). This followed its earlier consultation by way of its discussion paper published on 12 January 2022 on the relevant proposals (the “Discussion Paper”) (see our news update on the Discussion Paper). Taking into account the feedback received, the HKMA will further proceed to bringing certain activities relating to stablecoins into the regulatory regime. The target implementation date of the regime will be by 2023/24 after considering various issues such as the volatility and risks of the stablecoins as well as the need to adopt the latest international recommendations and align Hong Kong’s regulatory regime in stablecoins with those in other major jurisdictions. 1
…
The Key Parameters of the Regulatory Regime
A. What to regulate
Having considered the responses received, the HKMA suggested that key activities relating to stablecoins will be subject to a mandatory licensing regime. The HKMA will take a risk-based approach by giving priority to regulating stablecoins that purport to reference to one or more fiat currencies at this stage. The focus of the regulation would be on the purported reference of a stablecoin regardless of their respective underlying stabilisation mechanism. That is, stablecoins that purports to reference to fiat currencies through algorithms or arbitrage mechanisms will be regulated. 2
Regarding the regime, the HKMA proposes that flexibility should be adopted to enable the authority to declare other stablecoin structure(s) for regulation under the regime in the future. The HKMA also acknowledges the need to exclude certain arrangements from the definition of stablecoins for certain reasons, for instance, the stablecoins which are already being subject to another financial regulatory regime. 3 As this issue has not been finalised yet, further analysis and additional consultation will be required for more information on decision making. While considering the regulation of other crypto-assets, the latest market situation and international discussion will be taken into account by the HKMA for future implementation.
B. Key activities to be regulated
As mentioned above, the key activities relating to an in-scope stablecoin will be regulated under the mandatory licensing regime, for instance: 4
| Key activities | |
| Governance | Establishment and maintenance of the rules governing an in-scope stablecoin arrangement |
| Issuance | Issuing, creation or destroying of in-scope stablecoins |
| Stabilisation | Stabilisation and reserve management arrangements of an in-scope stablecoin (whether or not such arrangements are provided by the issuer) |
| Wallets | Provision of services that allow the storage of users’ cryptographic keys which enable access to the users’ holdings of an in-scope stablecoin and the management of such stablecoins |
It is noted that these activities might overlap and/or have interface with other financial regulatory regimes in Hong Kong such as the licensing regime for VASPs to be administered by the SFC. 5
For the other stablecoin-related activities that are not listed above, they may not be included in the proposed regulatory scope at this stage. Nevertheless, in order to scope in new types of regulated activities in the future, the HKMA aims to apply appropriate flexibility in the regulatory regime. This would also prepare the authority to tackle any risks associated with the unregulated stablecoin activities when such risks become concerning from a monetary and financial stability angle. 6
C. Entities that will require a license from HKMA
After the consultation, the HKMA concludes that the following types of entities will require a license from the authority:
Entities that:
D. Key regulatory principles
When formulating the regulatory requirements, the HKMA will adopt a risk-based approach. To deal with the issue where there are multiple activities that may take place regarding a stablecoin arrangement, the authority tends to customise the appropriate requirements for each type of activities. 8
For the time being, the HKMA has provided the three principles of the regulatory regime: 9
| Principle | |
| Comprehensive regulatory framework |
The regulatory framework should cover a broad range of issues including but not limited to:
|
| Full backing and redemption at par |
|
| Principle business restriction |
|
Authorised Institutions (“AI”) and Non-AI Issuers of Stablecoins
Following the consultation and considering the international standards, a risk-based, “same risk, same regulation” approach will be adopted by the HKMA, where the authority is of the view that both AIs and non-AIs should be allowed to issue stablecoins provided that the licensing and regulatory requirements could be satisfied. On the other hand, the final regulatory requirements applicable to the AI and non-AI will be calibrated according to risks of each type of issuers presents to the financial system. 10
Analysis and Takeaways
The significant potential in the use of crypto-assets in Hong Kong raises the need of investor protection and the regulation of the new financial instrument. With the introduction of the stablecoin and its regulatory parameters, the financial stability risks that may be posed by the stablecoin can be addressed for a safer crypto-asset ecosystem in Hong Kong. The proposed regulatory regime shows the initiative and determination of the regulators in Hong Kong to ensure monetary and financial stability amidst technological advancement.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
1 Consultation Conclusion Paper p.21
2 Consultation Conclusion Paper p.14
3 Consultation Conclusion Paper p.14
4 Consultation Conclusion Paper p.15-16
5 Consultation Conclusion Paper p.5
6 Consultation Conclusion Paper p.16
7 Consultation Conclusion Paper p.4
8 Consultation Conclusion Paper pp.17
9 Consultation Conclusion Paper pp.17-18
10 Consultation Conclusion Paper pp.22-23
Introduction
On 31 October 2022, the Securities and Futures Commission of Hong Kong (“SFC”) issued a circular regarding virtual assets (“VA”) 1futures exchange traded funds (the “Circular”). The Circular sets out the requirements under which the SFC may consider authorising exchange-traded funds (“ETFs”) that obtain exposure to VAs primarily through futures contracts (“VA Futures ETFs”) for public offering in Hong Kong under sections 104 and 105 of the Securities and Futures Ordinance (“SFO”).
As noted in the Circular, the SFC is prepared to accept applications for authorisation of VA Futures ETFs. The SFC will keep in view and closely monitor the development of the VA market and its regulatory landscape regarding the appropriateness of authorisation of ETFs that invest directly in spot VAs.
The Circular was published soon after the Hong Kong government issued a policy statement on the development of VA (the “Policy Statement”) relating to, among others, non-fungible token issuance, green bond tokenisation, and e-HKD (see our news update on the Policy Statement here).

Key Authorisation Requirements for VA Futures ETFs
General Requirements
VA Futures ETFs seeking SFC authorisation to enable the public offering of interests in Hong Kong should meet the applicable requirements in the Overarching Principles Section and the Code on Unit Trusts and Mutual Funds in the SFC Handbook for Unit Trusts and Mutual Funds, Investment-Linked Assurance Schemes and Unlisted Structured Investment Products.
Additional Requirements
VA Futures ETFs which seek SFC authorisation for public offering in Hong Kong shall meet additional requirements set ou the Circular as summarised below:
Management Companies
The management company of a VA Futures ETF must have (i) a good track record of regulatory compliance; and (ii) demonstrate at least three years of proven track record in managing ETFs. The SFC will also consider relevant experience in managing the same or similar type of products from the group of companies to which the management company belongs. The SFC may also consider accepting delegation or co-management of a VA Futures ETF, provided that the management company in the case of delegation or at least one of the management companies in the case of co-management complies with the relevant requirements.
Eligible Futures
Only VA futures traded on conventional regulated futures exchanges are allowed, subject to the relevant management company demonstrating (i) the relevant VA futures have adequate liquidity for the operation of the VA Futures ETF; and (ii) the roll costs of the relevant VA futures contracts are manageable which includes how roll costs will be managed. Initially, only Bitcoin futures and Ether futures traded on the Chicago Mercantile Exchange will be permitted. The SFC shall consider expanding the scope of eligible VA futures markets in the future as appropriate.
Investment Strategy
The management company of a VA Futures ETF is expected to adopt an active investment strategy to allow flexibility in portfolio composition (such as diversification of futures positions with multiple expiry dates), rolling strategy and handling of any market disruption events. The net derivative exposure of a VA Futures ETF shall not exceed 100% of the total net asset value of the relevant ETF.
Disclosure
The product key facts statement of a VA Futures ETF should contain upfront disclosure of the investment objective and key risks associated with investment in VA futures contracts, including (1) risks concerning potentially large roll costs of VA futures; and (2) operational risks, such as margin risk and risk associated with mandatory measures imposed by relevant parties.
Distribution
Since VA Futures ETFs are derivative products and VA-related products, intermediaries are subject to the applicable requirements under the Code of Conduct for Persons Licensed by or Registered with the Securities and Futures Commission (the “Code of Conduct”) and related guidelines including the Joint Circular on Intermediaries’ Virtual Asset-Related Activities (the “Joint Circular”) issued by the SFC and the Hong Kong Monetary Authority in January 2022 (see our news update on the Joint Circular here). In particular, intermediaries shall comply with the existing conduct requirements for derivative products as set out under paragraphs 5.1A and 5.3 of the Code of Conduct, as well as the VA-knowledge test requirement.
Investor Education
The management company of a VA Futures ETF should carry out extensive investor education before launching the VA Futures ETF in Hong Kong.
Please contact our Partner Mr. Rodney Teoh and associate Mr. Calvin KW Lo for any enquiries or further information. Rodney would like to thank Ms. Adrienne Leung (Intern) for her contribution to this news update.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
1 VA refers to digital representations of value, which may be in the form of digital tokens, such as utility tokens, stablecoins, security-backed tokens or asset-backed tokens, or any other virtual commodities, crypto assets or other assets of the same nature, irrespective of whether or not they amount to “securities” or “futures contracts” as defined under the SFO but excludes digital representations of fiat currencies issued by central banks.
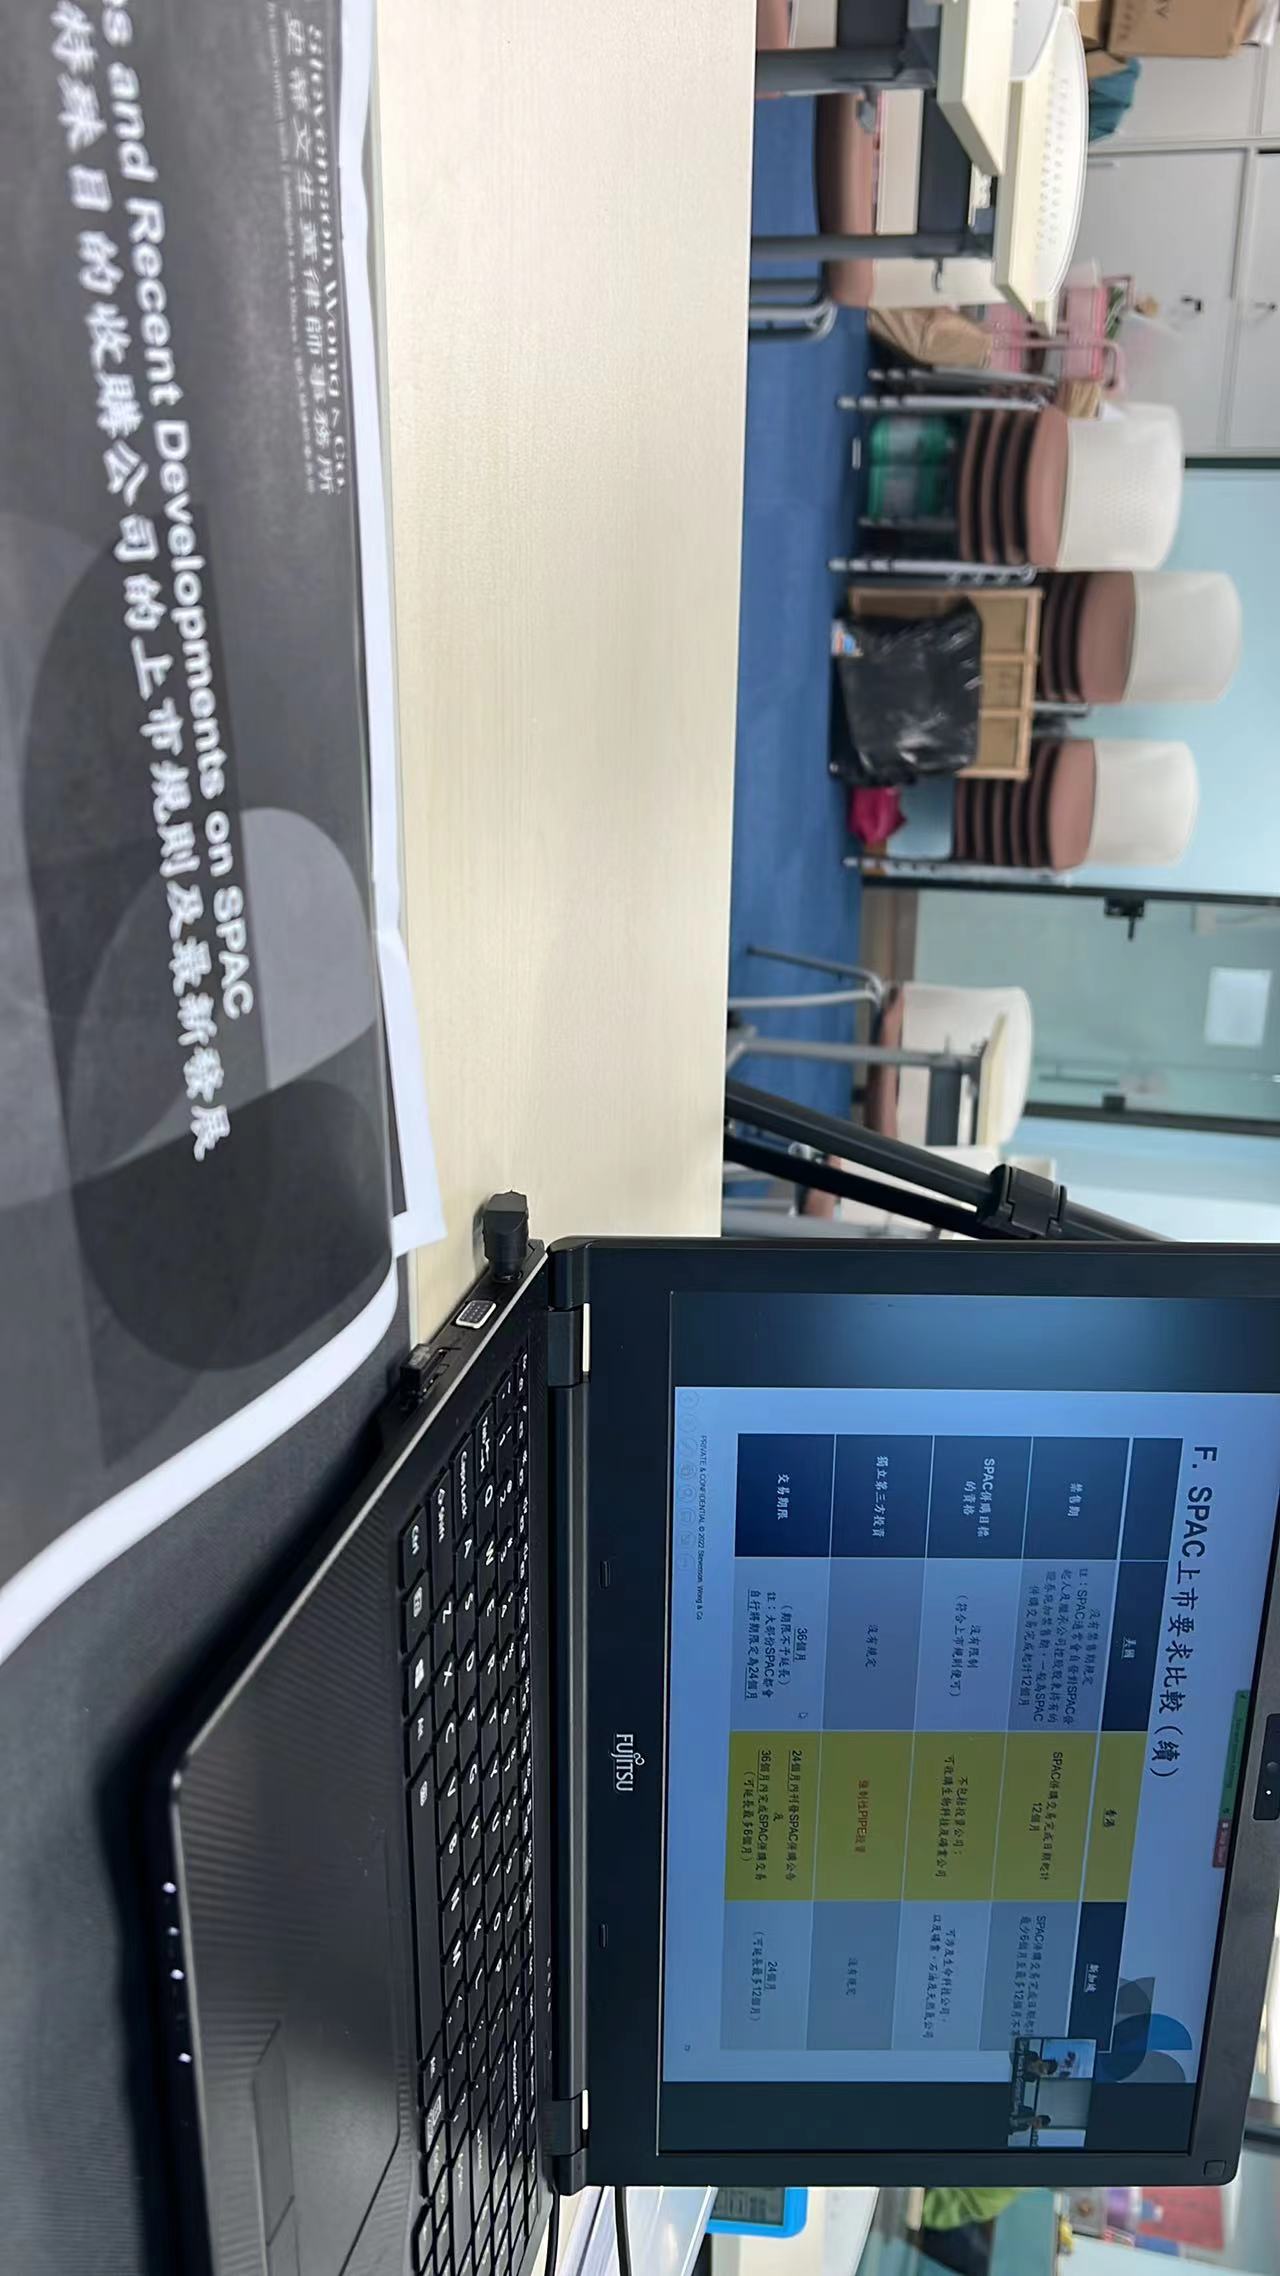
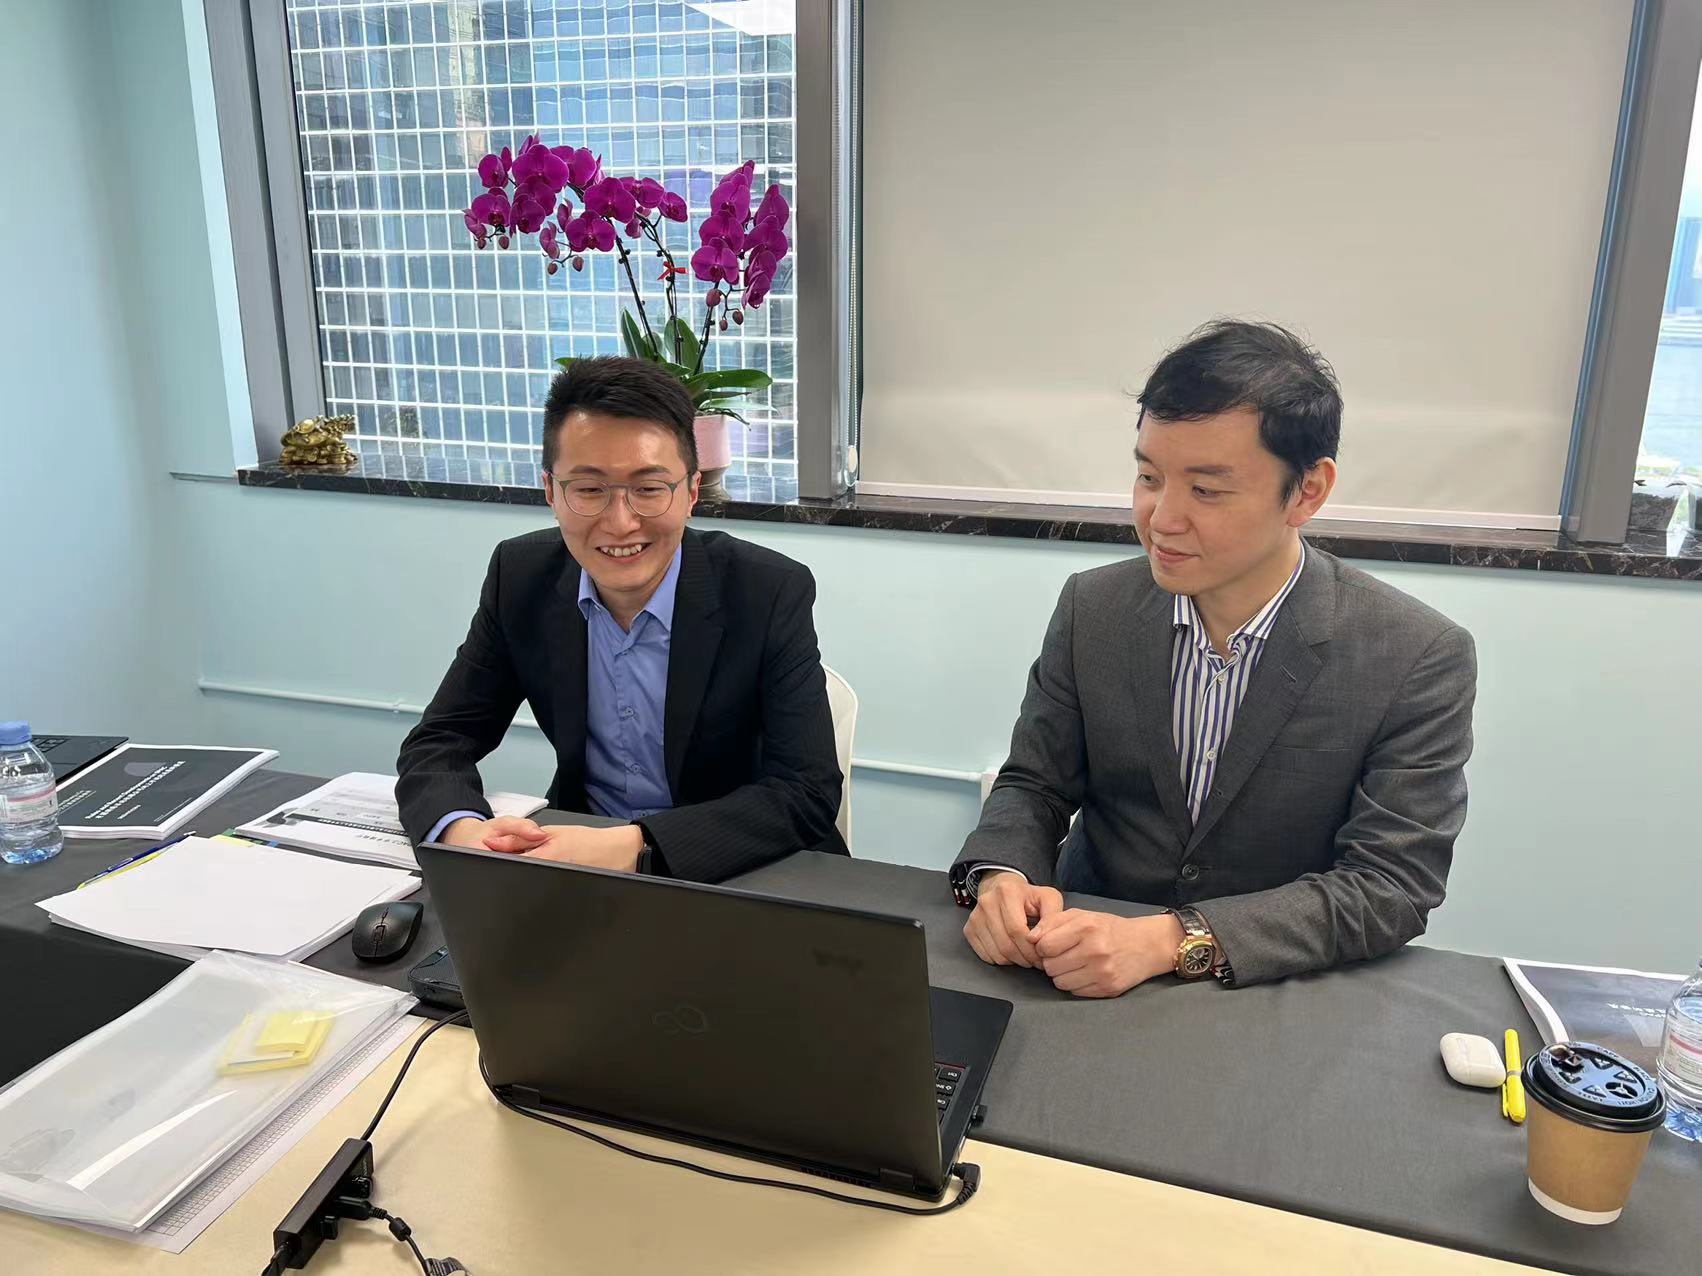
On 30 August 2022, our Partner Gordon Tsang and Associate Gary Kwok were invited by LexOmnibus to give a CPD course on the topic “Rules and Recent Developments on Special Purpose Acquisition Companies”.
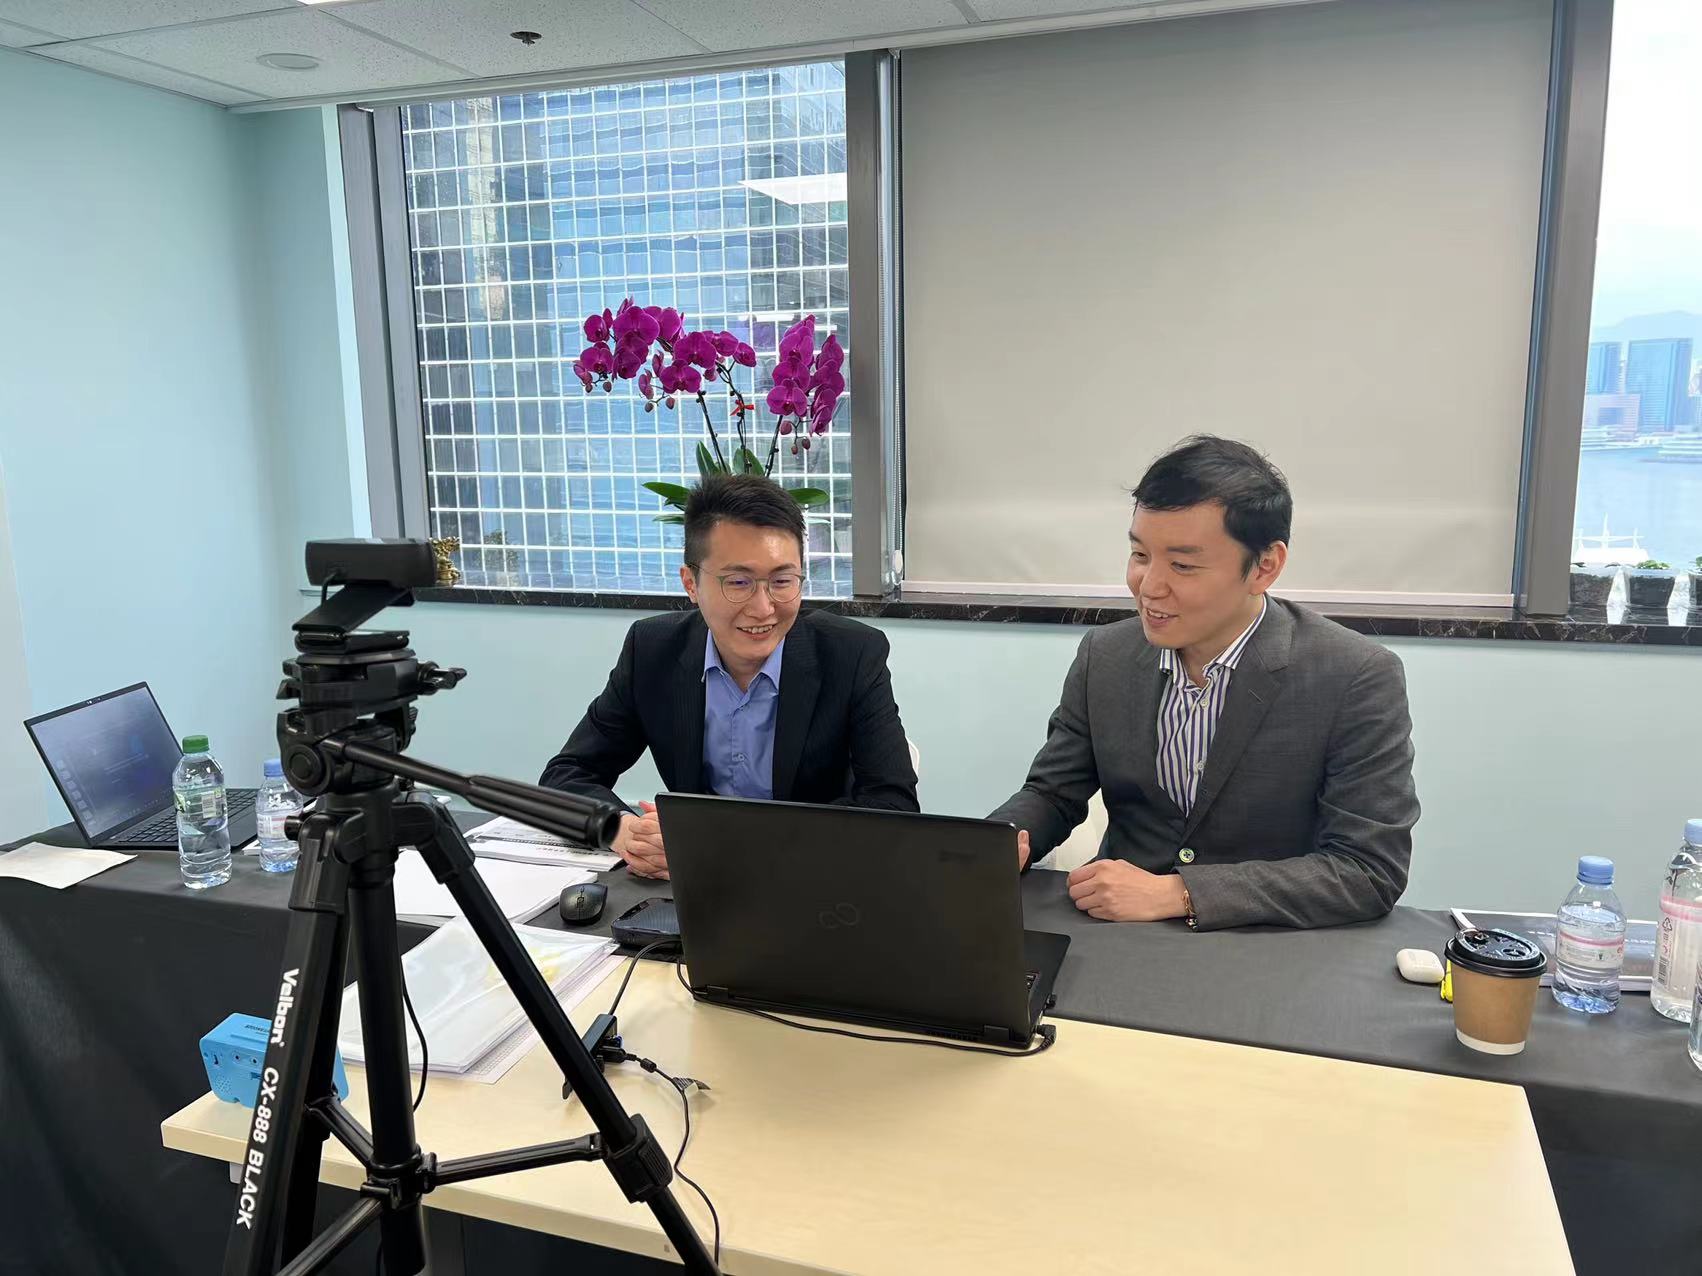
Special Purpose Acquisition Companies (“SPAC”) is a new listing regime in Hong Kong. It allows SPAC promoters to source target companies with potential in listing for merger and acquisition to acquire a listing status through an unconventional initial offering.
During the 3-hour webinar, Gordon and Gary gave an in-depth introduction to the listing requirements of traditional IPOs and SPAC, as well as the De-SPAC Transaction and De-Listing Mechanism of SPAC. They also compared the SPAC listing requirements between the U.S., Hong Kong and Singapore. Lastly, they concluded the course by discussing the advantage and potential risks of SPAC Listing in Hong Kong.
Due to the pandemic, the course was delivered via a webinar, and positive feedback was received from the audience.
Please contact Partner Gordon Tsang for any enquiries or further information about this course.