News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
Stevenson, Wong & Co. Partner Ms. Heidi Chui has been appointed by the Medical Council of Hong Kong, on the nomination of the Council of the Law Society of Hong Kong, to be a Lay Assessor with effect from 3 October 2018 for a term of three years.
Lay Assessor is appointed under section 20BB of the Medical Registration Ordinance. Assessors may be appointed as members of the Preliminary Investigation Committee, the Inquiry Panel and/or the Health Committee of the Council.
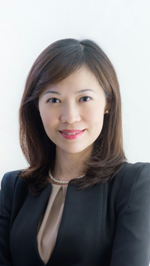
Ms. Heidi Chui is an Arbitrator (on the panel list of the Law Society of Hong Kong), Fellow of the Chartered Institute of Arbitrators (U.K.) and an Accredited General Mediator with both the Hong Kong International Arbitration Centre and the Law Society of Hong Kong. She is also a member of the Arbitration Committee of The Law Society of Hong Kong and a China Appointed Attesting Officer. She has been appointed as an Expert on the professional Committee on Real Estate Arbitration of China Academy of Arbitration Law, a Practising Solicitor Member of the Solicitors Disciplinary Tribunal Panel and a member of Disciplinary Panel A of the Hong Kong Institute of Certified Public Accountants.
Please contact Ms. Heidi Chui for any enquiries or further information.
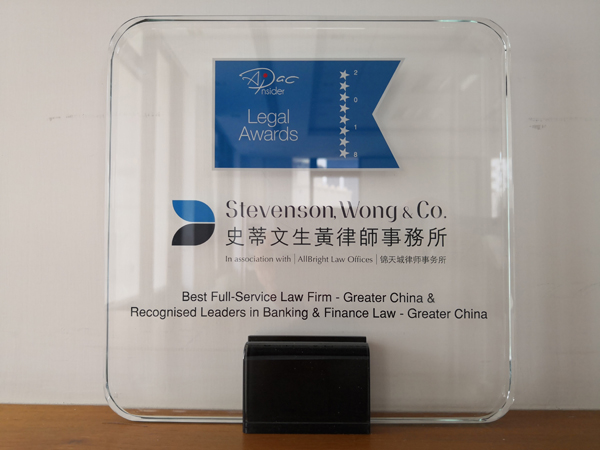
We are delighted to announce that Stevenson, Wong & Co. has been recognized as “Best Full-Service Law Firm – Greater China” and “Recognised Leaders at Banking & Finance Law – Greater China” at the APAC Insider 2018 Legal Awards. Each award nominee is carefully examined, with the judging panel taking into account their performance over the past 12 months to ensure that only the most deserving firms are handed one of the trophies.
About APAC Insider
APAC Insider is a magazine in the United Kingdom focusing on business strategy and analysis in the Asia-Pacific region.
Please contact Mr. Willy Cheng for any enquiries or further information.
Stevenson, Wong & Co. is delighted to announce that our Partner Ms. Heidi Chui has been appointed by The Secretary for Security of the Hong Kong Special Administrative Region as an adjudicator of the Immigration Tribunal with effect from 1 October 2018 for a term of two years.
The Immigration Tribunal was established in 1980 under the Immigration Ordinance, Cap. 115, to deal with appeals lodged under the Immigration Ordinance.
Ms. Heidi Chui is an Arbitrator (on the panel list of the Law Society of Hong Kong), Fellow of the Chartered Institute of Arbitrators (U.K.) and an Accredited General Mediator with both the Hong Kong International Arbitration Centre and the Law Society of Hong Kong. She is also a member of the Arbitration Committee of The Law Society of Hong Kong and a China Appointed Attesting Officer. She has been appointed as an Expert on the professional Committee on Real Estate Arbitration of China Academy of Arbitration Law, a Practising Solicitor Member of the Solicitors Disciplinary Tribunal Panel and a member of Disciplinary Panel A of the Hong Kong Institute of Certified Public Accountants.
Please contact Ms. Heidi Chui for any enquiries or further information.
In the newly published edition of Asialaw Profiles 2019, Stevenson, Wong & Co. is delighted to be recognized as an Outstanding Firm in Regulatory work, a Highly Recommended Firm in 5 practice areas, a Recommended Firm in 7 practice areas and an Active Firm in Private Client. Our Partners Ms. Heidi Chui has been identified as a leading practitioner in both Dispute Resolution and Banking and Finance, Mr. Stephen Wong has been identified as a leading practitioner in Regulatory and Dispute resolution, and Mr. Rodney Teoh has been identified as a leading practitioner in Capital markets and Corporate and M&A.
“Outstanding Firm” for:

“Highly Recommended Firm” for the following practice areas:-

“Recommended Firm” for the following practice areas:-

“Active Firm” for:
Please contact Mr. Willy Cheng, Mr. Hank Lo, Ms. Catherine Por, Ms. Heidi Chui, Mr. Stephen Wong or Mr. Rodney Teoh for any enquiries or further information.
Introduction
In recent years, significant demands for shell companies for backdoor listings can be seen as a factor to explain the substantial increase in the value attached to the listing status on the Hong Kong stock exchange. The Stock Exchange of Hong Kong Limited (the “Exchange”) noted an increase in market activities related to the creation and the trading of shell companies involving not only listings of new applicants whose sizes and prospects do not appear to justify the cost or purpose associated with a public listing, but also listed issuers with failed business attempting to maintain their listing status by establishing new businesses that have a lower threshold for entry and/or can be conveniently established and discontinued without considerable costs.
While shell activities are limited to a small segment of the market, the Exchange considers that these activities invite speculative trading and can lead to opportunities for market manipulation and unnecessary volatility, which may compromise the reputation and overall quality of the Hong Kong stock market. In response to this, the Exchange published a consultation paper on 29 June 2018 to codify certain guidance letters provisions into the Main Board Listing Rules (the “MBLR”) and the GEM Listing Rules (the “GLR”) (collectively, the “Listing Rules”) as well as to impose further requirements. A summary of such proposed amendments relating to backdoor listing is set out below.
Proposed amendments to the Listing Rules
| Principle based test |
(a) the size of transaction relative to the size of the issuer; (b) the quality of the business to be acquired – whether it can meet the trading record requirements for listings, or whether it is unsuitable for listing (e.g. an early stage exploration company); (c) the nature and scale of the issuer’s business before the acquisition (e.g. whether it is a listed shell); (d) any fundamental change in the issuer’s principal business (e.g. the existing business would be discontinued or very immaterial to the enlarged group’s operations after the acquisition); (e) other events and transactions (historical, proposed or intended) which, together with the acquisition, form a series of arrangements to circumvent the RTO Rules (e.g. a disposal of the issuer’s original business simultaneously with a very substantial acquisition); and (f) any issue of restricted convertible securities to the vendor which would provide it with de facto control of the issuer.
(a) the criterion of “issue of restricted convertible securities” will be extended to include any change in control or de facto control of the issuer; (b) the “series of arrangements” criterion will be clarified: i. to mean any transactions and/or arrangements that are in reasonable proximity (normally within a period of three years) or otherwise related; and ii. that it is no longer required for the proposed (last) transaction to be an acquisition to trigger the Listing Rules in relation to RTOs. |
| Bright line tests and restriction on material disposals |
(a) an acquisition or a series of acquisitions of assets constituting a very substantial acquisition where there is or which will result in a change in control (as defined in the Codes on Takeovers and Mergers and Share Buy-backs (the “Takeovers Code”)) of the listed issuer; or (b) very substantial acquisition(s) of assets (individually or in aggregate) from the new controlling shareholder and/or any of its associates within 24 months following a change in control (as defined in the Takeovers Code).
|
| Extreme transactions |
(a) the issuer has been operating a principal business with substantial size which will continue after the transaction (as a general guidance, this may include a principal business with annual revenue or total asset value of HK$1 billion or more, excluding any revenue or assets not attributable to the issuer’s original principal business); or (b) the listed issuer has been under control of a large business enterprise for a long period of time (normally not less than three years), and the transaction forms part of a business restructuring of the group and would not result in a change in control.
|
| Additional requirements applicable to RTOs and extreme transactions |
(a) Both the acquisition target(s) and the enlarged group must be suitable for listing (pursuant to MBLR 8.04 / GLR 11.06). (b) The acquisition target(s) must also meet MBLR 8.05 (or 8.05A or 8.05B) / GLR 11.12A (or GLR 11.14)). (c) In case an issuer has failed to comply with MBLR 13.24 / GLR 17.26) regarding its sufficient operations, each of the acquisition target(s) and the enlarged group must meet all the new listing requirements of Chapter 8 MBLR / Chapter 11 GLR.
|
| Backdoor listings via large scale issue of securities |
|
Implications
The consultation paper and its proposals represent a policy response by the Exchange to the prevailing trend of creation and trading of shell companies in the Hong Kong stock markets. If the proposed amendments are in place, taking into account the proposed extended aggregation period and track record period, together with the proposed additional regulatory requirements and restrictions, it is expected that the costs for and the risks associating with backdoor listings will increase. The proposed regime is expected to change the course of cost-and-benefit analyses of investors and listed companies alike.
This newsletter is for information purposes only. Its content does not constitute legal advice, and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage.
Please contact Mr. Hank Lo or Mr. Rodney Teoh for any enquiries or further information.
(中文)
不当销售金融产品申索 银行再胜一仗
Shine Grace Investment Ltd
v.
Citibank, N.A and Another
[2018] HKCU 2560
香港高等法庭原讼法庭公布了关于累计股票期权合约 (accumulator contract)的不当销售 (mis-selling)纠纷的Shine Grace Investment Ltd v. Citibank, N.A and Another [2018] HKCU 2560案件判决。本案的原告Shine Grace Investment Ltd.(下称「Shine Grace」)为已故慈善家陈树渠的妻子陈丽玲(下称「陈女士」)的名下公司,而被告为美资银行Citibank(下称「银行」)。
本案的核心焦点在于法庭如何诠释此份累计股票期权合约的条款,包括银行是否有法律责任为客户提供建议,及法庭为何认为香港证监会(下称「证监会」)操守准则(code of conduct)没有并入本案争议合约。另外,在事实层面,当事人在投资决策上的精明、自信和不耐心的性格特点,也成为法官判银行胜诉的一大考量。
案件背景:
陈女士于2007年10月去世前透过其名下公司,包括本案主要原告Shine Grace,与银行签订9张累计股票期权合约。在陈女士去世后,由陈女士儿女继承并掌管的Shine Grace控告银行,称正是由于银行当年的误导,才使得陈女士签订了的上述9张累计股票期权合约。银行在签订9份争议合约时,违反银行应当向陈女士提供合适建议的法律责任,以及违反应当提供合理、公平、准确和诚实建议和不得误导的责任,因此基于银行对陈女士造成的不当影响(undue influence)或压制行为(oppressive conduct),入禀向银行索偿约港币5亿元。
法庭在法律基础和事实基础上驳回了原告以上请求。
判决分析:
1. 银行是否有法律责任,为客户提供合适、合理、准确及诚实的建议?
法庭认为,单凭银行与客户间存在的往来关系并不证明银行有提供建议的法律责任。法庭在本案中援引了先例Chang Pui Yin & Ors v Bank of Singapore Limited [2017] 4 HKLRD 458, 在先例中,Lam VP法官认为,在法律层面,银行在其业务往来中为客户提供建议并不一定会将此行为认定为银行的法律责任。在每一个个案中,确定银行是否须承担为客户提供建议的法律责任,应当视乎于个案与当事人每一个方面的客观事实。
在先例中法官判断银行是否有上述法律责任的标准为:须考量银行的服务合约和风险披露声明以及其他相关的事实背景,来确定银行在销售或管理金融产品时是否对客户负有法律责任。
在本案(和很多关于不当销售的案件)中,银行的合约都包含不依赖条款(non-reliance clause)[1],约定客户必须根据自身判断做投资决定。
在本案中,法庭基于先例采纳合约不容反悔原则(principle of contractual estoppel)支持了银行的抗辩,认定银行合约内的不依赖条款卸除了银行为客户提供建议的法律责任,以及即使提供了建议也无须对客户的投资决定承担任何法律责任。
另一方面,法庭在事实考量上,认为陈女士是一位精明、自信、意志坚定但没有耐心的投资者。法庭从陈女士与银行职员的电话记录中发现,陈女士已有超过30年的股票市场投资经验,并且不只一次要求银行职员不得干预她的投资决策。并且,证据也证明陈女士过于自信和没有耐心来寻求或听取银行适当的投资建议,尤其是对于市场变化的投资风险、按市值计价以及追加保证金通知等建议。
因此,法庭基于对事实的考量,即陈女士在投资决策时的个性和行为,以及在本案争议的累计股票期权合约决策上未向银行征求过相关建议,法庭认为银行无须承担为陈女士提供适当建议的法律责任,同样,针对失实陈述的请求,法庭以事实证据不足而将其驳回。
2. 香港证监会的操守准则是否并入本合约?
原告Shine Grace称证监会的操守准则(code of conduct)已明确并入本合约,因此根据证监会的操守准则,银行应当负责、小心且谨慎地为客户提供适当建议或确保客户明白交易的性质和风险的责任。
法庭驳回了原告之主张,称若Shine Grace有意将证监会的行为准则并入其与银行的合约中,要求银行承担上述为客户提供建议的责任,应当将该准则清楚明确地订立在合约条款中,但在该争议合约中,并未发现存在上述条款。其次,基于银行角度,并入以上条款既不存在商业价值,也没有实际意义,换言之,银行不存在并入与合约相矛盾条款的订约意图。再者,证监会的行为准则是非强制性法律。
法庭驳回Shine Grace之主张,认为即使银行在与客户的业务往来存在向客户提供建议的情形,但法庭基于对合约的解释,认为证监会的操守准则与本合约以及银行的订约目的相悖,银行在订约时不存在承担为客户提供建议的法律责任的意思表示。
案件评论:
虽然本案法庭判银行胜诉,但银行在业务操作中仍应注意谨慎订立内容和提供合适建议。
首先,银行等金融机构应当注意近年证监会发布的规定[2],包括要求金融机构在作出建议或招揽行为时为客户提供合理适当建议的条款,即该金融产品须基于客户的合理需求,例如客户的经济情况、投资经验以及投资取向等。
其次,即使该客户在投资中不会经常性采纳银行建议,例如投资者非常坚持自己看法,但银行也当履行向该类客户提出必要建议。
法庭虽然未采纳原告提出的证监会操守准则,但有关此准则的争议已出现在多个先例中,如DBS Bank(Hong Kong) Limited v Sit Pan Jit(FAMV 45/2016), Chang Pui Yin & Ors v Bank of Singapore [2017] 4 HKLRD 458等,该准则已日益成为银行与客户订立合约的重要考量因素,银行通过合约条款来卸除责任的方式,将来可能会被打破。
如阁下想了解更多银行金融、诉讼或争议解决等详情,请联络本所诉讼及争议排解部主管徐凯怡律师(heidichui.office@sw-hk.com)。
免责声明:于此提供的资料只供参考,不构成法律意见,上述资料亦受制于适用案例及法例不时的更新与修改,需以当地法律顾问的法律意见为准。
[1] 本案合约中的不依赖条款,可供参考:
Clause 4.12: ACKNOWLEDGMENT
You understand and agree that:
(a) The above brief statement cannot disclose all the risks and other significant aspects of the derivatives market and you should therefore carefully study derivative transactions before you trade;
(b) In respect of services rendered by us on a nondiscretionary basis,
(i) You make your own judgment in relation to the transactions;
(ii) We assume no duty to give advice or make recommendations;
(iii) If we make any suggestions, we assume no responsibility for your portfolio or for any investment or transaction made.
[2] 具体操守准则可参考 https://www.sfc.hk/web/EN/rules-and-standards/