News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
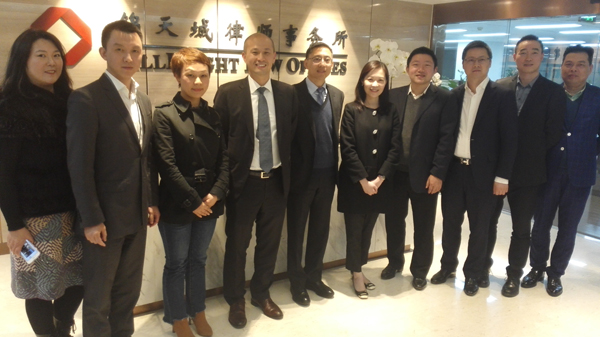
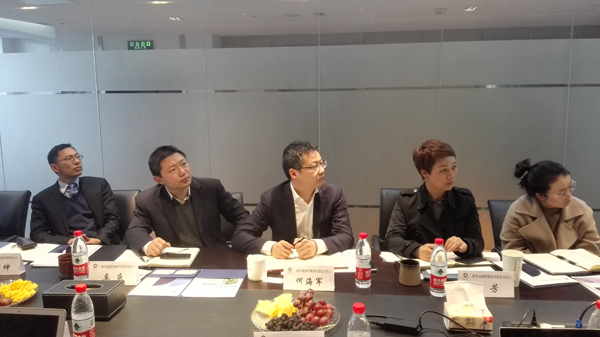
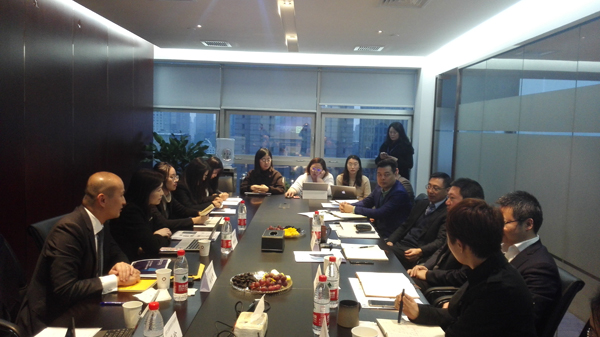
(中文) 史蒂文生黄律师事务所合伙人徐凯怡律师及张源辉律师,联同公共关系部经理叶慧珍小姐于2018年3月22日到访锦天城南京分所参观交流,双方就诉讼及仲裁和资本巿场(上市及收购合并)等议题举行交流座谈会,并获多位南京分所同仁热切款待,包括南京分所主任倪同木律师、高级合伙人奚庆律师、何海军律师、张宇坤律师、王芳律师、王小晶律师、刘嘉豪资深律师、以及南京分所行政主管吴小红女士等。
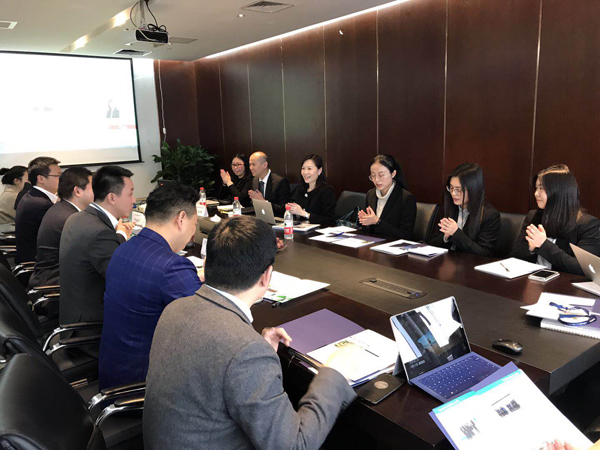
交流会由锦天城高级合伙人张宇坤致欢迎词掀开序幕,奚庆律师也介绍了南京分所的专业领域。
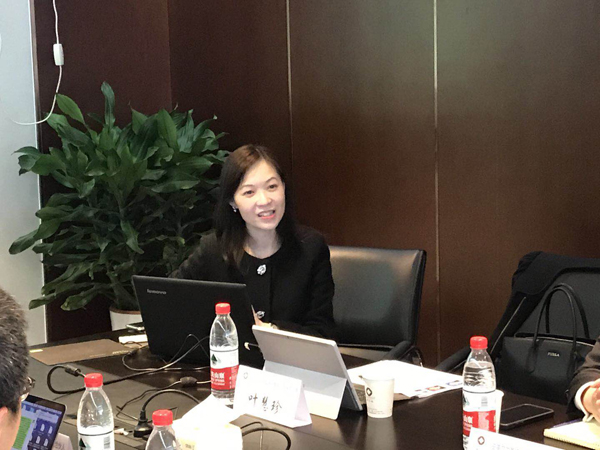
本所合伙人、诉讼及争议排解部门主管徐凯怡律师在交流会上就「跨境诉讼与仲裁」发表演讲。徐律师利用不同的案例,深入浅出地向大家阐述跨境诉讼与仲裁的各种情况,并互相讨论。徐律师更向大家分享第三方资助仲裁的最新发展。
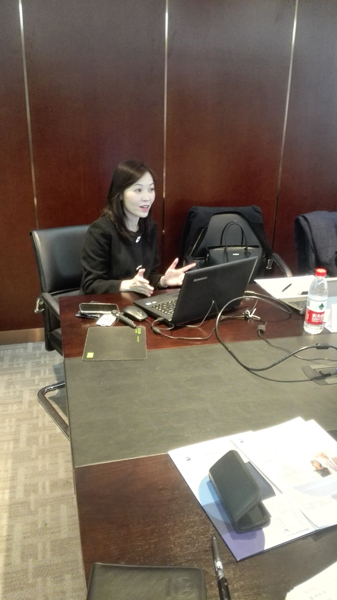
另外,合伙人张源辉律师也介绍了本所企业融资部门的团队及业务,也分享了本所在去年处理上市及收购合并的项目。
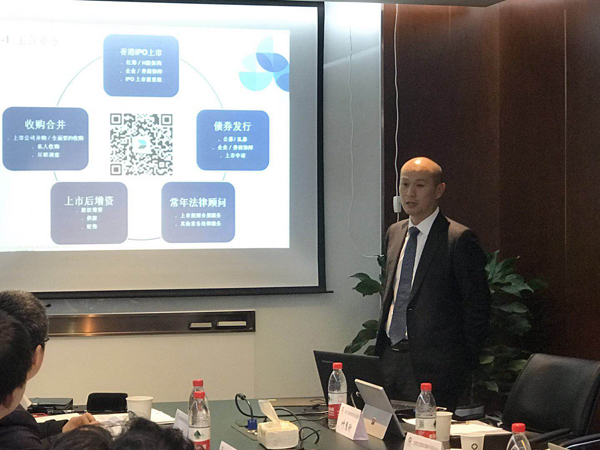
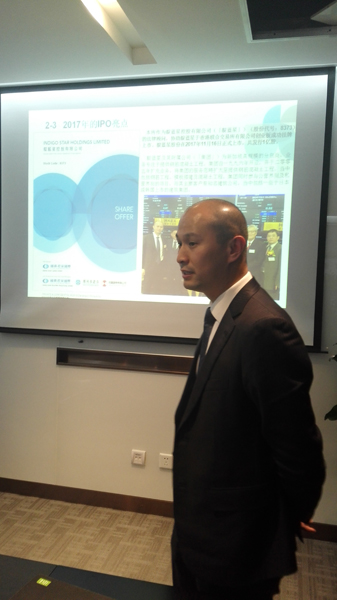
最后,南京分所主任倪同木律师肯定了这次交流会的成果,对本所的到访与分享表示感谢,期待未来两所有更多合作,并祝愿两所有更好的发展。
In July 2017, Mr. Ashley Alder, the Chief Executive officer of the Securities and Futures Commission (“SFC”) introduced a new approach to regulate licensed corporations, listed companies and companies that are applying to be listed on the Stock Exchange of Hong Kong. This new approach, often called the “front-loaded regulation”, aims to identify risks and minimise harm to the investing public from market misconduct and irregularities. It places a strong emphasis on “earlier, more targeted intervention”.
Conventional approach
There are three main arms of the SFC’s regulatory work. The first arm is education. The SFC would issue reports, circulars and guidelines periodically to provide regulatory guidance for the investing public, companies (listed and non-listed), and licensees. The second arm is the Intermediaries Division, which carries out licensing and supervisory functions. Regarding its supervisory role, it acts as a ‘good cop’ to perform regular inspections on regulated licensees with a view to protect the investing public. When material irregularities are found during inspections, the Intermediaries Division would refer the case to the Enforcement Division. The final arm is the Enforcement Division, which takes criminal, civil and disciplinary actions against offenders following investigations into the alleged irregularities or market misconduct.
Issues with the conventional approach
Traditionally, the SFC has primarily relied on the Enforcement Division to carry out its regulatory enforcement functions. On top of that, enforcement powers may only be exercised through a Court or the Market Misconduct Tribunal (“MMT”). This approach can be very time-consuming because all sanctions and remedies were dependent on the approval from the Court or MMT. Once the Intermediaries Division has referred a case to the Enforcement Division, the Enforcement Division would carry out further in-depth investigation into the alleged irregularity before commencing proceedings. The ensuing proceedings in the Court or MMT would also take a considerable amount of time.
Moreover, the transition of cases from the Intermediaries Division to the Enforcement Division may not always be smooth, due to the difference in their investigation approach and evidence gathering methodology causing unnecessary delay that may risk losing the opportunity for timely fact-finding. As a result, the irregularities or market misconducts might usually be needlessly prolonged.
New approach – “early intervention”
Under the new approach, the SFC will take pre-emptive measures to tackle market irregularities and “interact directly with the market at an early stage”.
In terms of administrative measures, the Intermediaries Division will now issue more thematic guidance to licensees and companies on how the SFC intends to deal with specific issues under the Securities and Futures Ordinance (“SFO”) and the Securities and Futures (Stock Market Listing) Rules (“SMLR”). Such thematic guidance will require licensees and companies to conduct internal control reviews regularly to check for irregularities. The active review will be done by the company/licensee so that irregularities can be identified and dealt with immediately.
The SFC may also issue a restriction notice pursuant to ss. 204 and 205 of the SFO. This gives the SFC powers to prohibit the targeted company or licensee from carrying out specific regulated activities that would create irregularities. The issue of restriction notice aims to preserve the assets of the licensee and its clients, and protect the interest of those clients and the investing public. While the SFC has been issuing restriction notices long before the adoption of the new approach, we can expect the SFC to exercise such powers more readily in the future in light of the new approach.
Regarding the disciplinary actions and proceedings brought by the Enforcement Division, the SFC will now be able to exercise enforcement powers without prior approval from the Court/MMT. Under the SMLR, the SFC could suspend a listed company without the need to seek Court approval. The SFC has indicated that it would use such power of suspension as an “exceptional early protective action” during an investigation pending further investigation or legal action.
Furthermore, the SFC will now give credit to the people and/or licensees who are willing to cooperate with the SFC in their investigations. Forms of cooperation may include, inter alia, voluntarily and promptly reporting any breaches or failings to the SFC, acceptance of liability, and taking rectification measures. In both disciplinary matters and Court/MMT proceedings, the SFC may reduce the sanctions imposed if the person/licensee is cooperative. In particular, the SFC has divided its disciplinary process into three stages, with sanction reduction up to 30%, 20% and 10% respectively. These changes to the SFC’s cooperation policy may give rise to more constructive solutions in resolving irregularities, while keeping the daily operations of the company intact. These benefits should help to provide more incentive for people and licensees to cooperate with the SFC.
Overall, the Intermediaries Division will be more proactive in exercising its supervisory powers, meanwhile, the Enforcement Division will only focus on the most serious issues, such as fraud and corporate misfeasance, which would have serious ramifications to the integrity of the capital markets of Hong Kong.
Implications to companies: the changes that will affect your business
The new approach may increase the efficiency of the SFC in handling investigations into the irregular conduct of licensees, companies, and also individuals. The cooperation between the SFC and the licensed entities is also going to be tighter.
However, this approach may also cause the compliance cost of licensees and companies to soar. Licensees and companies may need to conduct excessive internal reviews and monitoring in order to meet the requirements of the regulators, albeit there may not be any material findings on any misconducts.
The lack of universal standards for internal reviews conducted by licensees and companies may also be problematic, as the standard of review would vary from one licensee/company to another, making it difficult for licensees and companies to fully understand how to comply with the SFC’s requirements.
The expansion of enforcement powers of the Intermediaries Division may also be seen as a misplacement of resources. In essence, the roles of the Intermediaries Division and the Enforcement Division are distinct. The “front-loaded” approach delegates more enforcement power to the Intermediaries Division, despite the fact that the Division may not have enough expertise to conduct thorough investigations and obtain material findings for imposing preliminary sanctions.
To tackle such changes, listed companies and regulated activities licensees should be prepared that the SFC may take aggressive strategies to handle any irregularities spotted even at an early stage when the Enforcement Division has not been engaged. Professionals should be engaged to conduct ‘health checks’ on the entities’ internal control on a regular basis.
What we can provide to help you
Key contact
Stephen Wong
Partner
Tel: +852 2533 2525
Email: stephenwong.office@sw-hk.com
We are delighted to announce that Stevenson, Wong & Co. has been recognized as “Best Full-Service Law Firm 2018” in APAC Insider’s Hong Kong Business Awards 2018. APAC Insider’s Hong Kong Business Awards aims to recognize the perseverance and dedication of entire corporations to key personnel in value-added businesses. Each award nominee is carefully examined, with the judging panel taking into account their performance over the past 12 months to ensure that only the most deserving firms are handed one of the trophies.
About The Firm
Founded in 1978, Stevenson, Wong & Co. (SW) is a forward-looking, full-service law firm. The firm is ranked fifth among all Hong Kong domestic firms in the Top 50 research of Asian Legal Business. SW provides services including Banking & Finance, Corporate Finance/Capital Markets, China Practice, Corporate Commercial Law and Corporate Services, Employment Law, Family Law and Private Clients, Immigration, Intellectual Property, Litigation & Disputes Resolution, Media and Entertainment Law, Property, Regulatory Enforcement and Technology and Communications. SW has a strategic association with AllBright Law Offices, one of the nation’s largest full service law firms. SW is also a founding member of INTERLAW, an international association. Through our membership in INTERLAW and our association with AllBright, clients are assured of the same personal, open-minded and highly effective approach delivered by our lawyers in Hong Kong and China.
Please contact Mr. Willy Cheng, Mr. Hank Lo or Ms. Catherine Por for any enquiries or further information.
Introduction
On 15 December 2017, Hong Kong Exchanges and Clearing Limited (“HKEX”) published the Consultation Conclusions (the “Conclusions”) on the Review of the Growth Enterprise Market (“GEM”) and Changes to the GEM and Main Board Listing Rules. The revised Listing Rules took effect from 15 February 2018 with transitional arrangements.
|
Highlights Revised GEM listing requirements with effect from 15 February 2018:
Revised Main Board listing requirements with effect from 15 February 2018:
|
Under the revised regime, Growth Enterprise Market (创业板) is renamed as “GEM” for both English and Chinese names and repositioned from a market for emerging companies to a market for small to mid-sized companies.
All the proposals in the consultation paper are adopted except for the proposals regarding the (a) the admission requirements for GEM transfer to the Main Board; and (b) extending the post-IPO lock up requirement on controlling shareholders for Main Board listing applicants which are not adopted.
Key Conclusions
|
Current requirements |
Revised requirements |
|
| A. Transfer from GEM to Main Board
|
||
|
Positioning |
|
|
| B. GEM Listing requirements | ||
|
Cash flow requirement |
Minimum operating cash flow of HK$20 million |
Minimum operating cash flow of HK$30 million |
|
Minimum market capitalisation at the time of listing |
HK$100 million |
HK$150 million |
|
Minimum public float value at the time of listing |
HK$30 million |
HK$45 million |
|
Post-IPO lock-up period for controlling shareholders |
Cannot sell shares for the first 6 months upon listing; may sell shares for the next 6 months but should retain control |
Cannot sell shares for the first 12 months upon listing; may sell shares for the next 12 months but should retain control |
|
Offering mechanism |
100% placing allowed subject to full disclosure in the listing document |
Align with Main Board where mandatory public offering of at least 10% of the total offer size |
|
Placing to core connected persons/connected clients/existing shareholders and their close associates |
No restriction provided full disclosure is made in the listing document |
Align with Main Board where waiver/consent of The Stock Exchange of Hong Kong Limited is required |
| C. Main Board Listing requirements | ||
|
Minimum market capitalisation at the time of listing |
HK$200 million |
HK$500 million |
|
Minimum market capitalisation at the time of listing |
HK$50 million |
HK$125 million |
Transitional Arrangements in relation to Listing Applications
Listing applications submitted before 15 February 2018
Listing applications submitted to the HKEX before 15 February 2018 will be processed in accordance with the GEM or Main Board Listing Rules in force as at the date of the Conclusions. Only one renewal of such applications will be permitted thereafter.
Listing applications submitted on or after 15 February 2018
Listing applications submitted to the HKEX on or after 15 February 2018 will be processed in accordance with the revised GEM or Main Board Listing Rules.
Transitional Arrangements in relation to GEM Transfer Applications
GEM transfer applications submitted before 15 February 2018
Applications to transfer from GEM to the Main Board that are submitted by eligible issuers before 15 February 2018 and have not lapsed, been rejected or returned as at that date, will be processed under the GEM streamlined process. The eligibility for the Main Board will be assessed in accordance with the Main Board Listing Rules in force at the date of the Conclusions, i.e. 15 December 2017. Only one renewal of such applications will be permitted thereafter.
GEM transfer applications submitted from 15 February 2018 to 14 February 2021
The Conclusions provide a 3-year transitional period. All GEM transfer applications submitted by eligible issuers within the period from 15 February 2018 to 14 February 2021 will have eligibility for the Main Board assessed in accordance with the Main Board Listing Rules in force as at the date of the Conclusions, i.e. 15 December 2017, and subject to the following requirements:
(a) applicants that have changed their principal businesses and/or controlling shareholders since listing on GEM will be required to:
• appoint a sponsor to conduct due diligence; and
• publish a listing document as a new listing applicant to the Main Board; or
(b) applicants that did not change their principal business and controlling shareholders since listing on GEM will only need to:
• prepare a GEM transfer announcement in connection with its GEM transfer; and
• appoint a sponsor to conduct due diligence in respect of their activities during the most recent full financial year and up to the date of the GEM transfer announcement to ensure that the information in the GEM transfer announcement is accurate, complete and not misleading.
Implications
One of the main implications of the HKEX’s proposal was the reform of GEM as a stand-alone board. Without the streamlined transfer process, GEM transfer applicants will be required to appoint a sponsor to conduct due diligence and publish a “prospectus-standard” listing document for its transfer application.
Nevertheless, in the light of the three-year transitional arrangement, eligible GEM issuers without change of principal business nor controlling shareholders since listing will still be allowed to only issue a GEM transfer announcement and appoint a sponsor to conduct due diligence in respect of their activities during the most recent full financial year for their transfer application to the Main Board.
Another amendment to the rules relates to a controlling shareholder’s lock-up period after a GEM listing. Following the revision, the post IPO lock up will be extended to a “12+12” lock up period, in the sense that the controlling shareholder(s) cannot dispose any of the issuer’s shares held by it (with exceptions) during the first year after listing and must retain a controlling stake of the issuer for the subsequent year.
This newsletter is for information purposes only. Its content does not constitute legal advice, and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage.
Please contact our Hank Lo or Rodney Teoh for any enquiries or further information.
We are delighted to announce that our Partner and Head of Litigation and Dispute Resolution Department Ms. Heidi Chui has been appointed by the Secretary for Financial Services and the Treasury of the Government of the Hong Kong Special Administrative Region as a member of Disciplinary Panel A of the Hong Kong Institute of Certified Public Accounts (“HKICPA”) in February 2018 for a term of two years.
The HKICPA is the statutory licensing body of accountants in Hong Kong. It is responsible for matters including the maintenance of the quality of entry to the profession; the promulgation of standards on financial reporting, auditing and assurance, and accounting ethics standards; as well as the development of the profession.
Ms. Heidi Chui is an Arbitrator (on the panel list of the Law Society of Hong Kong), Fellow of the Chartered Institute of Arbitrators (U.K.) and an Accredited General Mediator with both the Hong Kong International Arbitration Centre and the Law Society of Hong Kong. She is also a member of the Arbitration Committee of The Law Society of Hong Kong. She is also a China Appointed Attesting Officer.
Please contact Ms. Heidi Chui for any enquiries or further information.
Stevenson, Wong & Co. is delighted to announce 3 awards, a testament to the excellence and territory wide recognition of our Family Department.
First, our Family Department has been selected as the winner of “Family – Law Firm of the Year – Hong Kong” in Lawyer Monthly Legal Awards 2017

Secondly, we have been awarded “Family Mediation Law Firm of the Year in Hong Kong 2018” by Corporate INTL. Corporate Intl Magazine Global Award which commemorates those who have been successful over the past 12 months and who have shown excellence not only in expertise but in service.
Thirdly, our Family Department has again been recognized for its success and dedication in the legal industry by being awarded as “Family Law Firm of the Year – Hong Kong” in Corporate USA Today Annual Awards 2018 and Lawyer International – Legal 100 2018 Awards.
Stevenson, Wong & Co has one of the leading family law practices in Hong Kong with over 40 years of experience. The practice has grown and become a significant part of a developing Private Client department which uniquely also provides wealth protection and succession planning, estates and trusts, Committee work, wealth and asset management, all under one roof. Our teams are dedicated and aim to provide effective and practical solutions and support to people going through changes in their family circumstances. We have expertise in dealing with all aspects of contentious and non-contentious family matters. We also deal with cases with an international element, whether they relate to children or finances. We regularly help clients with PRC issues.
We also offer and promote mediation as an alternative dispute resolution procedure. We regularly conduct mediations for a variety of family issues with a high success rate. We are dedicated to the use of alternative dispute resolution in litigation, providing assistance to parties to reach a mutually agreed settlement in a timely and flexible manner.
Our Succession planning and estates practice group, in addition to assisting our clients with the preparation of wills, succession planning and the handling of probate applications, works closely with our family team to assist separating parties in wealth protection. We handle financial and maintenance claims of family and dependants against the estate of deceased persons. We offer advice and help resolve financial disputes involving complex issues, substantial assets or complicated company and trust structures
As well as with SW Trustee, we also work closely with international trust corporations to establish trusts to meet the needs of our domestic and international clients.
Committee Work is a growing area in Hong Kong and we are experienced in handling applications under Part II of the Mental Health Ordinance, advising Committees and acting as a Professional Committee appointed by the Court of First Instance.
Please contact Ms. Catherine Por for any enquiries or further information.