新闻快讯
有关本所的新闻快讯,请浏览以下内容。如有兴趣个别了解,请点击此处与我们联系。
 史蒂文生黄律师事务所
新闻快讯
有关本所的新闻快讯,请浏览以下内容。如有兴趣个别了解,请点击此处与我们联系。
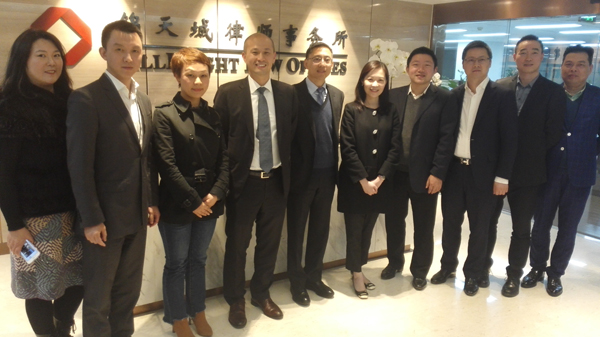
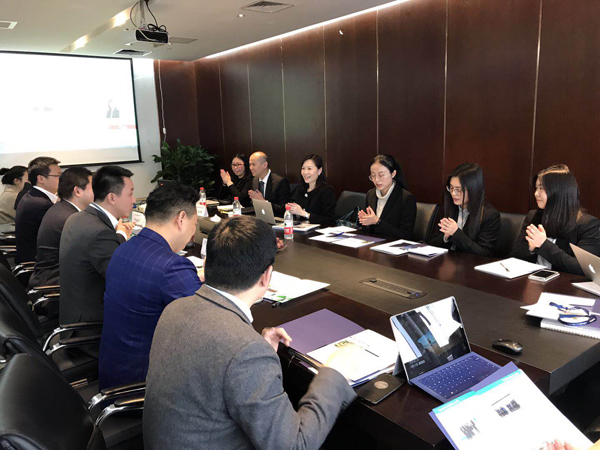
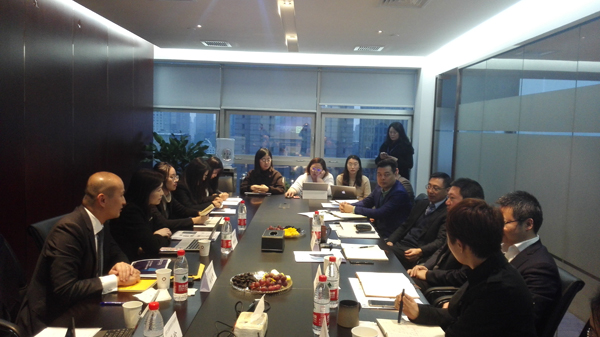
史蒂文生黄律师事务所合伙人徐凯怡律师及张源辉律师,联同公共关系部经理叶慧珍小姐于2018年3月22日到访锦天城南京分所参观交流,双方就诉讼及仲裁和资本巿场(上市及收购合并)等议题举行交流座谈会,并获多位南京分所同仁热切款待,包括南京分所主任倪同木律师、高级合伙人奚庆律师、何海军律师、张宇坤律师、王芳律师、王小晶律师、刘嘉豪资深律师、以及南京分所行政主管吴小红女士等。
交流会由锦天城高级合伙人张宇坤致欢迎词掀开序幕,奚庆律师也介绍了南京分所的专业领域。
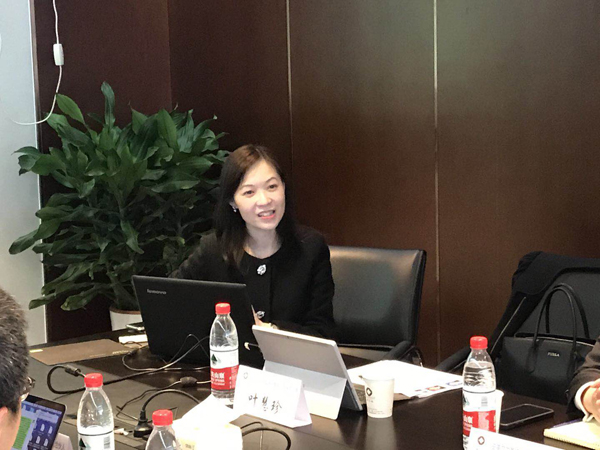
本所合伙人、诉讼及争议排解部门主管徐凯怡律师在交流会上就「跨境诉讼与仲裁」发表演讲。徐律师利用不同的案例,深入浅出地向大家阐述跨境诉讼与仲裁的各种情况,并互相讨论。徐律师更向大家分享第三方资助仲裁的最新发展。
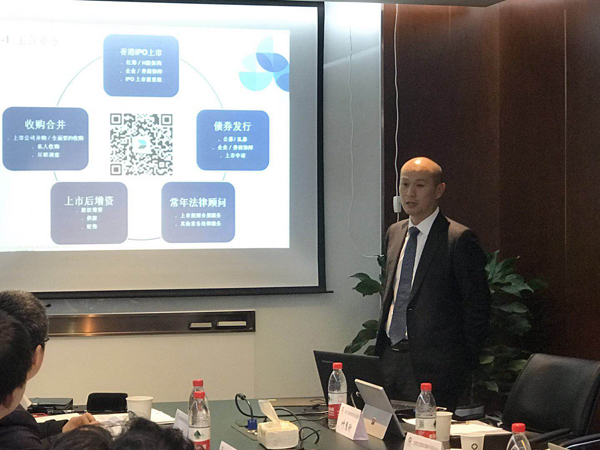
另外,合伙人张源辉律师也介绍了本所企业融资部门的团队及业务,也分享了本所在去年处理上市及收购合并的项目。
最后,南京分所主任倪同木律师肯定了这次交流会的成果,对本所的到访与分享表示感谢,期待未来两所有更多合作,并祝愿两所有更好的发展。
(English) In July 2017, Mr. Ashley Alder, the Chief Executive officer of the Securities and Futures Commission (“SFC”) introduced a new approach to regulate licensed corporations, listed companies and companies that are applying to be listed on the Stock Exchange of Hong Kong. This new approach, often called the “front-loaded regulation”, aims to identify risks and minimise harm to the investing public from market misconduct and irregularities. It places a strong emphasis on “earlier, more targeted intervention”.
Conventional approach
There are three main arms of the SFC’s regulatory work. The first arm is education. The SFC would issue reports, circulars and guidelines periodically to provide regulatory guidance for the investing public, companies (listed and non-listed), and licensees. The second arm is the Intermediaries Division, which carries out licensing and supervisory functions. Regarding its supervisory role, it acts as a ‘good cop’ to perform regular inspections on regulated licensees with a view to protect the investing public. When material irregularities are found during inspections, the Intermediaries Division would refer the case to the Enforcement Division. The final arm is the Enforcement Division, which takes criminal, civil and disciplinary actions against offenders following investigations into the alleged irregularities or market misconduct.
Issues with the conventional approach
Traditionally, the SFC has primarily relied on the Enforcement Division to carry out its regulatory enforcement functions. On top of that, enforcement powers may only be exercised through a Court or the Market Misconduct Tribunal (“MMT”). This approach can be very time-consuming because all sanctions and remedies were dependent on the approval from the Court or MMT. Once the Intermediaries Division has referred a case to the Enforcement Division, the Enforcement Division would carry out further in-depth investigation into the alleged irregularity before commencing proceedings. The ensuing proceedings in the Court or MMT would also take a considerable amount of time.
Moreover, the transition of cases from the Intermediaries Division to the Enforcement Division may not always be smooth, due to the difference in their investigation approach and evidence gathering methodology causing unnecessary delay that may risk losing the opportunity for timely fact-finding. As a result, the irregularities or market misconducts might usually be needlessly prolonged.
New approach – “early intervention”
Under the new approach, the SFC will take pre-emptive measures to tackle market irregularities and “interact directly with the market at an early stage”.
In terms of administrative measures, the Intermediaries Division will now issue more thematic guidance to licensees and companies on how the SFC intends to deal with specific issues under the Securities and Futures Ordinance (“SFO”) and the Securities and Futures (Stock Market Listing) Rules (“SMLR”). Such thematic guidance will require licensees and companies to conduct internal control reviews regularly to check for irregularities. The active review will be done by the company/licensee so that irregularities can be identified and dealt with immediately.
The SFC may also issue a restriction notice pursuant to ss. 204 and 205 of the SFO. This gives the SFC powers to prohibit the targeted company or licensee from carrying out specific regulated activities that would create irregularities. The issue of restriction notice aims to preserve the assets of the licensee and its clients, and protect the interest of those clients and the investing public. While the SFC has been issuing restriction notices long before the adoption of the new approach, we can expect the SFC to exercise such powers more readily in the future in light of the new approach.
Regarding the disciplinary actions and proceedings brought by the Enforcement Division, the SFC will now be able to exercise enforcement powers without prior approval from the Court/MMT. Under the SMLR, the SFC could suspend a listed company without the need to seek Court approval. The SFC has indicated that it would use such power of suspension as an “exceptional early protective action” during an investigation pending further investigation or legal action.
Furthermore, the SFC will now give credit to the people and/or licensees who are willing to cooperate with the SFC in their investigations. Forms of cooperation may include, inter alia, voluntarily and promptly reporting any breaches or failings to the SFC, acceptance of liability, and taking rectification measures. In both disciplinary matters and Court/MMT proceedings, the SFC may reduce the sanctions imposed if the person/licensee is cooperative. In particular, the SFC has divided its disciplinary process into three stages, with sanction reduction up to 30%, 20% and 10% respectively. These changes to the SFC’s cooperation policy may give rise to more constructive solutions in resolving irregularities, while keeping the daily operations of the company intact. These benefits should help to provide more incentive for people and licensees to cooperate with the SFC.
Overall, the Intermediaries Division will be more proactive in exercising its supervisory powers, meanwhile, the Enforcement Division will only focus on the most serious issues, such as fraud and corporate misfeasance, which would have serious ramifications to the integrity of the capital markets of Hong Kong.
Implications to companies: the changes that will affect your business
The new approach may increase the efficiency of the SFC in handling investigations into the irregular conduct of licensees, companies, and also individuals. The cooperation between the SFC and the licensed entities is also going to be tighter.
However, this approach may also cause the compliance cost of licensees and companies to soar. Licensees and companies may need to conduct excessive internal reviews and monitoring in order to meet the requirements of the regulators, albeit there may not be any material findings on any misconducts.
The lack of universal standards for internal reviews conducted by licensees and companies may also be problematic, as the standard of review would vary from one licensee/company to another, making it difficult for licensees and companies to fully understand how to comply with the SFC’s requirements.
The expansion of enforcement powers of the Intermediaries Division may also be seen as a misplacement of resources. In essence, the roles of the Intermediaries Division and the Enforcement Division are distinct. The “front-loaded” approach delegates more enforcement power to the Intermediaries Division, despite the fact that the Division may not have enough expertise to conduct thorough investigations and obtain material findings for imposing preliminary sanctions.
To tackle such changes, listed companies and regulated activities licensees should be prepared that the SFC may take aggressive strategies to handle any irregularities spotted even at an early stage when the Enforcement Division has not been engaged. Professionals should be engaged to conduct ‘health checks’ on the entities’ internal control on a regular basis.
What we can provide to help you
Key contact
Stephen Wong
Partner
Tel: +852 2533 2525
Email: stephenwong.office@sw-hk.com
本所的法律服务再次获得肯定,于APAC Insider 2018年度香港商业奖中荣获「最佳全面法律服务律师事务所」。奖项是由评审委员综合考虑候选者在过去12个月的表现,经仔细审查后才授予奖项以示认同。
关于本所
史蒂文生黄律师事务所于1978年成立,是一家高瞻远瞩,致力为客户提供全方位法律顾问服务的事务所,全所共有160多人,荣登第5大香港本地律师事务所。本所提供一系列的法律和企业服务,包括中国事务、银行与金融、企业及商业法和公司服务、企业融资、雇佣法、家事法及私人事务、知识产权、诉讼及争议解决、财产转让、监管执法、科技与通讯、移民、媒体及娱乐法。于2013年与在中国内地极具规模的锦天城律师事务所建立了策略联盟,扩阔了本所在中国内地所提供的服务范围,并拓展业务地域。本所亦是国际律师事务所协会INTERLAW的创会成员之一,该会网络覆盖超过全球140个城市。本所于国际律师事务所协会的会员资格及与锦天城律师事务所建立的策略联盟,给客户一个强大的服务支援网络,加上本所中港两地的专业律师团队,为客户带来个人化、开放及高效的策略建议。
简介
香港联合交易所有限公司(「联交所」)于2017年12月15日刊发了《有关检讨创业板及修订《创业板规则》及《主板规则》的咨询文件》(「咨询文件」)的咨询总结(「咨询总结」)。经修订的上市规则已于2018年2月15日起生效,并有相关的过渡安排。
|
重点内容 创业板上市要求的修订(2018年2月15日起生效):
创业板上市要求的修订(2018年2月15日起生效):
|
经修订的制度下,「Growth Enterprise Market」及「创业板」均统一改称「GEM」,而创业板亦由为新兴公司而设的市场重新定位为中小型公司而设的市场。
除有关(a)由GEM转往主板的上市资格要求;以及(b)延长主板上市申请人控股股东的上市后禁售期的建议没有被采纳外,咨询文件中的所有建议修订都被采纳。
主要咨询总结内容:
|
现行机制 |
经修订机制 |
|
| A. 发行人转往主板上市 | ||
|
定位 |
|
|
| B. GEM上市要求 | ||
|
现金流要求 |
经营业务产生的现金流最少达港币3,000万元 |
经营业务产生的现金流最少达港币3,000万元 |
|
上市时最低市值 |
港币1亿元 |
港币1.5亿元 |
|
上市时最低公众持股价值 |
港币3,000万元 |
港币4,500万元 |
|
上市后控股股东禁售期 |
控股股东在上市后首六个月内不得售股;在接下六个月内可售股但须保留控制权 |
控股股东在上市后首十二个月内不得售股;在接下十二个月内可售股但须保留控制权 |
|
发行机制 |
在上市文件作全面披露即可作100%配售 |
与《主板规则》一致,即规定公开发售部分不少于总发行量的10% |
|
向核心关连人士/关连客户/现有股东及彼等各自紧密联系人配售股份 |
在上市文件作全面披露则不受限制 |
与《主板规则》一致,须经联交所豁免/同意 |
| C. 主板上市要求
|
||
|
上市时最低市值 |
港币2亿元 |
港币5亿元 |
|
上市时最低公众持股价值 |
港币5000万元 |
港币1.25亿元 |
与上市申请有关的过渡安排
于2018年2月15日之前提交的申请
新上市申请人若是于规则修订生效日期之前提交主板或创业板上市申请,现行《上市规则》下的上市资格及要求仍然适用,惟其后只可作出一次更新。
于2018年2月15日或之后提交的申请
新上市申请人若是于规则修订生效日期之后提交主板或GEM上市申请将根据经修订的GEM或主板上市规则处理。
有关GEM转板申请的过渡安排
于2018年2月15日之前提交的GEM发行人转主板上市申请
所有于规则修订生效日期前提交、且于规则修订生效日期尚未失效、被拒绝或退回的创业板转板申请,一概继续根据现行简化转板申请程序处理,其主板上市资格将按照现行《主板规则》进行评估,惟其后只可作出一次更新。
于2018年2月15日至2021年2月14日提交的GEM发行人转主板上市申请
咨询总结提供了一个3年的过渡期。 合资格发行人于2018年2月15日至2021年2月14日期间内提交的所有GEM发行人转主板上市申请,如遵守以下要求,其转往主板上市的资格将根据于咨询总结日期(即2017年12月15日)生效的主板上市规则进行评估:
(a) 自GEM上市后已变更其主要业务及╱或控股股东的申请人须:
• 委任保荐人进行尽职调查; 及
• 如主板新上市申请人般刊发上市文件;或
(b) 自GEM上市后没有变更其主要业务和控股股东的申请人仅须:
• 就从GEM转主板上市事宜拟备GEM转板公告; 及
• 委任保荐人就其于最近一个完整财政年度及直至GEM转板公告日期的业务进行尽职审查,以确保其GEM转板公告内的资料准确,完备且并无误导。
总结
联交所的提案的主要内容之一是将GEM改革为一独立市场。在取消简化转主板上市申请程序后,GEM转主板上市申请人将被要求委任一名保荐人进行尽职调查,并须为其转主板上市申请刊发达至「招股章程标准」的上市文件。
然而,根据三年期的过渡安排,合资格的GEM发行人如自上市起未发生主要业务或控股股东上的变动,仍可为其转往主板上市的申请仅发行GEM转板公告,以及委任保荐人对其在最近一个完整财政年度内的业务进行尽职调查。
上市规则的另一项修正涉及控股股东在GEM上市后的禁售期。 经修订后,GEM上市后的禁售期将延长至「12 + 12」 期限,这意味着控股股东在上市后的第一年内不得出售其持有的任何发行人股份(例外情况除外),并且必须在第二年内保留发行人的控股权。
本新闻简讯仅供参考之用。史蒂文生黄律师事务所竭力确保本文件所提供的资料准确可靠,但不保证该等资料绝对正确可靠,对于任何因资料不确或遗漏又或因根据或倚赖本文件所载资料所作决定、行动或不行动而引致的损失或损害,史蒂文生黄律师事务所概不负责。
本所合伙人、诉讼及争议排解部门主管徐凯怡律师获香港特别行政区财经事务及库务局财经事务科委任为香港会计师公会纪律审裁团成员之一,任期由2018年2月1日起为期两年。
徐律师十分荣幸获委任为香港会计师公会纪律审裁团成员之一,并会尽最大努力履行有关公职。
徐律师是仲裁员(香港律师会仲裁员名册);英国仲裁司学会院士、香港国际仲裁中心及香港律师会的认可调解员,身兼香港律师会仲裁委员会成员。徐律师亦是中国司法部委任的中国委托公证人。
如阁下有任何查询或想了解更多详情,请联络本所徐凯怡律师。
史蒂文生黄家事法团队表现优越,先后在不同法律大奖中屡获殊荣,当中包括于《律师月刊》法律奖项2017中荣获「年度家事法律师事务所 – 香港区」、于《Corporate Intl杂志》环球大奖中获颁发「年度香港家事调解律师事务所」、在Corporate USA Today 2018年度大奖及Lawyer International – Legal 100 2018大奖中荣获「年度家事法律师事务所 – 香港区」。上述各奖项旨在嘉许得奖者过去一年在其专业技能及服务方面表现出色,史蒂文生黄再次获奖,是对本所的法律服务及家事法团队的表现予以肯定及认同。

本所是香港领先的婚姻及家事法的律师事务所之一。现时主理家事的法官当中有三位是本所的前任合伙人,其中一位更是高等法院法官。自1978年起,本所于提供高效的法律服务,并当人们经历关系破裂或者改变家庭环境时提供支援。本部门有三大专责团队,分别是家事法、信托、遗产承办及筹划继承、以及受托监管人工作。
本所专门处理各类争议或非争议的家事案件、涉及国际因素的儿童事务及财务案件,并帮助客户处理有关内地事宜。
本所的团队亦有认可的家事调解员资历,经常主持各类型的家事调解,成效显着获得高成功率。本所提倡面对讼诉时利用调解,以省时及灵活的方法协助双方解决纠纷达致双嬴。
本所不但替客户处理家人和受养人对身故者的财产提出财务及赡养费的申请,更会解决汲及繁复、庞大资产或复杂公司和信托架构的纠纷。
本所的信托、遗产承办及筹划继承团队除了协助客户草拟遗嘱、筹划遗产继承和处理遗产承办外,也与本所的婚姻及家事法团队合作无间,协助离异双方成立信托以保障他们及子女的长远利益。成立信托时本所亦会与国际信托公司紧密联系,迎合我们本地及世界各地客户的需要。
受托监管人工作在香港是一个不断发展的领域,我们有丰富经验处理《精神健康条例》第II部的申请,给予受托监管人建议,并担任原讼法庭委任的专业委员。
如阁下有任何查询或想了解更多详情,请联络本所傅景元律师。