News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
(中文) 2021年3月4日,本所合伙人,银行及金融部和诉讼及争议解决部主管徐凯怡律师受邀为银行客户的管理团队提供企业线上培训。本次培训的主题为「香港反歧视法例—招聘面试及甄选程序」。
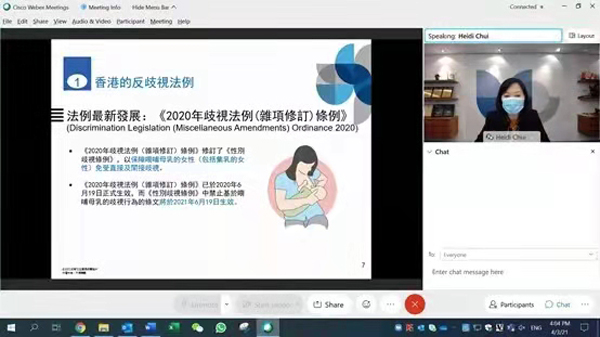
徐律师在课程中讲解了香港的反歧视法例并介绍了相关法例的最新发展。她亦就招聘面试及甄选程序的最佳行事方式作出详尽解说,以及透过案例分析阐释了划一甄选准则的例外情况。
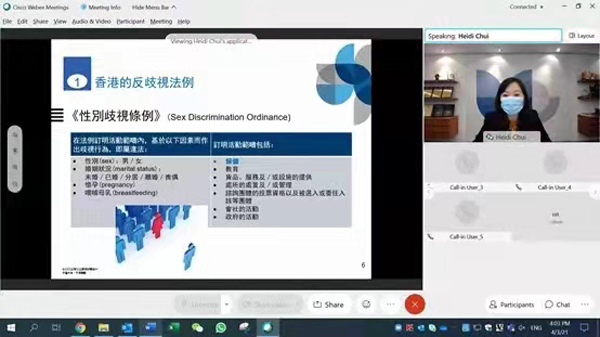
透过本次培训,客户对香港的反歧视法例有了进一步的认识,加强配合银行各项营运及合规的需求,并对日后的面试和甄选程序能有更完善的准备。
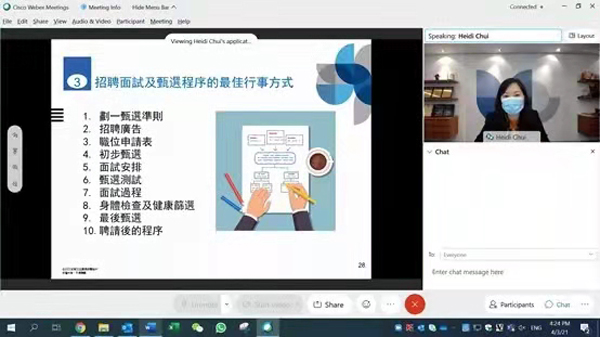
如阁下有任何查询或想了解更多详情,请联络本所徐凯怡律师 (heidi.chui@sw-hk.com)。
On 26 February 2021, Stevenson, Wong & Co. celebrated the Year of Ox at our office in the Landmark. Due to Covid-19, we were unable to gather for a dinner celebration. Nevertheless, our staff were treated to a virtual festival and performance prepared by our trainee solicitors.
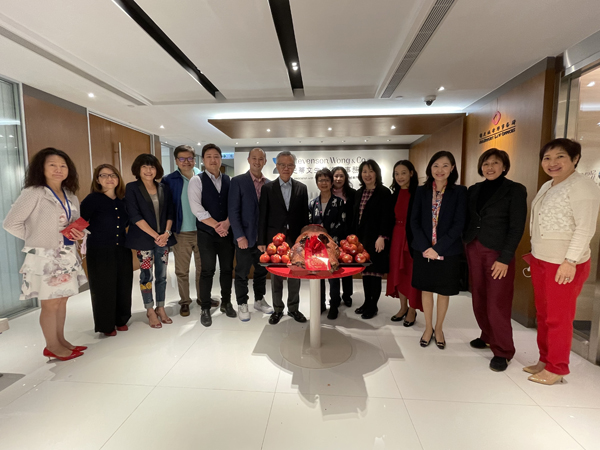
Our CNY celebration started with an opening speech by our senior Partner Mr. Willy Cheng. He expressed gratitude to the staff for their hard work throughout last year and his vision for the firm’s future. He also presented Service Awards to staff who have worked for more than 10 years and 20 years in the firm. The night was filled with laughter along with singing and a lion-dance performed by the trainees and an exciting lucky draw!
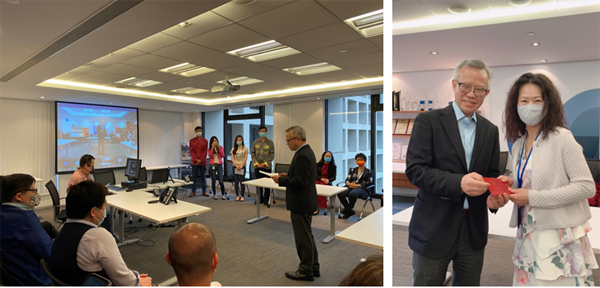
Our Partner Mr. Cheng delivered an opening speech and presented a service award to our Office Manager Ms. Vivien Lo.
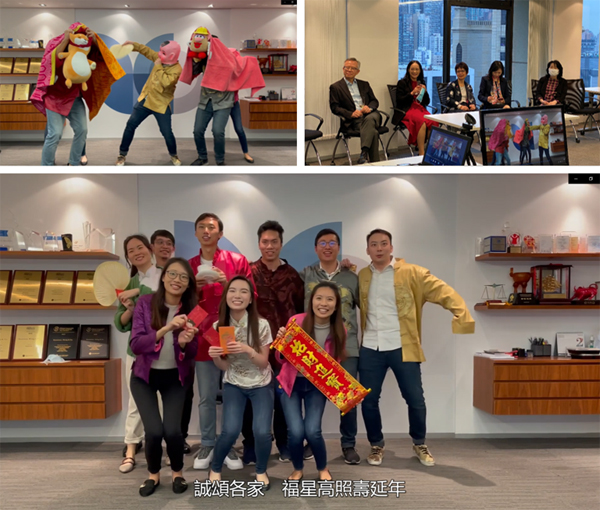
Our trainees sang and performed a lion dance to celebrate the CNY.
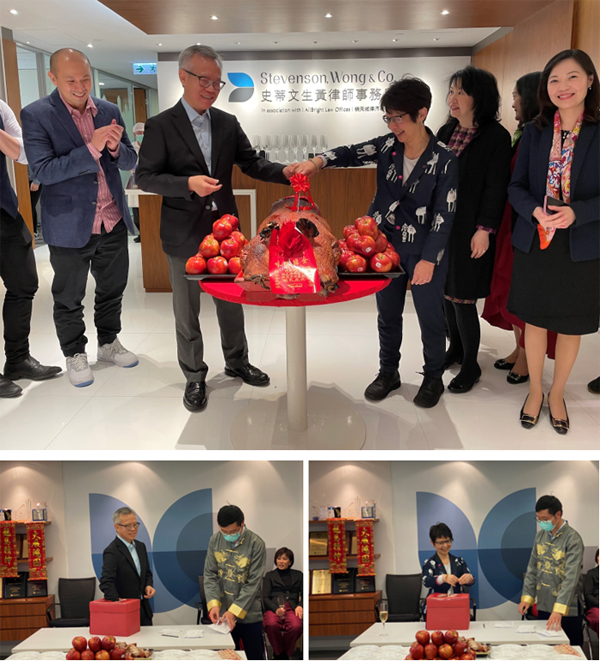
A fun-filled night with roasted pig cutting ceremony and exciting lucky draw.
On 19 February 2021, our firm’s Partner, Head of Banking and Finance department and Dispute Resolution department, Ms. Heidi Chui, was interviewed by Guangdong Television’s Evening News on Hong Kong’s latest developments and opportunities under the “Outline Development Plan for the Guangdong-Hong Kong-Macao Greater Bay Area”, which was launched 2 years ago.
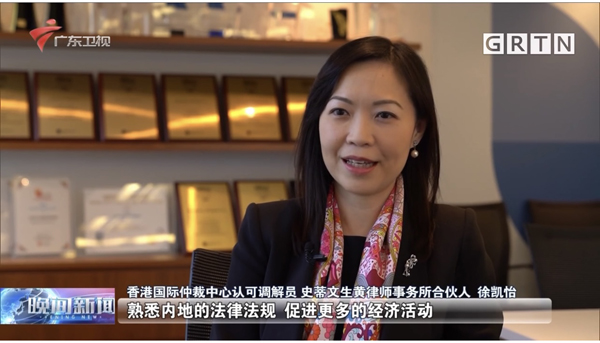
During the interview, Ms. Chui shared the latest initiative by the Ministry of Justice of the People’s Republic of China. The initiative allows eligible Hong Kong lawyers to practice in specified area of law in 9 cities in the Greater Bay Area after passing the qualifying examination and training. The initiative would enable Hong Kong lawyers to understand more about the Mainland legal market and further facilitate economic activities between the Mainland and Hong Kong.
Please click here to watch the interview (available in Chinese only).
Please contact our Ms. Heidi Chui (heidichui.office@sw-hk.com) for any enquiries or further information.
Background
On 8 February 2021, the Securities and Futures Commission (the “SFC”) published a consultation paper on (i) the Proposed Code of Conduct on Bookbuilding and Placing Activities in Equity Capital Market and Debt Capital Market Transactions and (ii) the “Sponsor Coupling” Proposal (the “Paper”). This followed their thematic review of licensed intermediaries engaged in equity capital market (“ECM”) or debt capital market (“DCM”) over the state of the market as well as the practices and conduct of intermediaries.
In the Paper, the SFC highlighted a number factors which in their view had hampered the price discovery process for some offerings. These included inflated or opaque demand, undesirable intermediary conduct such as brokers without a mandate “swarming” order books at the last minute with orders of unknown quality, as well as non-alignment of sponsors’ incentives and liabilities especially in larger IPOs which may lead to concerns on a sponsor laxing its due diligence enquiries in competition for the head of the underwriting syndicate. With a view to meeting their regulatory objectives, the SFC sets out in the Paper their Proposed Code of Conduct on Bookbuilding and Placing Activities in Equity Capital Market and Debt Capital Market Transactions (the “Bookbuilding Code Proposal”) and the “Sponsor Coupling” Proposal (the “Sponsor Coupling Proposal”) and invited comments from market participants and interested parties.
The Proposed Code of Conduct on Bookbuilding and Placing Activities in ECM and DCM Transactions
Specifically, the SFC observed that the bookbuilding and placing activities of certain market participants are affected by substandard practices and control deficiencies in various areas, such as the lack of clearly defined roles or functions of intermediaries engaging in capital raising, fluid syndicate membership and fee arrangements, inflated demand, lack of transparency, conflicts of interest, preferential treatment or rebates paid to investors, lack of documentation and potential breaches of the requirements of The Stock Exchange of Hong Kong Limited (“SEHK”).
In the Bookbuilding Code Proposal, the SFC, among other things, purported revision of the Code of Conduct for Persons Licensed by or Registered with the SFC (the “Code of Conduct”) by way of a new paragraph 21 on Bookbuilding and Placing Activities in ECM and DCM Transactions (the “Proposed Code”). This Proposed Code focused on expected standards of conduct and systems and controls in the following areas:
(a) assessment of the issuer and the offering – before engaging in an offering, a capital market intermediary (“CMI”) should take reasonable steps to obtain an accurate understanding of the issuer and establish a formal governance process to review and assess the offering which involves designation of member(s) of senior management to assess, for example, the structure of the offering, any actual or potential conflicts of interest and other associated risks;
(b) appointment of CMIs and overall coordinators (“OCs”) – the appointments of OCs and other CMIs and the determination of their roles, responsibilities and fee arrangements should all take place at an early stage:
(i) before a CMI (other than an OC) starts any bookbuilding or placing activities, it should ensure that (i) it has been formally appointed by the issuer (or another CMI in the case of a non-syndicate CMI) under a written agreement to conduct such activities, and (ii) the written agreement clearly specifies the roles and responsibilities of the CMI as well as a description of the fee arrangements; and
(ii) likewise, before an OC provides any services as stipulated in the Proposed Code to the issuer for a share offering, or before an OC participates in any bookbuilding or placing activities for a debt offering, it should ensure that (i) it has been formally appointed by the issuer under a written agreement to conduct such activities, and (ii) the written agreement clearly specifies the roles and responsibilities of the OC as well as a description of the fee arrangements;
(c) advice to the issuer – an OC should provide advice to the issuer on syndicate membership, fee arrangements, marketing strategy as well as pricing and allocation, and ensure that the advice and recommendations are balanced and based on thorough analysis, taking into account the issuer’s preferences and objectives as well as prevailing market conditions and sentiment, and aligned with all legal and regulatory requirements;
(d) marketing – an OC should advise and assist the issuer in developing an appropriate marketing and investor targeting strategy and should inform other syndicate CMIs of the marketing and investor targeting strategy so that they can carry out their own activities accordingly;
(e) rebates and preferential treatment – a CMI should not offer any rebates to its investor clients or pass on any rebates provided by the issuer. In addition:
(i) for an IPO, a CMI should not enable any investor clients to pay, for each of the shares allocated, less than the total consideration as disclosed in the listing documents; and
(ii) for a debt offering, a CMI should not enter into any arrangements which may result in investor clients paying different prices for the debt securities allocated;
Furthermore, a CMI should, among other things, disclose to the issuer, the OCs, all of its targeted investors and the non-syndicate CMIs it appoints, any rebates offered by the issuer to CMIs and any preferential treatment of any CMIs or targeted investors (such as guaranteed allocations). It should also advise the issuer against providing any arrangements whereby, in the case of an IPO, the investor clients would pay, for each of the shares allocated, less than the total consideration as disclosed in the listing documents and, in the case of a debt offering, the investor clients would pay different prices for the debt securities allocated;
(f) assessment of investor clients – a CMI should take reasonable steps to identify connected clients and core connected persons of the issuer and inform the OC before placing an order on behalf of such clients. An OC should provide more information to CMIs to facilitate their identification of investors related to the issuer, such as a list of such persons or entities;
(g) bookbuilding, including order placement and order book management, pricing – an OC should ensure that the pricing and allocation recommendations made to the issuer fully take into account the principles and factors stipulated under the Proposed Code. For instance, that the price is determined based on orders received from targeted investors during the bookbuilding process and that the securities are allocated to investors who can build a strong investor or shareholder base for the issuer. It is also proposed to require the identities of all investors to be disclosed in the order book, except for orders placed on an omnibus basis.
Further, it is proposed that a CMI should:
(i) take reasonable steps to ensure that all orders placed in the order book on behalf of its own investor clients, itself and its group companies represent bona fide demand. The CMI must not place knowingly inflated orders;
(ii) make enquiries with its investor clients about orders which appear unusual, e.g., orders which are not commensurate with the client’s financial profile, before placing these orders; and
(iii) maintain adequate records of orders placed by its investor clients so as to substantiate that there are no fictitious or knowingly inflated orders placed in the order book.
On the other hand, an OC should:
(i) ensure that the identities of all investor clients are disclosed in the order book, except for orders placed on an omnibus basis;
(ii) make enquiries with CMIs if any orders appear to be unusual or irregular;
(iii) consolidate the order book by taking reasonable steps to identify and eliminate duplicated orders, inconsistencies and errors; and
(iv) segregate and clearly identify in the order book any proprietary orders of CMIs and their group companies;
(h) allocation – among other things, an OC or CMI should establish and implement an allocation policy which sets out the criteria for making allocation recommendations to the issuer;
(i) conflicts of interest – among other things, a CMI should establish and implement policies and procedures to identify, manage and disclose actual and potential conflicts of interests with investor clients and to establish and implement policies to govern the process for generating its own proprietary orders as well as making allocations to such orders. It should give priority to investor clients’ orders over its own proprietary orders and those of its group companies and only be a “price taker” in relation to the proprietary orders; and
(j) disclosures to the issuer, other CMIs and investors – CMIs should, among other things, provide information in a timely manner and ensure that it is complete, accurate and has a proper basis, about connected clients and core connected persons of the issuer for a share offering, and about investor clients which have associations with the issuer, CMIs and their group companies for a debt offering, to the OC and non-syndicate CMIs appointed by them, and to disseminate the marketing and investor targeting strategy to non-syndicate CMIs. It should also provide “book messages” and other information related to the offering to enable investor clients to make informed decisions.
The “Sponsor Coupling” Proposal
The SFC proposed “sponsor coupling” which requires that, among other things, the listing applicant should appoint at least one sponsor which is independent of the listing applicant who should also be appointed as an OC for the IPO, or have a group company which is also appointed as an OC for the IPO (the “Sponsor OC”). Interestingly, the Sponsor OC should be appointed as OC and sponsor at the same time and at least two months before filing the listing application. The listing applicant can appoint other OCs (which may or may not be sponsors of the IPO), which should be no later than two weeks after the submission of the listing application.
As observed by the SFC, the Sponsor Coupling Proposal was aimed to achieve effects such that, among other things, at least one sponsor would be free of potential incentives to limit due diligence in order to secure an OC role, and the Sponsor OC should be in a position to give comprehensive advice to the listing applicant throughout the transaction.
Analysis and Takeaways
The implementation of the Bookbuilding Code Proposal may possibly lead to a change in the executory structure of IPO deals, given that the timeframe has been set for appointment of the OCs and CMIs at an early stage. Sponsor OC will find itself exercising both functions as sponsor and issuer’s marketing adviser at an early stage of an IPO. The Proposed Code could also allow a more orderly execution of the bookbuilding and placing process in a given ECM or DCM transaction.
Moreover, the Sponsor Coupling Proposal may bring the interest of the sponsor and OC into better alignment. The early appointment of Sponsor OC prior to commencement of the sponsor’s due diligence discourages a sponsor from compromising its due diligence obligations. From a regulatory perspective, OC which also has a sponsor hat may also be more well-equipped in discharging its regulatory obligations in relation to identification of duplicated orders or circumstances suggesting lack of genuine demands for the securities, in light of its knowledge about the listing applicant and its business acquired in the course of performing its due diligence functions as a sponsor.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This newsletter is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
(中文) 香港国际仲裁中心 (下称“港仲”) 在2021年2月9日发布了2020年的相关数据,对港仲的受案情况以及《关于内地与香港特别行政区法院就仲裁程序相互协助保全的安排》 (下称“《仲裁互助保全安排》”) 作出了综合数据统计,为仲裁参与人提供了重要的参考。
本文对这些数据进行了简要的介绍,如想查看港仲2020年数据的全文,请参见:https://www.hkiac.org/news/hkiac-releases-statistics-2020。
显著的成绩
在2020年,港仲共接收了318宗仲裁案件,受案量是过去10年来的最高。在这318宗仲裁案件中,203宗是由港仲管理,较2019年增长近20%。
争议总金额为688亿港元 (约88亿美元),创下港仲自2011年开始公布此类信息以来的新高。
2020年提交的仲裁案件涉及来自45个司法管辖区的当事方。72%的仲裁案件以及86%的港仲管理仲裁案件是国际性仲裁案件。绝大多数仲裁案件的仲裁地为香港,所涉准据法数量多达12个。
在2020年,HKIAC举行了117次聆讯,其中80次全部或部分以遥距聆讯方式进行,37次是在香港进行的实体线下聆讯。
《仲裁相互保全安排》的发展
总结
近年以仲裁作为争议解决方式的民商事纠纷日渐增加,各仲裁机构受案量也不断上升。香港作为亚太区争议解决中心,是当事人值得信赖的仲裁地。受到疫情的影响,香港各仲裁机构 (例如港仲) 也在积极开拓创新,为当事人提供了与时俱进的仲裁服务 (例如遥距开庭等)。
本所诉讼及争议解决团队在2020年为当事人代理了多起仲裁案件,并利用线上和线下结合的聆讯方式,为内地、香港和其他司法管辖区的当事人提供了高效便捷的争议解决服务。
Between 2 to 5 February 2021, our firm’s Partners Mr. Willy Cheng, Ms. Catherine Por and Ms. Lai Lam participated in the largest Asia Pacific Regional Meeting ever, and the first regional meeting to take place virtually. The topic this year was “Forward to Better: Recalibrating the Business Environment”. INTERLAW is an elite global law firm network comprised of top tier independent law firms from over 150 cities worldwide. To enhance the relations of strategic partners, seminars and networking meetings are held regularly for members to discuss topical issues and latest legal developments.
On 2 Feb, our Partner Mr. Willy Cheng was a speaker for the topic of- “Balancing the Books: Tax at the vanguard of Recovery”. At the meeting, he explained the challenges presented by COVID-19 to Hong Kong’s economy and the relief measures rolled out by the Hong Kong government to relieve the burden of citizens and enterprises. He also illustrated the potential tax reforms that may increase government revenue and help Hong Kong’s economic recovery, such as goods and services tax and digital services tax.
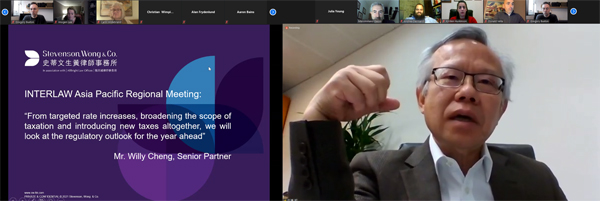
Our firm’s partner, Mr. Willy Cheng at the Tax Meeting.
On 3 Feb, our Partners Ms. Catherine Por and Ms. Lai Lam, the vice-chair of the Diversity, Inclusion and Community committee (Asia Pacific) attended the meeting of “Leadership, Lessons and Long-term Strategy”. Panellists from across the region discussed diversity in their country and the strategies deployed for a more inclusive workplace. Catherine pointed out that Hong Kong aims to be a gender-equal society, but same-sex couples and LGBT groups still face challenges in view of recent litigation decisions.
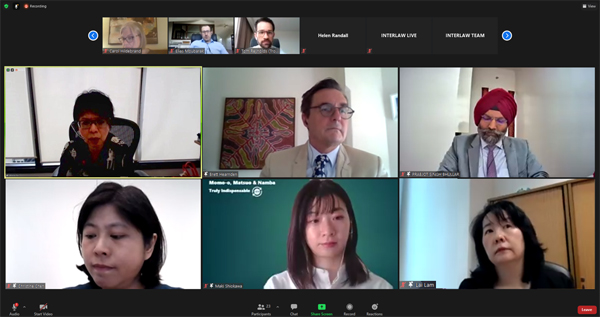
Our firm’s partners, Ms. Catherine Por (Top Right) and Ms. Lai Lam (Bottom Right) attended the Diversity, Inclusion and Community Meeting.
On the last day of the meeting, our Partner Ms. Lai Lam attended the Regional Business Meeting and Networking Session where participants from across the globe reviewed the year past and discussed business development initiatives for the coming year.
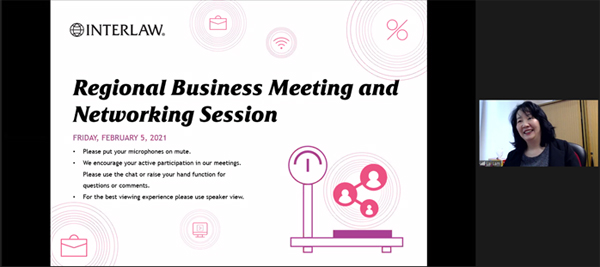
Please contact Mr. Willy Cheng, Ms. Catherine Por or Ms. Lai Lam for further enquiries about this event.