
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
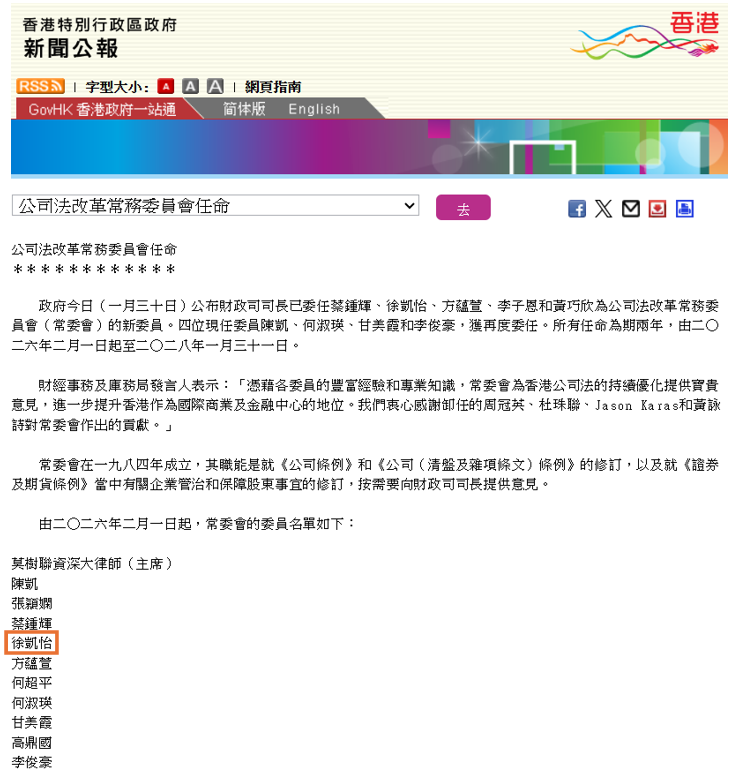
(中文) 本所欣然宣布,本所合伙人、银行与金融部及诉讼及争议解决部主管徐凯怡律师,获财政司司长委任为公司法改革常务委员会委员。是次委任由2026年2月1日起生效,为期两年。
 …
公司法改革常务委员会是香港财经事务及库务局辖下的重要咨询组织,其职能就《公司条例》和《证券及期货条例》等条例修订向政府提供专业意见。委员会致力于构建清晰、高效且稳健的法律框架,以优化企业营运环境,进一步巩固香港作为国际商业及金融中心的领先地位。
徐律师是香港律师会理事、大中华法律事务委员会副主席及仲裁委员会委员;同时担任香港国际仲裁中心理事和香港国际仲裁中心仲裁女性俱乐部 (WIA) 委员。徐律师多获多家知名仲裁机构委任为仲裁员及调解员,包括香港国际仲裁中心、中国国际经济贸易仲裁委员会、上海国际仲裁中心、华南(香港)国际仲裁院、亚非法协(香港)、北京仲裁委员会/北京国际仲裁中心等。此外,她亦是广东省高级人民法院﹑深圳前海合作区人民法院的特邀调解员。
徐律师拥有粤港澳大湾区执业律师资格及中国委托公证人身份,并为英国特许仲裁司学会院士。
如阁下有查询或想了解更多详情,请联络本所合伙人徐凯怡律师,或按此查看香港政府之新闻公报。
 …
Stevenson, Wong & Co. is pleased to announce that our Partner and Head of Banking and Finance, Litigation and Dispute Resolution, and Co-head of the FinTech Group, Heidi Chui, alongside our Partner and Deputy Head of Corporate Finance and Co-head of the FinTech Group, Rodney Teoh, have been honoured as Growth Drivers in The A-List 2025–26 by China Business Law Journal.
This recognition reaffirms the sustained leadership of both Partners in their respective fields. Ms. Chui has been acknowledged for this accolade for the fifth consecutive year, while Mr. Teoh has received this honour for the third consecutive year.
The selection for the “A-List Elite Lawyers” is based on thousands of nominations and independent research from corporate legal counsel, executives, and legal peers, ensuring a high level of industry credibility. The “Legal Elite” category specifically aims to recognise exceptional lawyers who demonstrate both profound professional expertise and significant market influence, particularly in driving business development and earning client trust.
We would like to express our gratitude to China Business Law Journal and our clients for their ongoing support.
For further details, please contact our Partners, Heidi Chui and Rodney Teoh, or view the official report on the CBLJ website here.
 …
HKEX Publishes Consultation Paper on Enhancements to Board Lot Framework
9 January 2026
On 18 December 2025, Hong Kong Exchanges and Clearing Limited (“HKEX” or the “Exchange”) published a consultation paper on proposed enhancements to the board lot framework in the Hong Kong securities market (the “Consultation Paper”). The initiative, mandated by the HKSAR Government’s Task Force on Enhancing Stock Market Liquidity established in August 2023, aims to streamline trading, clearing and settlement processes while expanding investor participation.
The consultation period will run until 12 March 2026. Stakeholders are invited to submit feedback via HKEX’s online questionnaire, with a consultation conclusions paper tentatively (the “Consultation Conclusions”) scheduled for release by the end of the first half of 2026. This update breaks down the core proposals, their strategic rationale, and potential impacts on market participants.
A board lot is the standard number of shares required for a single transaction in the securities market, serving as a cornerstone of orderly trading and operational efficiency. Unlike most major global exchanges that adopt a single unified board lot unit, Hong Kong’s current framework is “issuer-led”, allowing each listed company to determine its own board lot size.
This approach has resulted in significant fragmentation. Currently, 44 distinct board lot units are in use, ranging from 10 shares to 100,000 shares. While 2,000 shares is the most common unit which is used by 25% of issuers, the 100-share unit accounts for the largest share of average daily turnover and market capitalisation.
This fragmentation has created multiple challenges:
(i) Operational inefficiencies: Complexity in trading, clearing and settlement processes;
(ii) Barriers to retail participation: Extremely high board lot values make certain securities
unaffordable for small investors, while low board lot values risk “negative value trades”
where execution costs exceed trade value; and
(iii) Misalignment with global practices: Divergence from international standards complicates
cross-market trading, particularly for Southbound Stock Connect investors familiar with
Mainland China’s unified 100-share board lot.
Additionally, Hong Kong’s market has a higher proportion of low-priced securities (56% of securities traded in the Hong Kong securities market (“Applicable Securities”) trade below HK$1.0) and fixed execution costs, making an immediate shift to a single unified board lot unit impractical due to the risk of widespread negative value trades.
3.1 Board Lot Value Floor and Ceiling Guidance
To balance accessibility and risk mitigation, HKEX proposes revising existing guidance and introducing a new ceiling:
(i) Reduction of board lot value floor guidance: HKEX proposes decreasing the existing board
lot value floor from HK$2,000 to HK$1,000. This adjustment reduces entry barriers without
increasing negative value trade risks. The floor applies only when issuers list or adjust board
lot units. No action is required if stock price movements push values below HK$1,000.
(ii) Introduction of board lot value ceiling guidance: HKEX proposes to introduce board lot
value ceiling at HK$50,000, applicable only to issuers using units larger than 100 shares. The
ceiling encourages issuers to split units to maintain accessibility.
3.2 Standardisation of board lot units
HKEX proposes reducing the number of permissible board lot units to eight board lot options (i.e., 1, 50, 100, 500, 1,000, 2,000, 5,000, and 10,000 share(s)), covering diverse price bands from HK$0.1 to HK$1,000+ per share. The proposed new board lot framework would result in 657 securities needing to change board lot units, representing approximately 25% of the 2,680 Applicable Securities. The standardised set supports future convergence to a single unit by encouraging gradual adoption of smaller units.
3.3 Phased Implementation Aligned with the Uncertificated Securities Market (“USM”)
To minimise market disruption, the framework will be rolled out in two phases, coordinated with HKEX’s USM initiative which replaces physical share certificates with electronic records:
Phase One:
(i) New issuers: Must adopt the eight standardised units and comply with the HK$1,000
floor/HK$50,000 ceiling upon listing.
(ii) Existing issuers: No immediate unit standardisation required. Only need to adhere to the
HK$1,000 floor/HK$50,000 ceiling guidelines.
Phase Two: Existing issuers must adopt one of the standardised units within a specified period after transitioning to USM. This aims at avoiding reprint physical share certificates and optimising issuer resources.
A detailed implementation timeline may be included in the Consultation Conclusions Paper.
The proposed enhancements will have distinct impacts on key market stakeholders:
Approximately 25% of listed issuers will need to revise their board lot units to one of the eight standardised options. In the long term, these reforms will reduce operational complexity and better align with the needs of global and international investors—particularly for “A+H share” issuers seeking consistency across Mainland China and Hong Kong markets. Issuers must continuously monitor their board lot values to ensure compliance with the HK$50,000 ceiling applicable to units exceeding 100 shares.
Investors will benefit from lower entry barriers, expanding access to high-quality securities, reducing concentration risk, and enabling portfolio diversification. Institutional investors will find trading, hedging and settlement processes simplified by standardised units, lowering operational costs and the risk of errors.
Fewer board lot units significantly enhance the operational efficiency of brokers and intermediaries by streamlining system configurations, order entry, and client onboarding processes. Reduced odd lot creation and clearer value guidelines help mitigate operational and settlement risks, strengthening risk management. Additionally, standardised board lots simplify the management of associated products, whose terms are often linked to the underlying securities’ board lot units, eliminating the need for complex adjustments.
The consultation period runs until 12 March 2026, and all interested parties—including issuers, brokers, institutional and retail investors, legal and compliance professionals, and investor advocacy groups—are strongly encouraged to submit feedback via the Exchange’s online questionnaire.
Given the transformative nature of these proposals, stakeholders are urged to:
(i) review the Consultation Paper in full (available on HKEX’s website);
(ii) provide detailed, data-driven feedback by 12 March 2026 to shape the final rules; and
(iii) prepare for phased implementation, particularly aligning systems and processes with USM
transition timelines.
The success of this reform will depend on balancing operational efficiency, investor accessibility and issuer flexibility, ensuring Hong Kong’s securities market remains dynamic, inclusive and aligned with global best practices.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
In the dynamic landscape of Hong Kong’s financial markets, the Securities and Futures Commission (“SFC”) serves as the primary regulator. For market participants, including licensed corporations, directors, and investment managers, understanding the breadth of the SFC’s powers is not just a compliance exercise, but a critical component of risk management. For a layman, it is equally important to understand what legal responsibility and implications could entail should you receive any enquiry or request from the SFC, hence protecting your legal position.
Recent enforcement trends and court decisions in late 2025 have reinforced a clear message: the SFC’s investigative powers are extensive, it has little patience for non-compliance, and it does not hesitate to exercise its enforcement toolkit.
Section 183: The Power to Investigate
The cornerstone of the SFC’s authority lies in Section 183 of the Securities and Futures Ordinance (Cap. 571, “SFO”). This section empowers the SFC to compel any person – not just the subject of the investigation – to provide information in the context of an investigation under Section 182 of the SFO.
Unlike in police investigations, where your right to silence is fundamental, the SFO significantly abrogates this right. If you receive a Section 183 notice, you are legally obligated to:
Crucially, you cannot refuse to answer on the grounds of self-incrimination. While you can claim privilege to prevent your answers from being used against you in criminal proceedings, those same answers can still be used in civil or disciplinary actions, or to lead investigators to other admissible evidence.
The Trap of Secrecy
A common pitfall for those under investigation is the Section 378 secrecy provision. Upon receiving a notice, you are essentially bound by a strict statutory “gag order”. You must not disclose the existence of the investigation or the notice to anyone, including your colleagues, spouse, or employer, without the SFC’s express consent.
The only major exception is disclosing the information to your lawyer for the purpose of seeking legal advice. Breaching this secrecy is a criminal offence in itself, exposing one to be prosecuted independently of the underlying misconduct.
Recent Case Law: No Excuses for Non-Compliance
The High Court’s judgment in October 2025 in SFC v. oOo Securities (HK) Group Limited [2025] HKCFI 4584 serves as a stark reminder of the consequences of ignoring these obligations.
In this case, a licensed corporation failed to comply with Section 183 notices, citing a change in management and the loss of records during a relocation to Beijing. The Court rejected these defences, holding that:
The Court ordered the firm to comply and ruled that they were liable for penalties, paving the way for fines. This confirms that the SFC will use Section 185 to seek court orders and punish those who treat regulatory notices lightly.
The Multi-Track Enforcement Regime
Once an investigation concludes, the SFC has ample choices within its arsenal to further pursue against the wrongdoer(s). The SFC operates a dual-track system, allowing it to pursue misconduct through civil, criminal, or disciplinary routes depending on the severity of the case.
Scrutiny on Asset Managers
The SFC has also sharpened its focus on the asset management sector. Following a circular in October 2024, the regulator has been rigorously inspecting private fund managers for “substandard conduct,” particularly regarding conflicts of interest and risk management.
Common deficiencies identified include using fund assets to finance related entities, prioritizing staff redemptions over clients, and inappropriately valuing assets to hide losses. Managers-In-Charge and Responsible Officers should be aware that they bear primary responsibility for these failures.
Conclusion
Compliance with the SFO is not optional. As the oOo Securities case demonstrates, internal administrative hurdles or staffing changes are no defence against statutory obligations.
If you or your firm receives a Section 183 notice or is subject to an inspection, immediate legal advice is essential to navigate the delicate balance between cooperation, privilege, and secrecy.
At Stevenson, Wong & Co., our regulatory and compliance team has extensive experience advising listed companies, licensed corporations and individuals on SFC investigations, disciplinary proceedings, and compliance strategy. We can assist you in:
To discuss how we can assist you, please contact our Ms. Rainbow Ip, Mr. Kenneth Leung or Mr. Ronnie Tse.
This article is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
The subsequent arrests of platform operators and numerous high-profile influencers have exposed a new and hazardous regulatory environment for influencers, marketing agencies, and maybe even licensed corporations that associate with them. The red lines between marketing and criminal conduct are now being drawn by prosecutors. This incident not only highlights vulnerabilities in investor protection but also marks a pivotal moment in how Hong Kong authorities will police the promotion of high-risk investments.
This development does not exist in a vacuum. It echoes the enforcement trend on financial commentators we analysed in our recent newsletter, “What ‘Finfluencers’ should not do. The SFC is Watching!“. In that article, we detailed the SFC’s crackdown on individuals carrying on a business of “advising on securities” (i.e. Type 4 regulated activity) without a licence, a crackdown that resulted in the first-ever custodial sentence for an unlicensed ‘finfluencer’.
The JPEX case involves a different legal framework—the virtual asset service provider (“VASP”) regime under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance (“AMLO”)—but the policy goal is identical: to stamp out the unlicensed promotion of high-risk investments to the public. The legal “traps” , however, are new and much more expansive.
The key legal distinction is the underlying asset. The ‘finfluencer’ prosecutions relate to providing advice on securities (stocks), which is a licensed activity under the Securities and Futures Ordinance (“SFO”).
The JPEX platform, however, primarily dealt in virtual assets, such as Bitcoin. Therefore, the promoters’ liability stems from the new VASP regime under the AMLO. This regime introduces specific criminal offences that directly target promoters.
Under the new AMLO VASP regime, it is a specific offence for any person to “issue advertisements” of an unlicensed VASP to the Hong Kong public.[3]
Hence, as long as the VASP is to the promoter’s knowledge unlicensed, a mere disclaimer of “this is not financial advice” is useless. The question that matters is: “Is the platform licensed by the SFC?” If the promoter knows that the platform is not on the SFC’s list of licensed VATPs, any promotion of it to the Hong Kong public would be a criminal offence. In the JPEX case, the platform was unlicensed, and its promoters were allegedly making false claims that it had applied for a licence.[4]
The AMLO has also introduced a powerful new anti-fraud provision: an offence for any person to “fraudulently or recklessly induce others to invest in virtual assets”. This carries a maximum penalty of 7 years’ imprisonment and a HK$1 million fine.[5]
“Fraudulently” is clear: essentially, it means lying, such as by repeating false claims of licensure. The more dangerous word for promoters is “recklessly”.
For “recklessly”, a near-identical provision in the SFO (s. 107) could provide an analogy for interpretation. In this regard, a promoter might act “recklessly” if they:
This provision effectively nullifies the “DYOR” (Do Your Own Research) disclaimer. The law now places the burden on the promoter to conduct their own diligence. Promoting an unlicensed, high-yield product without verifying its claims, could well fall within the definition of recklessness.
Finally, promoters may be charged with the common law offence of ‘conspiracy to defraud‘. This charge, which carries a maximum sentence of 14 years[6], may apply where there is an agreement to use dishonest means to put investors’ economic interests at risk.
When a promoter agrees with an unlicensed platform to read a misleading script, promote unjustified returns, and drive public investment, the prosecution can argue they are no longer a marketer, but rather a co-conspirator.
The parallel enforcement actions under the SFO (for securities) and the AMLO (for virtual assets) appear to reveal a new, unified regulatory posture:-
With the now expanded regulatory perimeter, all parties must ensure they do not cross the line between marketing and criminal solicitation. It is vital that all entities in this ecosystem review their compliance frameworks, influencer engagement policies, and client onboarding processes immediately.
At Stevenson, Wong & Co., our regulatory and compliance team has extensive experience advising clients on their obligations under both the SFO and the new AMLO VASP regime. To discuss how these new risks impact your business, please contact our Ms. Rainbow Ip or Mr. Kenneth Leung.
[1] https://news.rthk.hk/rthk/en/component/k2/1830269-20251105.htm
[2] https://www.acrc.hku.hk/Case/Detail/2212
[3] AMLO s 53ZRE
[4] https://www.sfc.hk/en/News-and-announcements/Policy-statements-and-announcements/Statement-on-JPEX
[5] AMLO s 53ZRG
[6] Crimes Ordinance (Cap. 200) s 159C(6)
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
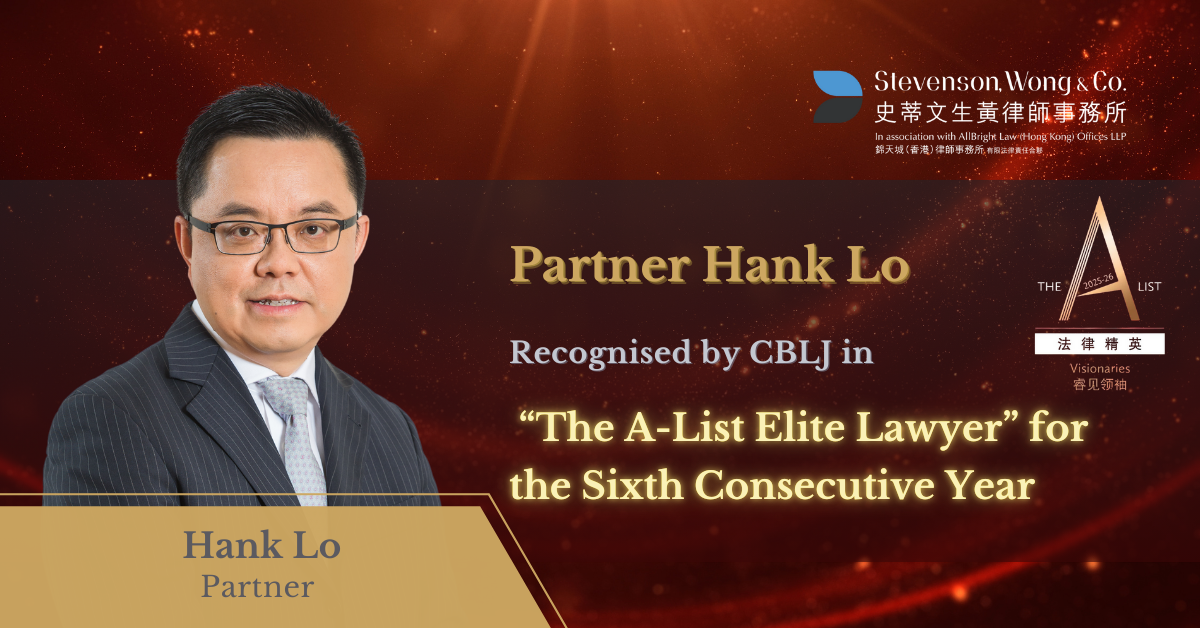 …
We are honoured to announce that Partner and Head of the Corporate Finance Department, Hank Lo, has once again been named one of “The A-List Elite Lawyers” by the prestigious legal publication, China Business Law Journal (CBLJ).
This distinction marks the sixth consecutive year that Mr. Lo has received this accolade. Following his inclusion in 2024, he has once again been listed in the highest tier, the “Visionaries” category, underscoring his exceptional professional expertise and leadership within the industry.
The CBLJ “The A-List Elite Lawyers” list aims to honour top lawyers who have made significant contributions to the China market and China-related business. The selection process is based on extensive market research, incorporating thousands of nominations and independent evaluations from in-house counsel, company executives, and legal professionals.
The list is divided into three categories: “Visionaries,” “Growth Drivers,” and “Rising Stars.” The “Visionaries” category specifically celebrates senior legal leaders who excel both within their firms and across the broader industry. These elite individuals typically hold pivotal roles such as managing partners or department heads, leveraging their strategic foresight to contribute to the advancement of the legal profession.
Mr. Lo possesses over three decades of extensive experience in capital markets, corporate finance, mergers and acquisitions, and corporate compliance. Recently, he has been admitted to practise as a solicitor in the United Arab Emirates and actively expanding the firm’s legal services into the UAE and the Middle East to facilitate Chinese enterprises with their “going global” strategies and international expansion.
We extend sincere gratitude to CBLJ for this recognition and offer most heartfelt thanks to our clients for their unwavering trust and support.
For further details, please contact our Partner, Hank Lo, or view the official report on the CBLJ website here.