
最新动态
有关本所的最新动态和活动,请浏览以下内容。如有兴趣个别了解,请点击此处与我们联系。
最新动态
有关本所的最新动态和活动,请浏览以下内容。如有兴趣个别了解,请点击此处与我们联系。
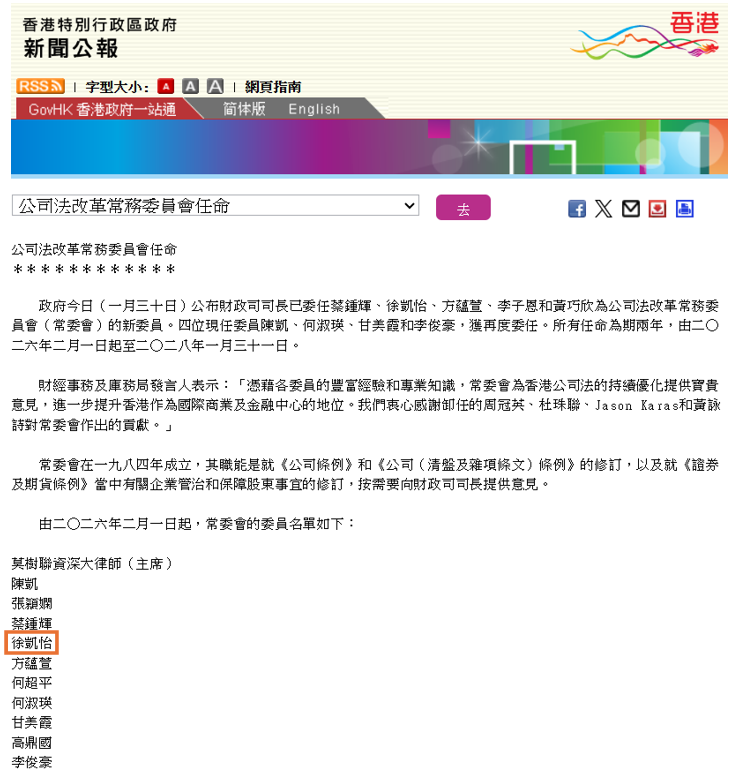
本所欣然宣布,本所合伙人、银行与金融部及诉讼及争议解决部主管徐凯怡律师,获财政司司长委任为公司法改革常务委员会委员。是次委任由2026年2月1日起生效,为期两年。
 …
公司法改革常务委员会是香港财经事务及库务局辖下的重要咨询组织,其职能就《公司条例》和《证券及期货条例》等条例修订向政府提供专业意见。委员会致力于构建清晰、高效且稳健的法律框架,以优化企业营运环境,进一步巩固香港作为国际商业及金融中心的领先地位。
徐律师是香港律师会理事、大中华法律事务委员会副主席及仲裁委员会委员;同时担任香港国际仲裁中心理事和香港国际仲裁中心仲裁女性俱乐部 (WIA) 委员。徐律师多获多家知名仲裁机构委任为仲裁员及调解员,包括香港国际仲裁中心、中国国际经济贸易仲裁委员会、上海国际仲裁中心、华南(香港)国际仲裁院、亚非法协(香港)、北京仲裁委员会/北京国际仲裁中心等。此外,她亦是广东省高级人民法院﹑深圳前海合作区人民法院的特邀调解员。
徐律师拥有粤港澳大湾区执业律师资格及中国委托公证人身份,并为英国特许仲裁司学会院士。
如阁下有查询或想了解更多详情,请联络本所合伙人徐凯怡律师,或按此查看香港政府之新闻公报。
 …
史蒂文生黄律师事务所欣然宣布,合伙人﹑银行及金融部和诉讼及争议解决部主管徐凯怡律师﹐以及合伙人、企业融资部副主管、金融科技部联席主管张源辉律师,凭借其卓越的专业表现和客户的高度评价,荣登《商法》(China Business Law Journal)“The A-List 法律精英:2025-26年度中国业务律界精锐” 榜单。
这项殊荣再次肯定了两位律师在各自专业领域的持续领先地位。徐凯怡律师已是连续第五年荣获《商法》「The A-List 法律精英」的肯定;而张源辉律师亦是连续第三年获此殊荣。
《商法》“The A-List 法律精英”榜单的评选基于数千份来自企业法务、高管及法律同行的提名与独立调研,具有高度的行业公信力。其中“律界精锐”类别旨在表彰兼具精深专业素养与卓越市场影响力的杰出律师,其在推动业务发展、赢得客户信赖方面表现尤为突出。
本所谨此感谢《商法》与各界客户的长期支持,本所将继续以专业实力为依托,为客户提供跨领域、跨法域的优质法律服务。
(English)  …
HKEX Publishes Consultation Paper on Enhancements to Board Lot Framework
9 January 2026
On 18 December 2025, Hong Kong Exchanges and Clearing Limited (“HKEX” or the “Exchange”) published a consultation paper on proposed enhancements to the board lot framework in the Hong Kong securities market (the “Consultation Paper”). The initiative, mandated by the HKSAR Government’s Task Force on Enhancing Stock Market Liquidity established in August 2023, aims to streamline trading, clearing and settlement processes while expanding investor participation.
The consultation period will run until 12 March 2026. Stakeholders are invited to submit feedback via HKEX’s online questionnaire, with a consultation conclusions paper tentatively (the “Consultation Conclusions”) scheduled for release by the end of the first half of 2026. This update breaks down the core proposals, their strategic rationale, and potential impacts on market participants.
A board lot is the standard number of shares required for a single transaction in the securities market, serving as a cornerstone of orderly trading and operational efficiency. Unlike most major global exchanges that adopt a single unified board lot unit, Hong Kong’s current framework is “issuer-led”, allowing each listed company to determine its own board lot size.
This approach has resulted in significant fragmentation. Currently, 44 distinct board lot units are in use, ranging from 10 shares to 100,000 shares. While 2,000 shares is the most common unit which is used by 25% of issuers, the 100-share unit accounts for the largest share of average daily turnover and market capitalisation.
This fragmentation has created multiple challenges:
(i) Operational inefficiencies: Complexity in trading, clearing and settlement processes;
(ii) Barriers to retail participation: Extremely high board lot values make certain securities
unaffordable for small investors, while low board lot values risk “negative value trades”
where execution costs exceed trade value; and
(iii) Misalignment with global practices: Divergence from international standards complicates
cross-market trading, particularly for Southbound Stock Connect investors familiar with
Mainland China’s unified 100-share board lot.
Additionally, Hong Kong’s market has a higher proportion of low-priced securities (56% of securities traded in the Hong Kong securities market (“Applicable Securities”) trade below HK$1.0) and fixed execution costs, making an immediate shift to a single unified board lot unit impractical due to the risk of widespread negative value trades.
3.1 Board Lot Value Floor and Ceiling Guidance
To balance accessibility and risk mitigation, HKEX proposes revising existing guidance and introducing a new ceiling:
(i) Reduction of board lot value floor guidance: HKEX proposes decreasing the existing board
lot value floor from HK$2,000 to HK$1,000. This adjustment reduces entry barriers without
increasing negative value trade risks. The floor applies only when issuers list or adjust board
lot units. No action is required if stock price movements push values below HK$1,000.
(ii) Introduction of board lot value ceiling guidance: HKEX proposes to introduce board lot
value ceiling at HK$50,000, applicable only to issuers using units larger than 100 shares. The
ceiling encourages issuers to split units to maintain accessibility.
3.2 Standardisation of board lot units
HKEX proposes reducing the number of permissible board lot units to eight board lot options (i.e., 1, 50, 100, 500, 1,000, 2,000, 5,000, and 10,000 share(s)), covering diverse price bands from HK$0.1 to HK$1,000+ per share. The proposed new board lot framework would result in 657 securities needing to change board lot units, representing approximately 25% of the 2,680 Applicable Securities. The standardised set supports future convergence to a single unit by encouraging gradual adoption of smaller units.
3.3 Phased Implementation Aligned with the Uncertificated Securities Market (“USM”)
To minimise market disruption, the framework will be rolled out in two phases, coordinated with HKEX’s USM initiative which replaces physical share certificates with electronic records:
Phase One:
(i) New issuers: Must adopt the eight standardised units and comply with the HK$1,000
floor/HK$50,000 ceiling upon listing.
(ii) Existing issuers: No immediate unit standardisation required. Only need to adhere to the
HK$1,000 floor/HK$50,000 ceiling guidelines.
Phase Two: Existing issuers must adopt one of the standardised units within a specified period after transitioning to USM. This aims at avoiding reprint physical share certificates and optimising issuer resources.
A detailed implementation timeline may be included in the Consultation Conclusions Paper.
The proposed enhancements will have distinct impacts on key market stakeholders:
Approximately 25% of listed issuers will need to revise their board lot units to one of the eight standardised options. In the long term, these reforms will reduce operational complexity and better align with the needs of global and international investors—particularly for “A+H share” issuers seeking consistency across Mainland China and Hong Kong markets. Issuers must continuously monitor their board lot values to ensure compliance with the HK$50,000 ceiling applicable to units exceeding 100 shares.
Investors will benefit from lower entry barriers, expanding access to high-quality securities, reducing concentration risk, and enabling portfolio diversification. Institutional investors will find trading, hedging and settlement processes simplified by standardised units, lowering operational costs and the risk of errors.
Fewer board lot units significantly enhance the operational efficiency of brokers and intermediaries by streamlining system configurations, order entry, and client onboarding processes. Reduced odd lot creation and clearer value guidelines help mitigate operational and settlement risks, strengthening risk management. Additionally, standardised board lots simplify the management of associated products, whose terms are often linked to the underlying securities’ board lot units, eliminating the need for complex adjustments.
The consultation period runs until 12 March 2026, and all interested parties—including issuers, brokers, institutional and retail investors, legal and compliance professionals, and investor advocacy groups—are strongly encouraged to submit feedback via the Exchange’s online questionnaire.
Given the transformative nature of these proposals, stakeholders are urged to:
(i) review the Consultation Paper in full (available on HKEX’s website);
(ii) provide detailed, data-driven feedback by 12 March 2026 to shape the final rules; and
(iii) prepare for phased implementation, particularly aligning systems and processes with USM
transition timelines.
The success of this reform will depend on balancing operational efficiency, investor accessibility and issuer flexibility, ensuring Hong Kong’s securities market remains dynamic, inclusive and aligned with global best practices.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
在香港金融市场瞬息万变的环境中,证券及期货事务监察委员会(“证监会”)担当主要的监管角色。对于市场参与者,包括持牌法团、董事和投资经理而言,了解证监会的权力不仅是一项合规工作,更是风险管理的关键一环。对于一般大众而言,了解当收到证监会的查询或要求时可能涉及的法律责任和后果,对于保障自身的法律权益同样至关重要。
2025年下半年的执法趋势和法院判决传达了一个明确的信息:证监会拥有广泛的调查权力,对违规行为几乎零容忍,并且会毫不犹豫地动用其执法工具。
第183条:调查权力
证监会权力的基石在于《证券及期货条例》(香港法例第571章)第183条。该条文授权证监会在根据《证券及期货条例》第182条进行调查时,强迫任何人——不仅仅是受调查对象——提供资料。
与警方调查中您享有的缄默权不同,《证券及期货条例》在很大程度上废除了这项权利。如果您收到第183条通知,您在法律上有义务:
关键在于,您不能以“免使自己入罪”为由拒绝回答。虽然您可以主张特权以防止您的回答在刑事诉讼中被用作针对您的证据,但这些回答仍可用于民事或纪律处分程序,或引导调查人员寻找其他可接纳的证据。
保密的陷阱
受调查人士面临的一个常见陷阱是第378条的保密条文。一旦收到通知,您实际上即受到严格的法定“封口令”约束。未经证监会明确同意,您不得向任何人(包括您的同事、配偶或雇主)披露调查的存在或通知本身。
唯一的主要例外是向您的律师披露调查事宜以寻求法律意见。违反此保密规定本身即属刑事罪行,即使与相关的不当行为无关,您也可能因此面临独立的检控。
近期判例:不合规无借口
高等法院于2025年10月就SFC v. oOo Securities (HK) Group Limited [2025] HKCFI 4584 一案作出的判决,赤裸裸地提醒我们忽视这些义务的后果。
在该案中,一家持牌法团未能遵守第183条通知,理由是管理层变动及在搬迁至北京期间遗失记录。法院驳回了这些抗辩理由,并裁定:
法院命令该行必须合规,并裁定其需承担罚款责任。这证实了证监会将利用第185条寻求法院命令,并惩处那些轻视监管通知的人士。
多重执法机制
一旦调查结束,证监会的“武器库”中有多种选择可供其进一步追究违规者的责任。证监会实行双重机制,可视乎案件的严重程度,通过民事、刑事或纪律处分途径处理失当行为。
加强对资产管理人的审查
证监会也加强了对资产管理行业的关注。继2024年10月发出一份通函后,证监会一直在严格视察私人基金管理人的“不达标情况”,特别是关于利益冲突和风险管理方面。
已发现的常见缺失包括利用基金资产为相关实体提供融资、在处理赎回时优先处理员工而非客户,以及采取不恰当的估值方法以掩饰投资亏损。核心职能主管及负责人员应意识到,他们需对这些失误承担主要责任。
结语
遵守《证券及期货条例》是必须的。正如 oOo Securities 案所示,内部行政障碍或人员变动并非违反法定义务的抗辩理由。
如果您或您的公司收到第183条通知或受到视察,立即寻求法律意见才可把握合作、特权和保密之间微妙的平衡。
史蒂文生黄律师事务所的监管及合规团队拥有丰富的经验,曾为众多上市公司、持牌法团及个人就证监会调查、纪律处分程序及合规策略提供法律咨询。我们可以协助您:
如欲讨论我们如何为您提供协助,请联系本所合伙人叶小铃律师、梁祺澧顾问律师或谢朗希律师。
本文仅供参考。其内容不构成亦不应视为法律咨询意见。史蒂文生黄律师事务所不会就任何因倚赖本处所载资料而作出的决定丶采取的行动或不采取的行动所引致的或与之有关的任何特别丶间接或相应而生的损失或损害向阁下承担法律责任。
 …
随后平台营运者及多名高知名度网红被捕,揭示了网红、营销机构,甚至与其有关联的持牌法团正面临一个全新且充满风险的监管环境。 检控部门正在划定营销与犯罪行为之间的红线。 这起事件不仅突显了投资者保护方面的漏洞,也标志着香港当局监管高风险投资推广方式的关键时刻。
这一发展并非凭空而来。这与我们在最近的快讯文章《金融网红应注意的红线?证监会正密切关注!》中分析的针对金融评论员的执法趋势相呼应。在该文章中,我们详述了证监会打击无牌经营「就证券提供意见」业务(即第 4 类受规管活动)的人士,该打击行动导致了首宗针对无牌「金融网红」判处监禁的案例。
JPEX 案涉及不同的法律框架——即《打击洗钱及恐怖分子资金筹集条例》(「《打击洗钱条例》」)下的虚拟资产服务提供者(「VASP」)制度——但政策目标是一致的:杜绝向公众无牌推广高风险投资。 然而,法律「陷阱」是新的,而且范围更广。
关键的法律区别在于牵涉的资产。「金融网红」的检控与就证券(股票)提供意见有关,这是受《证券及期货条例》规管的持牌活动。
然而,JPEX 平台主要从事比特币等虚拟资产的交易。 因此,推广者的法律责任源于《打击洗钱条例》下新的 VASP 制度。 该制度引入了直接针对推广者的具体刑事罪行。
根据新的《打击洗钱条例》VASP 制度,任何人士向香港公众「发出」无牌 VASP 的「广告」,即属犯罪。[3]
因此,只要推广者知悉该 VASP 未获发牌,单纯作出「这不是财务建议」的免责声明是无用的。 关键问题在于:「该平台是否已获证监会发牌?」如果推广者知道该平台不在证监会的持牌虚拟资产交易平台名单上,向香港公众进行任何推广都将构成刑事罪行。 在 JPEX 案中,该平台未获发牌,而其推广者据称作出了该平台已申请牌照的虚假声称。[4]
《打击洗钱条例》亦引入了一项强而有力的新反欺诈条文:任何人士「欺诈地或罔顾实情地诱使他人投资虚拟资产」即属犯罪。 这项罪行最高可判处 7 年监禁及罚款 100 万港元。[5]
「欺诈地」的意思很明确:本质上就是撒谎,例如重复关于已获发牌的虚假声称。 对推广者而言,更危险的字眼是「罔顾实情地」。
关于「罔顾实情地」,《证券及期货条例》中一条几近相同的条文(第 107 条)可作为解释的类比。 就此而言,如果推广者作出以下行为,可能会被视为「罔顾实情」:
这项条文效果是令「自己做研究」的免责声明失效。 法律现在将尽职审查的责任加诸于推广者身上。 推广未经许可的高收益产品而不核实其声称,很可能属于罔顾实情的定义范围。
最后,推广者可能会被控以普通法下的「串谋欺诈」罪。 这项控罪最高可判处 14 年监禁[6],适用于协议使用不诚实手段令投资者的经济利益蒙受风险的情况。
当推广者与无牌平台达成协议,朗读误导性的讲稿、推广不合理的回报并推动公众投资时,控方可以主张他们不再仅是营销人员,而是共谋者。
《证券及期货条例》(针对证券)和《打击洗钱条例》(针对虚拟资产)下的并行执法行动似乎揭示了一种全新且统一的监管姿态:-
随着监管范围的扩大,各方必须确保不越过营销与非法招揽之间的界线。 产业链中的所有实体都必须立即检讨其合规框架、网红聘用政策和建立客户关系的流程。
史蒂文生黄律师事务所的监管与合规团队在为客户就《证券及期货条例》及新的《打击洗钱条例》VASP 制度下的责任提供意见方面拥有丰富经验。如需了解更多服务详情,请联系本所合伙人叶小铃律师或梁祺澧顾问律师。
[1] https://news.rthk.hk/rthk/ch/component/k2/1830259-20251105.htm
[2] https://www.acrc.hku.hk/Case/Detail/2212
[3] 《打击洗钱条例》第53ZRE条
[4] https://www.sfc.hk/en/News-and-announcements/Policy-statements-and-announcements/Statement-on-JPEX
[5] 《打击洗钱条例》第53ZRG条
[6] 《刑事罪行条例》(第200章)第159C(6)条
本新闻简讯更新仅供参考。其内容不构成亦不应视为法律咨询意见。史蒂文生黄律师事务所不会就任何因倚赖本处所载资料而作出的决定丶采取的行动或不采取的行动所引致的或与之有关的任何特别丶间接或相应而生的损失或损害向阁下承担法律责任。
 …
本所荣幸宣布,合伙人及企业融资部主管劳恒晃律师凭借其卓越的专业专业实力和行业领导力,再次荣获知名法律媒体《商法》(China Business Law Journal)评选为「The A-List 法律精英」。
这项殊荣标志着劳恒晃律师连续第六年获此殊荣,也是继2024年后再度被列入最高级别的「睿见领袖」(Visionaries)类别,充分体现其在法律服务领域的持续领导地位。
《商法》「The A-List 法律精英」榜单旨在表彰在中国法律市场及涉华业务中作出重大贡献、备受客户推崇的顶尖律师。评选结果基于数千份来自企业法务、公司高管及法律专家的提名和独立调研。
该榜单分为三个类别:“睿见领袖”“律界精锐”和“律师新星”。其中「睿见领袖」类别专门表彰在律师事务所内外均表现卓越的资深法律领袖。这些精英通常身居管理合伙人或部门主管等关键职位,以其战略眼光引领业务创新,并积极参与行业协会和公共事务,为法律专业的发展贡献智慧。
劳恒晃律师在资本市场、企业融资、收购合并以及企业合规等领域拥有超过三十年的丰富经验。近期,劳律师亦已正式取得阿联酋律师执业资格,积极拓展法律服务至阿联酋及中东地区,协助中国企业出海发展。
“律界精锐”和“律师新星”类别的结果将在下一阶段公布。本所谨此感谢《商法》的认可,并向所有客户致以最诚挚的谢意,感谢他们一直以来的信任与坚定支持。