
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
 …
Stevenson, Wong & Co. acted as the Hong Kong legal adviser to US Tiger Securities, Inc. (the “Lead Underwriters”), the lead underwriters of DarkIris Inc. (NASDAQ: DKI) (“DarkIris”) in their successful listing on the Nasdaq Capital Market on 8 August 2025 (the “Nasdaq Listing”). DarkIris offered a total of 1,500,000 Class A Ordinary Shares, priced at US$4.00 per share. The aggregate gross proceeds from the Offering was US$6 million.
DarkIris is a comprehensive technology enterprise engaged in the development, publishing and operating of mobile digital games via various third-party digital storefronts. Through its subsidiaries in Hong Kong, DarkIris’s activities include game design, programming, graphics, distribution, and operation of mobile games on various platforms. DarkIris leverages (i) the innovative, creative, and technical expertise of the gaming industry communities in Hong Kong and (ii) the multicultural environment and diverse interests of mobile game players in these regions to create and promote a broader array of engaging, immersive, and captivating mobile game genres for a global audience of gamers.
Our Partners, Hank Lo and Gordon Tsang, and Associate Sam Liu, acted as the Hong Kong legal counsel for the Lead Underwriters in the Nasdaq Listing and provided comprehensive Hong Kong legal services.
Please contact Hank Lo or Gordon Tsang for any enquiries or further information about this transaction.
 …
Conclusions to IPO price discovery and open market reform proposals
Having considered the consultation responses with 1,253 respondents from all sectors, the Exchange will adopt the following key changes to the listing requirements:
Require an issuer to allocate at least 40% of its shares initially on offer in an IPO to its bookbuilding placing tranche.
Allow a new listing applicant to choose either Mechanism A or Mechanism B as its IPO offering mechanism:
| Initial allocation | Demand for shares in the public subscription tranche in number of times (x) the initial allocation | |||
| ≥15x to <50x | ≥50x to <100x | ≥100x | ||
| Percentage of offer shares allocated to the public subscription tranche | 5% | 15% | 25% | 35% |
Require issuers to meet the following minimum public float and free float requirements at the time of listing:
| Initial public float thresholds | Initial free float thresholds | |
| Issuers (not incorporated in Mainland China) with a single class of shares | Tiered percentage thresholds ranging between 10% and 25% depending on the market value of the relevant class of shares at listing | 10%, with a market value of HK$50 million (GEM: HK$15 million); OR HK$600 million in market value |
| H-share issuers with no other listed shares | ||
| A+H issuers | 10%; OR
HK$3 billion in market value |
5% with a market value of HK$50 million (GEM: HK$15 million); OR HK$600 million in market value |
The new requirements will come into effect on 4 August 2025 and apply to all issuers and all new applicants with listing documents published on or after that date.
Further consultation on ongoing public float proposals
In response to market feedback on the appropriate ongoing public float requirements, the Exchange is also launching a further consultation on detailed proposals on those requirements.
| Current requirement |
Proposed requirement | |
| Ongoing public float thresholds | ||
| · Issuers (not incorporated in Mainland China) with a single class of shares | Maintain at all times the percentage of public float prescribed at listing, i.e. 25% or any lower percentage prescribed at listing (the Initial Prescribed Threshold) | Maintain at all times: 1. The Initial Prescribed Threshold; OR 2. the Alternative Threshold of HK$1 billion in value and 10% public float |
| · H-share issuers with no other listed shares | ||
| · A+H issuers | H shares in public hands must have HK$1 billion in value OR 5% public float | |
| Public float shortfall | Breach of Listing Rules if public float falls below the applicable ongoing public float thresholds | |
| Consequence of public float shortfall | ||
| · Obligations upon breach | Obliged to restore public float and publish announcement | Obliged to restore public float and publish announcement; AND Restricted from taking actions that may further lower public float percentage |
| · Trading suspension | Exchange reserves right to direct trading suspension in case of a public float shortfall | No suspension solely due to a public float shortfall |
| · Delisting mechanism | Delisting if trading is suspended for 18 months (GEM: 12 months) | Impose stock marker if issuer has a significant public float shortfall; AND
Delisting if issuer fails to restore public float within 18 months (GEM: 12 months) |
| Public float reporting | Confirm public float sufficiency in annual reports | Confirm public float sufficiency in monthly returns and annual reports, with additional actual public float disclosure requirements |
The public comment period ends on 1 October 2025.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
 …
Stevenson, Wong & Co. acted as the Hong Kong legal adviser to Mega Fortune Company Limited (NASDAQ: MGRT) (“MGRT”) in the successful listing on the Nasdaq Capital Market on 16 July 2025 (the “Nasdaq Listing”). MGRT offered a total of 3,750,000 ordinary shares, priced at US$4.00 per share (the “Offering”). The aggregate gross proceeds from the offering was US$15 million.
MGRT is an Internet of Things (“IoT”) solution provider in Hong Kong. Through its operating subsidiary QBS System Limited (“QBS System”), MGRT has specialized in delivering comprehensive IoT solutions and services across various industries. QBS System’s business service portfolio includes the provision of IoT Integration Solution Services, IoT Maintenance and Support services, Business Process Outsourcing services and trading sales. Through its IoT platform, tools and services, QBS System helps enterprises through their digital transformation, launch IoT initiatives, upscale an existing IoT application or integrate any IoT solution with a legacy system to help them become more innovative, effective and productive. MGRT’s vision is to become the preferred choice for IoT solutions for enterprises and projects in the Asia-Pacific region.
Our Partners, Mr. Hank Lo and Mr. Gordon Tsang, acted as the Hong Kong legal counsel for MGRT in the Nasdaq Listing.
Please contact Mr. Hank Lo or Mr. Gordon Tsang for any enquiries or further information about this transaction.
 …
Our Partner, Gordon Tsang, has been appointed as a member of the panel of adjudicators for the Obscene Articles Tribunal by the Chief Justice. This appointment is effective from June 17, 2025, and will span a term of three years.
The Obscene Articles Tribunal, consisting of a Presiding Magistrate and two or more adjudicators, carries out two main tasks with respect to articles and matters – classification and determination.
For any enquiries, please contact our Partner Gordon Tsang.
 …
The Hong Kong[1] Government has confirmed that the Stablecoins Ordinance will take effect on 1 August 2025,[2] requiring issuers of fiat-referenced stablecoins in Hong Kong or those pegged to the Hong Kong dollar (“HKD”) to be licensed by the Hong Kong Monetary Authority (“HKMA”).
Overview of the Stablecoins Ordinance
The Stablecoins Ordinance aligns Hong Kong’s virtual assets regulatory framework with international standards under the “same activity, same risks, same regulation” principle.
The Stablecoins Ordinance sets out a regulatory framework for activities relating to “specified stablecoins” (“Specified Stablecoins”). Specified Stablecoins, as a type of virtual assets used as a medium of exchange, maintain a stable value with reference to one or more official currencies, such as the HKD, or a digital representation of value.[3] Issuers of Specified Stablecoins in Hong Kong must obtain a licence from the HKMA and continue to comply with the comprehensive requirements.
Key Provisions of the Licensing Regime
The Stablecoins Ordinance introduces a comprehensive regulatory framework for the issuance, offering, and marketing of Specified Stablecoins. Below are the key provisions: –
Licensing Requirement
Any person engaging in the following activities must obtain a license from the HKMA: –
Requirements of Licensed Issuers
To obtain a licence from the HKMA for issuing Specified Stablecoins, applicants must satisfy, including but not limited to, the following minimum criteria: – [4]
Offering Restrictions The Stablecoins Ordinance regulates not only the issuance of Specified Stablecoins, but also who can offer Specified Stablecoins, including but not limited to: –
Under the new regime, Specified Stablecoins issued by HKMA-licensed issuers can be offered to retail investors; others are restricted to professional investors or exempted persons designated by the HKMA or Financial Secretary. Transitional Arrangements Existing stablecoin issuers (“Issuers”) have a three-month period from 1 August 2025 (“Effective Date”) to apply for a licence, during which they may continue regulated stablecoin activities without immediate penalty. Issuers meeting the following conditions may receive a six-month extension: –
Issuers failing to apply within three months will enter a one-month wind-down period starting three months after the Effective Date. Issuers whose applications are rejected or withdrawn will enter a one-month wind-down period from the date of rejection or withdrawal, with the option to apply for an extension.AML/CFT Requirements On 26 May 2025, the HKMA released a consultation paper outlining proposed AML/CFT requirements for regulated stablecoin activities. Key proposals include, but are not limited to: –
Feedback on these proposals is due by 30 June 2025.Implications for the Virtual Asset Industry Enhanced Investor Confidence: The stringent licensing requirements, including reserve asset segregation and AML/CFT compliance, provide greater assurance to investors, reducing the risk of fraud and financial instability.
Conclusion The Stablecoins Ordinance, set to take effect on 1 August 2025, represents a significant step forward in Hong Kong’s digital finance journey. By balancing innovation with robust regulation, the Stablecoins Ordinance enhances market integrity, protects consumers, and positions Hong Kong as a competitive player in the global virtual asset landscape. Collaboration between regulators, issuers, and industry stakeholders will be essential to ensure a smooth transition and sustainable growth in Hong Kong’s stablecoin ecosystem.For issuers, compliance with the Stablecoins Ordinance will require significant investment in legal, operational, and financial systems, especially regarding reserve asset management and AML/CFT controls. While this may raise barriers to entry for smaller or less well-capitalised firms, it is expected to enhance overall market credibility and attract established financial institutions and global fintech companies to the Hong Kong market.For investors and users, the new licensing and supervisory requirements are designed to boost confidence in the safety and reliability of stablecoins available in Hong Kong, particularly for retail users who will have access only to products issued by HKMA-licensed entities.Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.[1] In this article, “Hong Kong” means the “Hong Kong Special Administrative Region of the People’s Republic of China”.[2] On 21 May 2025, the Legislative Council of Hong Kong passed the Stablecoins Bill; “Stablecoins laws effective Aug 1”.[3] Section 4 of the Stablecoins Ordinance[4] Schedule 2 Part 2 of the Stablecoins Ordinance
| Requirement | Details |
| Corporate Structure | The applicant must be a company, or an authorized institution incorporated outside Hong Kong. |
| Financial Resources | The applicant must have a minimum paid-up share capital of HK$ 25 million or its equivalent, and adequate liquid assets. |
| Reserve Assets
|
The applicant must establish an effective stabilisation mechanism for its Specified Stablecoins, maintaining a pool of reserve assets at least equal to the par value of the stablecoins in circulation, which is segregated from any other pool of reserve assets, ensuring high quality and liquidity, and allowing timely redemptions at par value without excessive fees. |
| Redemption | Process redemption requests of the Specified Stablecoins by holders at par value without undue delay and without having to face burdensome conditions and fees. |
| AML/CFT Compliance | Implement effective anti-money laundering and counter-terrorist financing (“AML/CFT”) systems and controls. |
| Disclosure and Auditing | Provide sufficient and timely disclosures to the public regarding reserve asset management policies, risk assessments, composition, and market value, and undergo regular independent verification and audits. |
| Fitness and Propriety | Ensure key personnel, including controllers, chief executives, directors, and stablecoin managers, meet the HKMA’s fitness and propriety standards. |
| Local Presence | Maintain a physical presence in Hong Kong for regulatory oversight. |
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
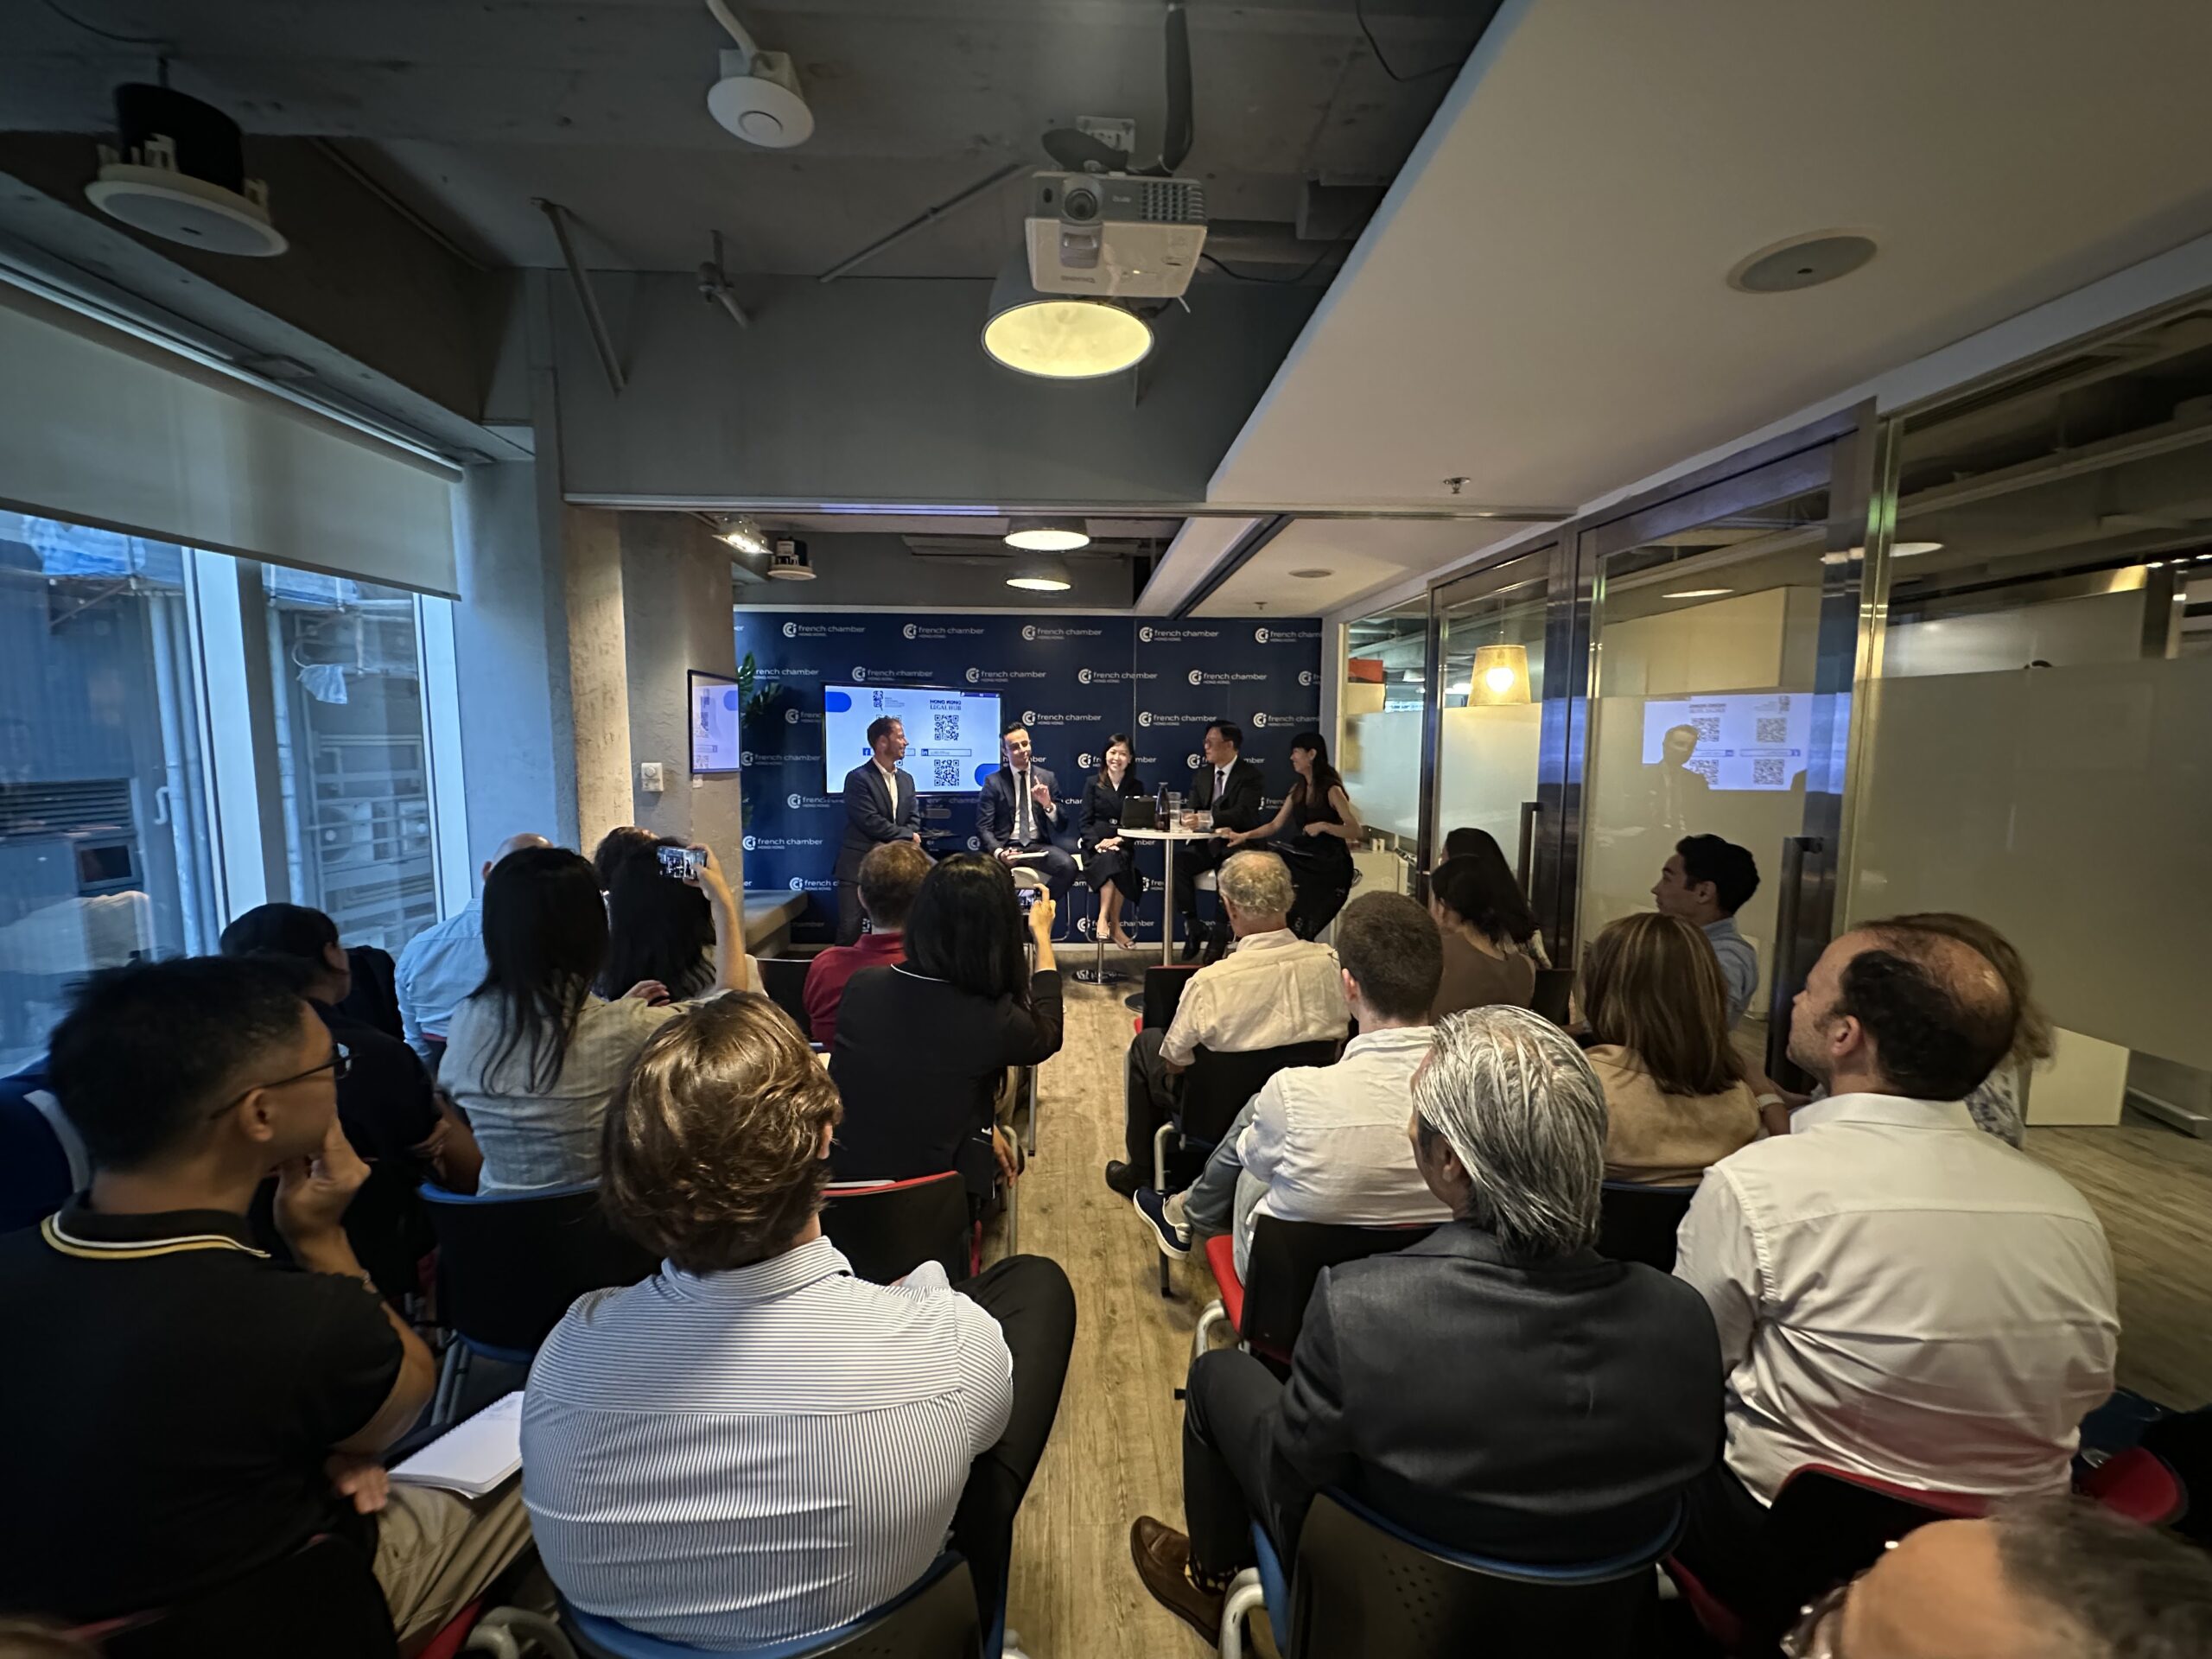
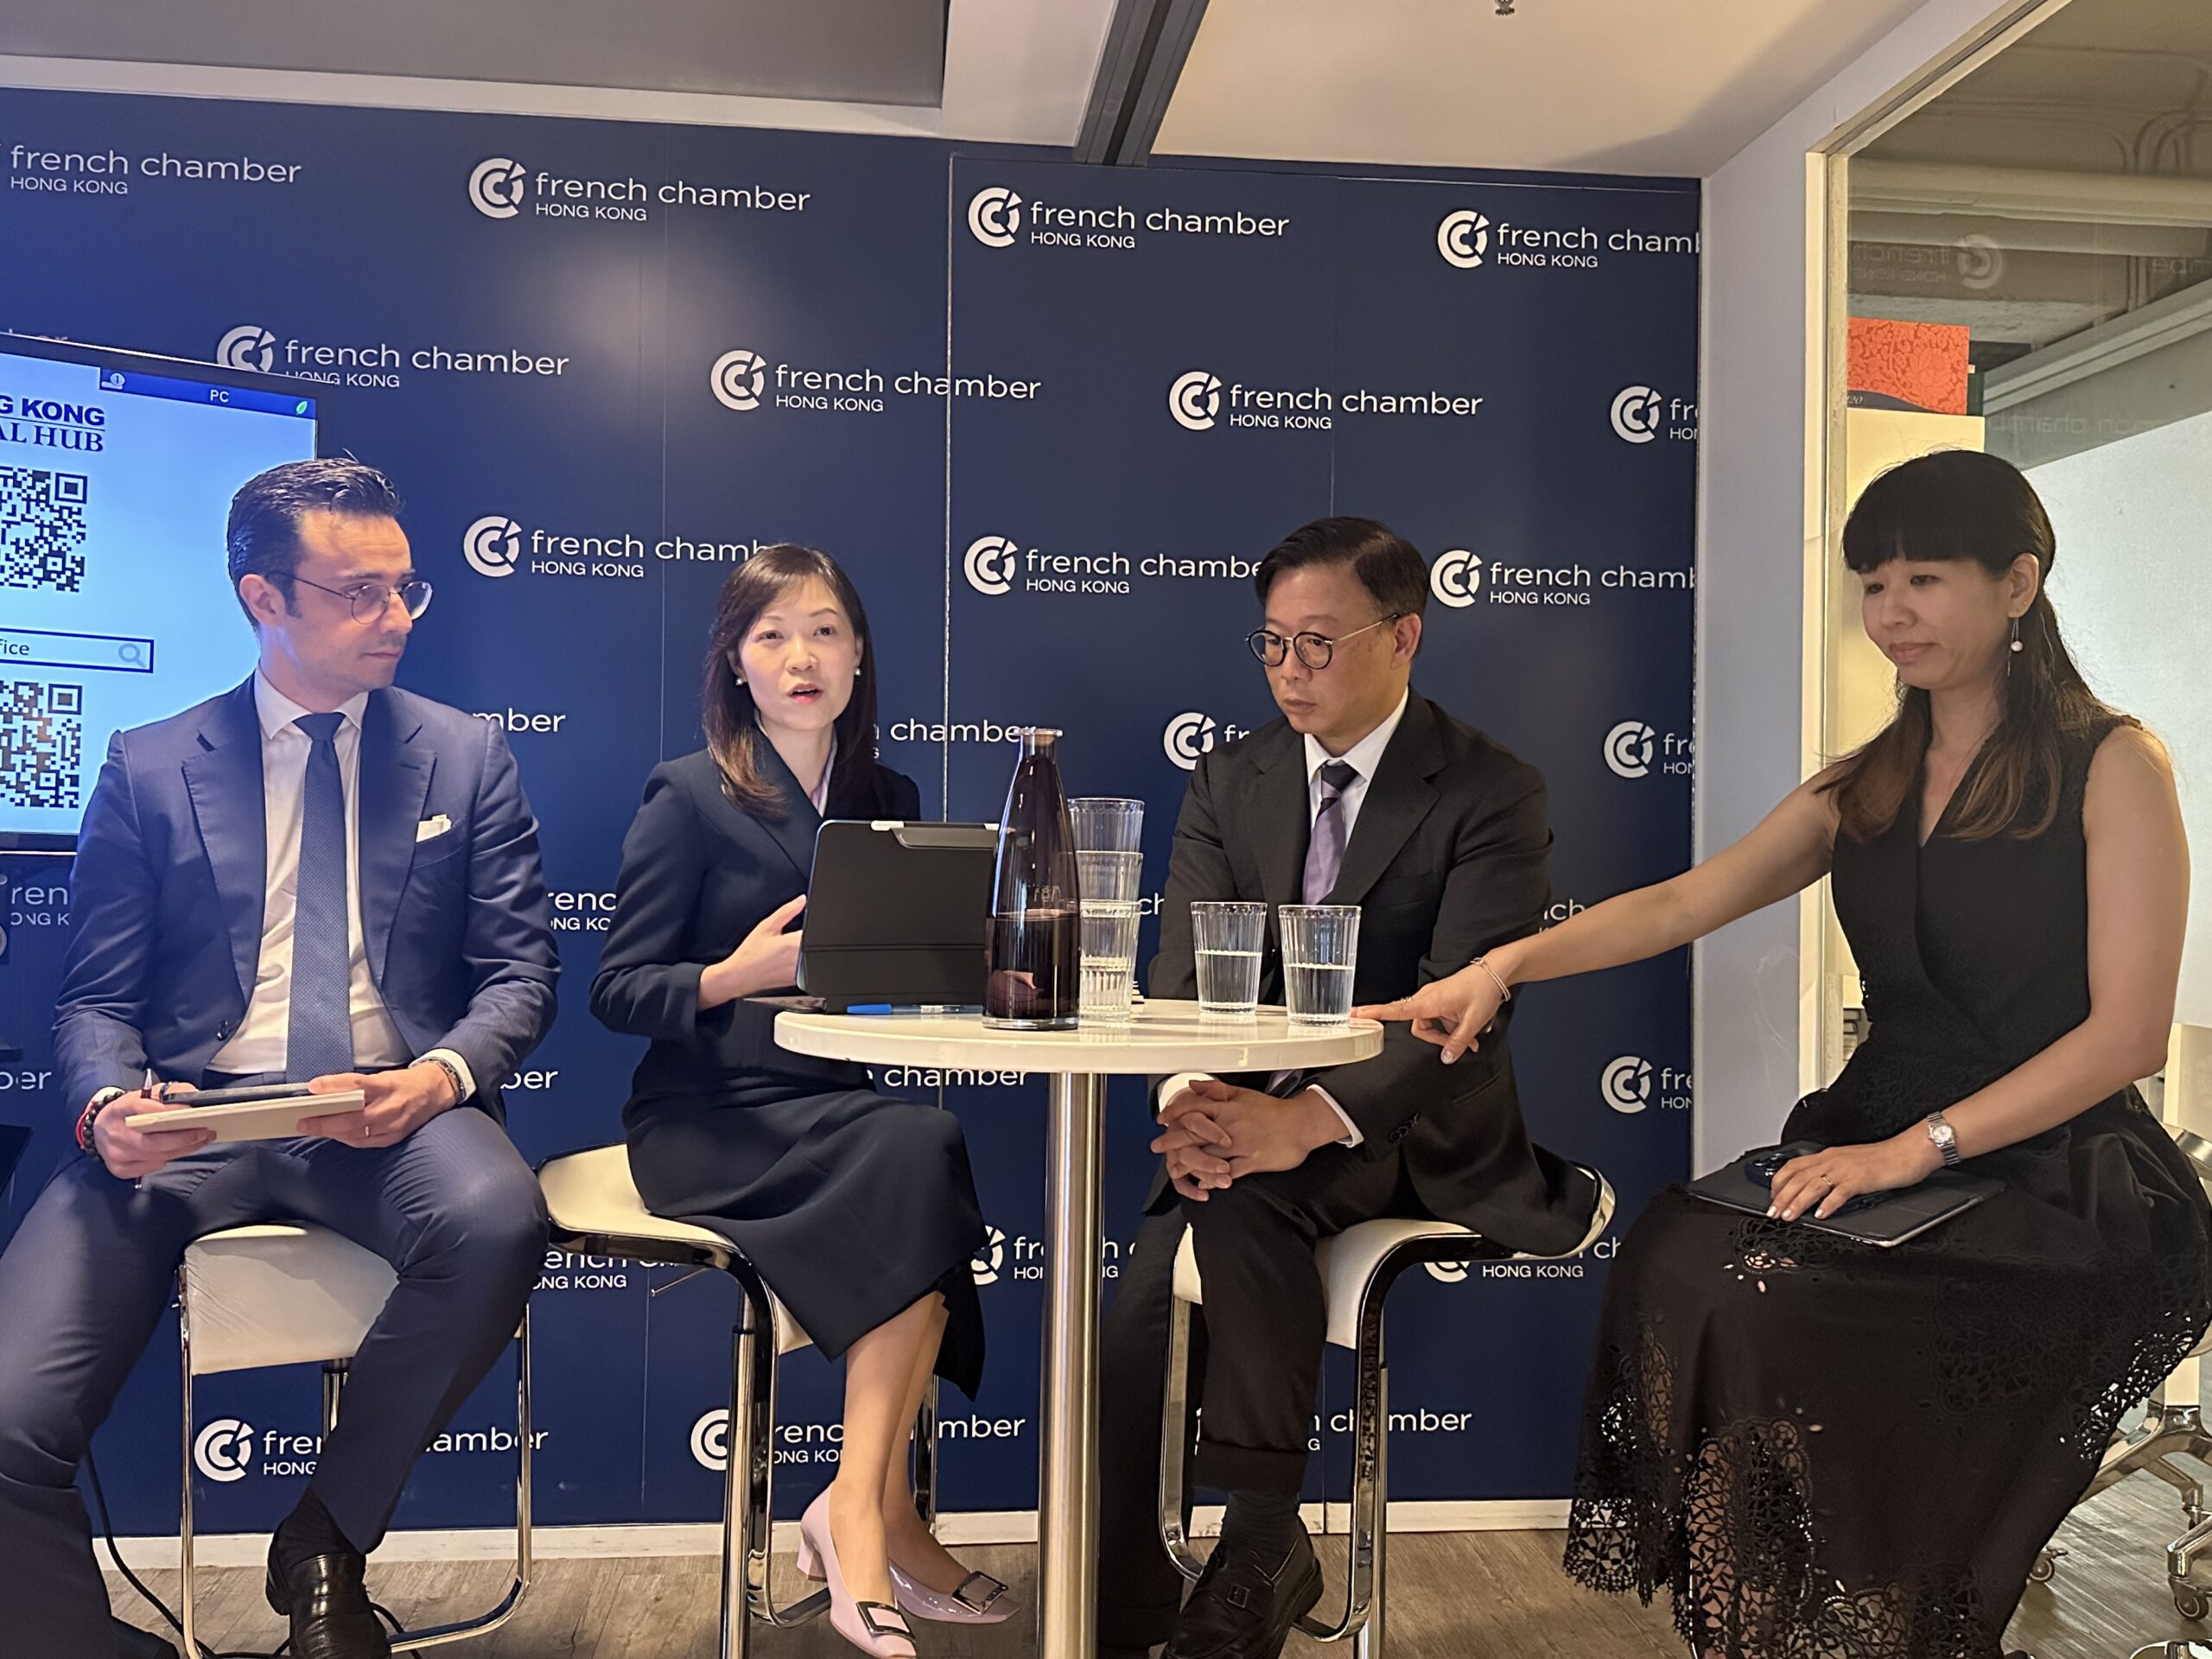
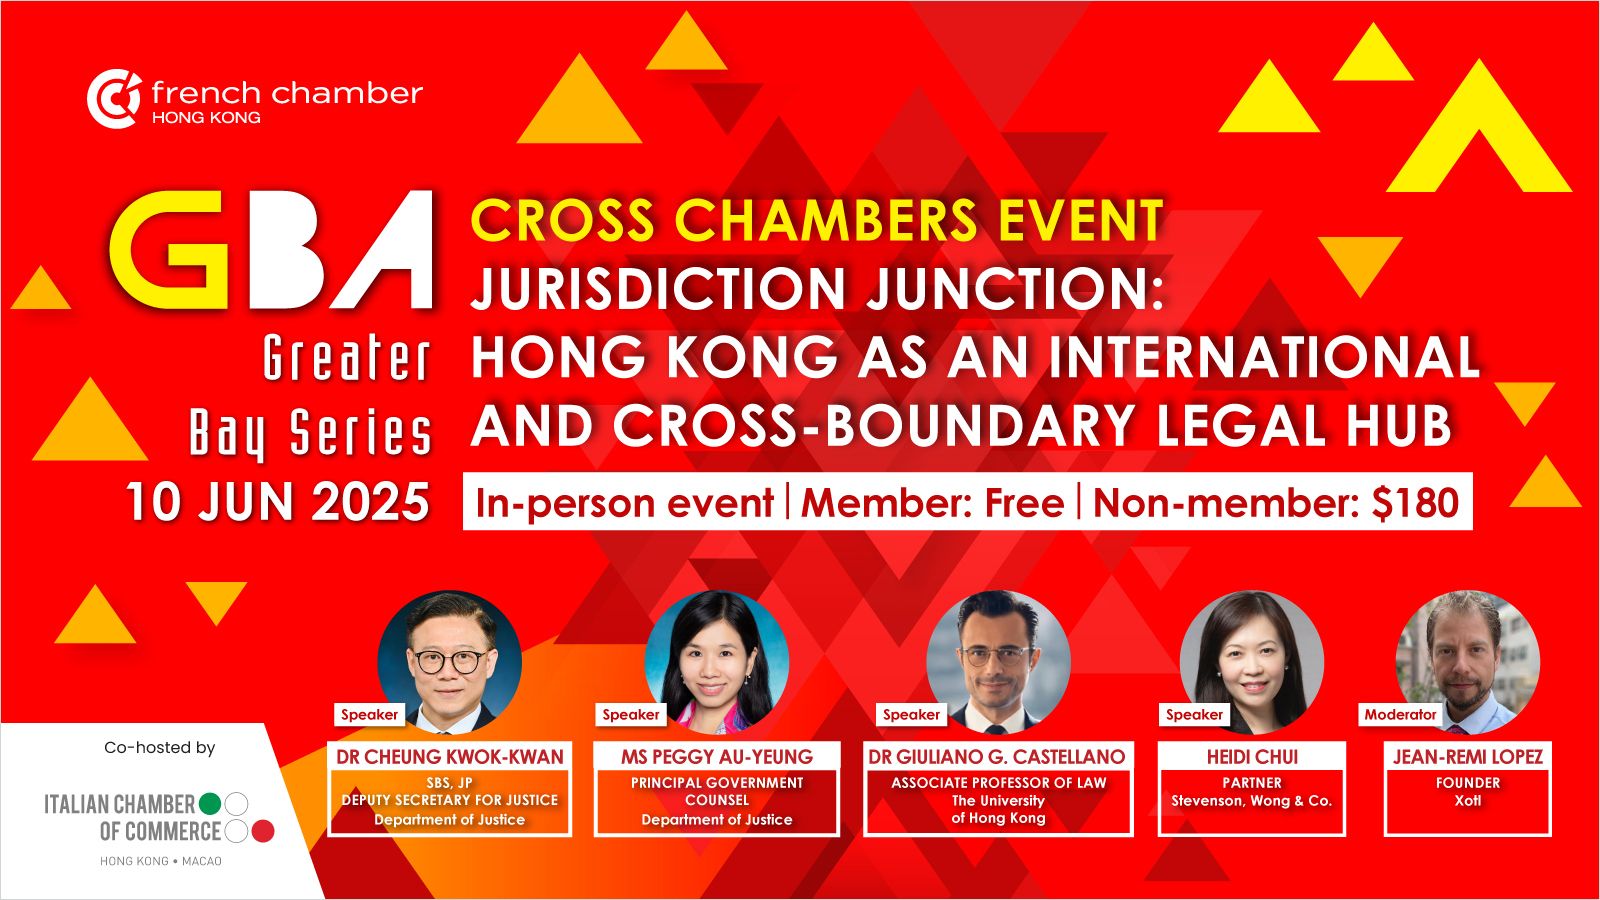
On 10 June 2025, our Partner and Head of the Litigation and Dispute Resolution Department, Heidi Chui, was invited to speak at the panel event titled “Jurisdiction Junction: Hong Kong as an International and Cross-Boundary Legal Hub.” The event was co-organised by the French Chamber in Hong Kong and the The Italian Chamber of Commerce in Hong Kong and Macao, and welcomed over 50 corporate representatives.
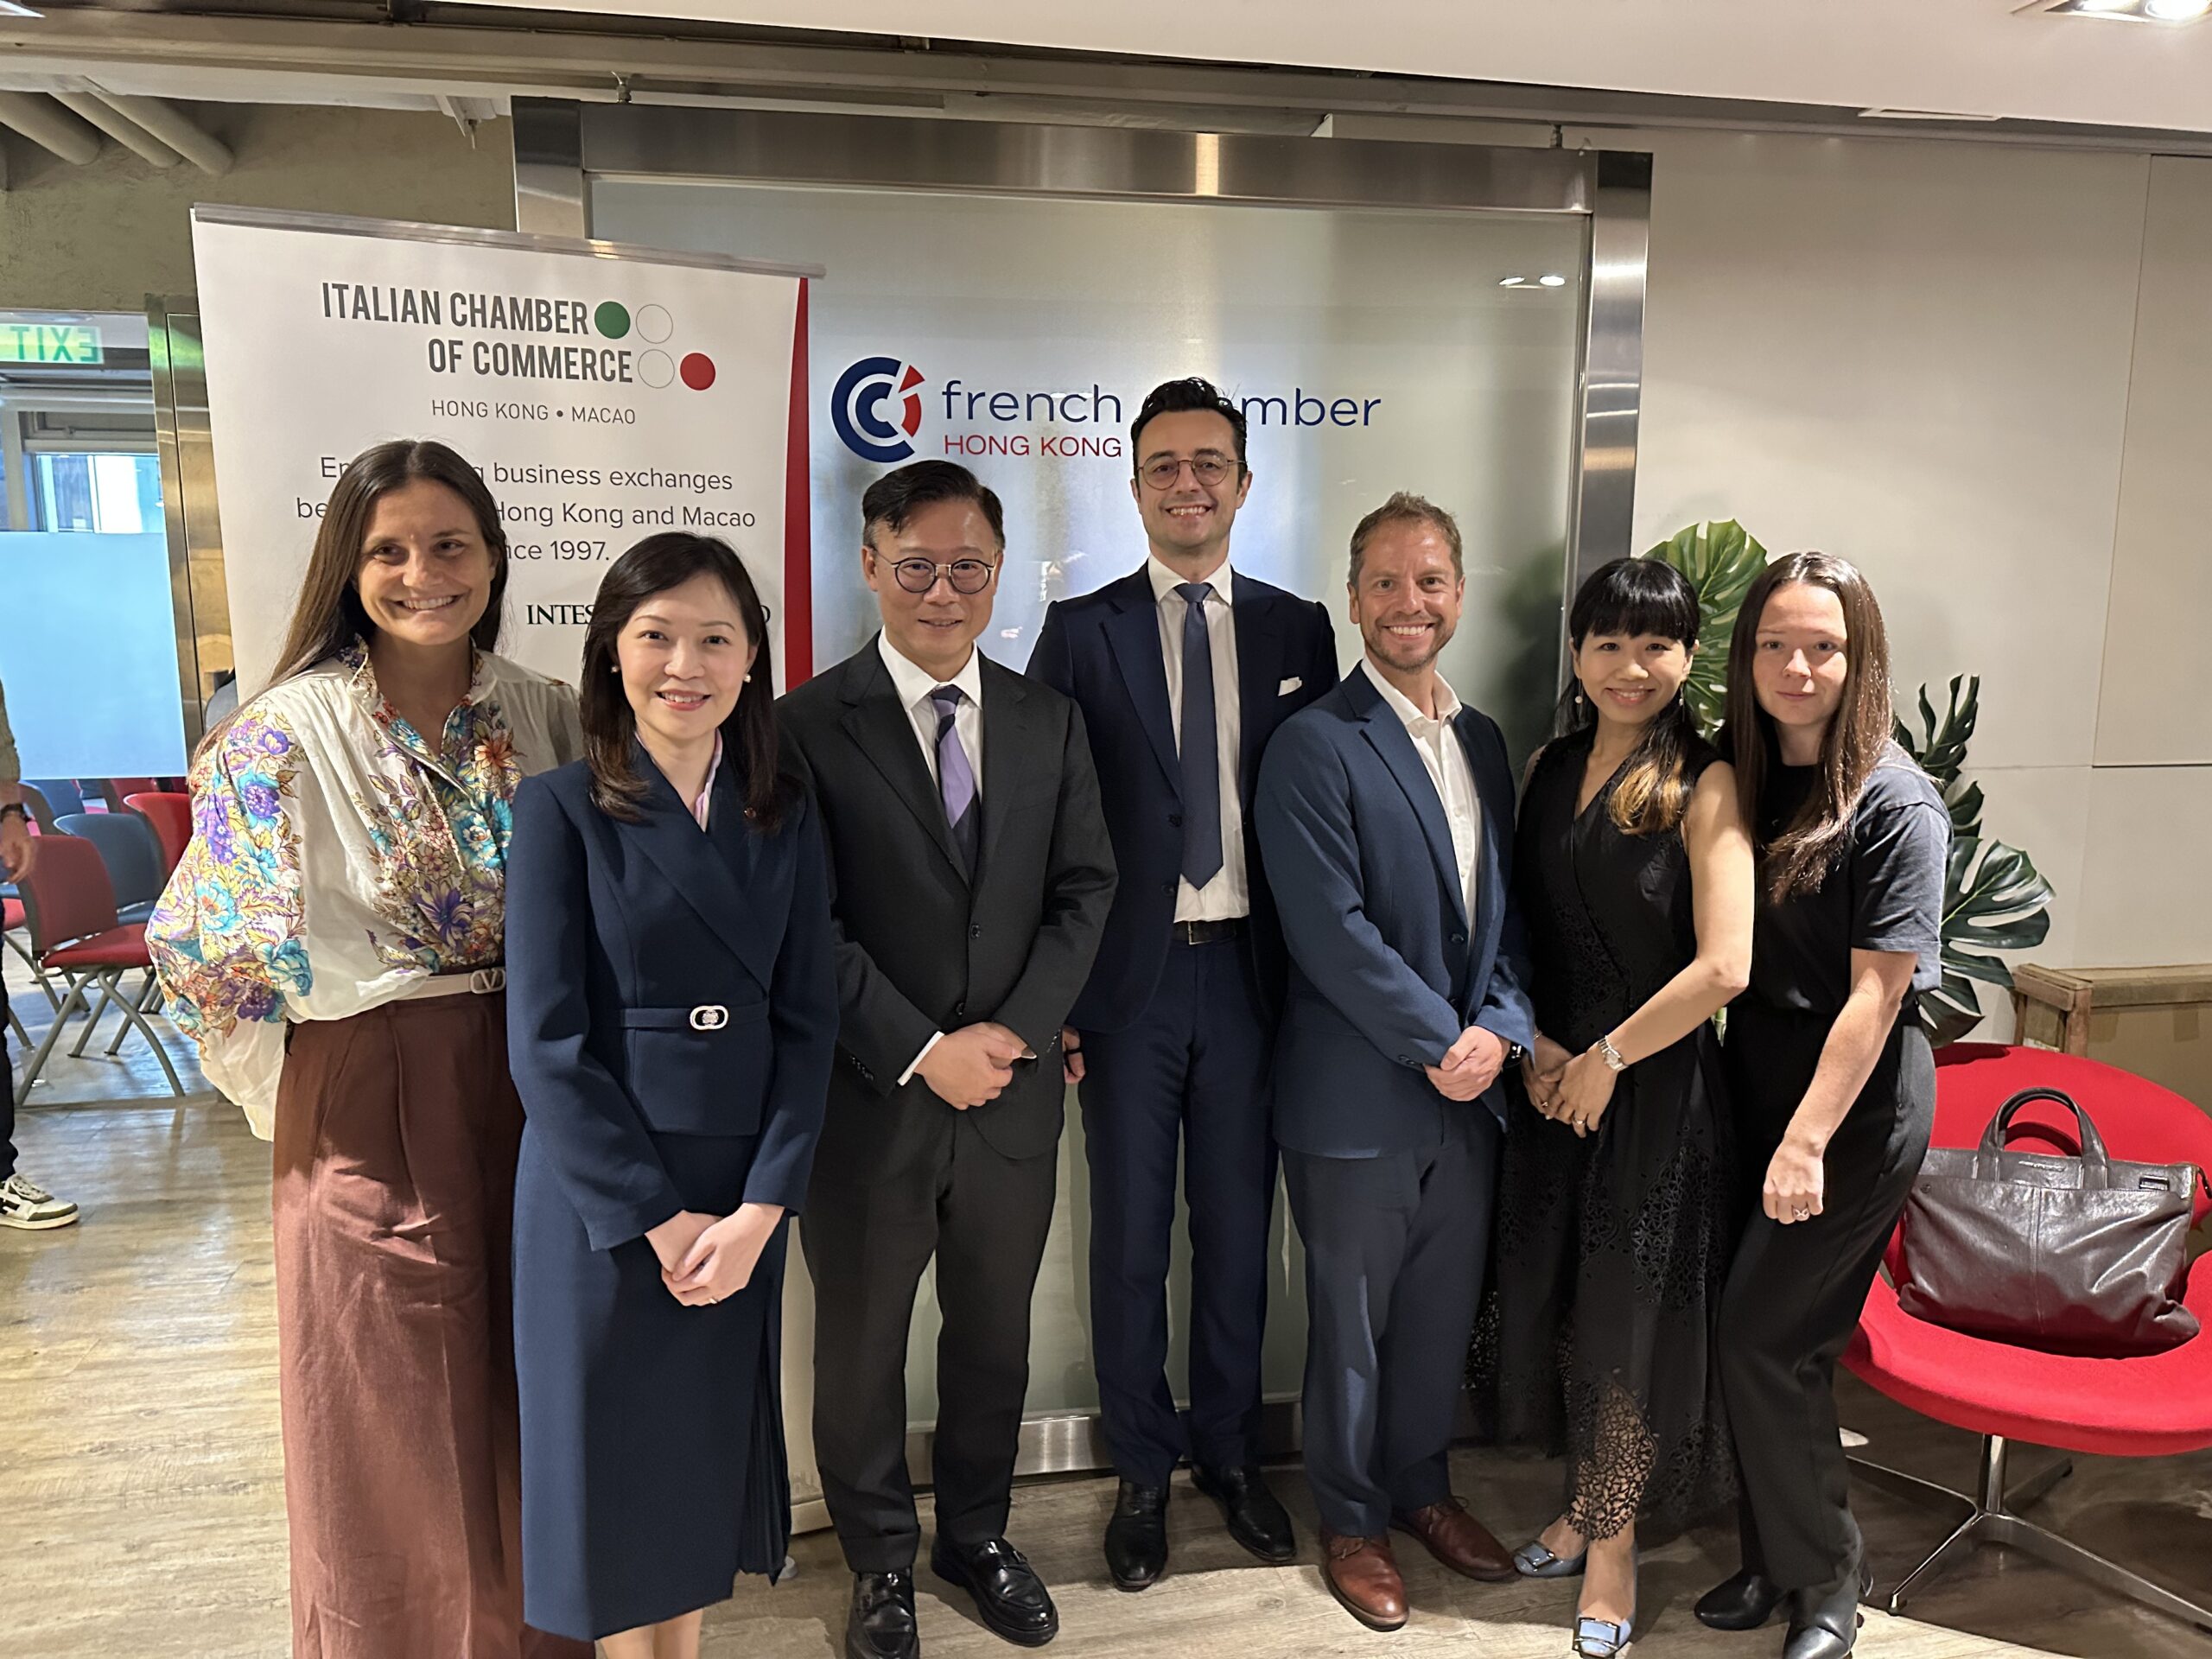 …
Ms Chui was joined by distinguished panellists including Dr Cheung Kwok-kwan, SBS, JP, Deputy Secretary for Justice; Peggy Au-Yeung, Principal Government Counsel at the Department of Justice; and Professor Giuliano G. Castellano, Associate Professor of Law at the University of Hong Kong. Together, they engaged in a dynamic discussion on Hong Kong’s strategic position under the “one country, two systems” framework, with a particular focus on its expanding role in cross-border legal cooperation and international arbitration.
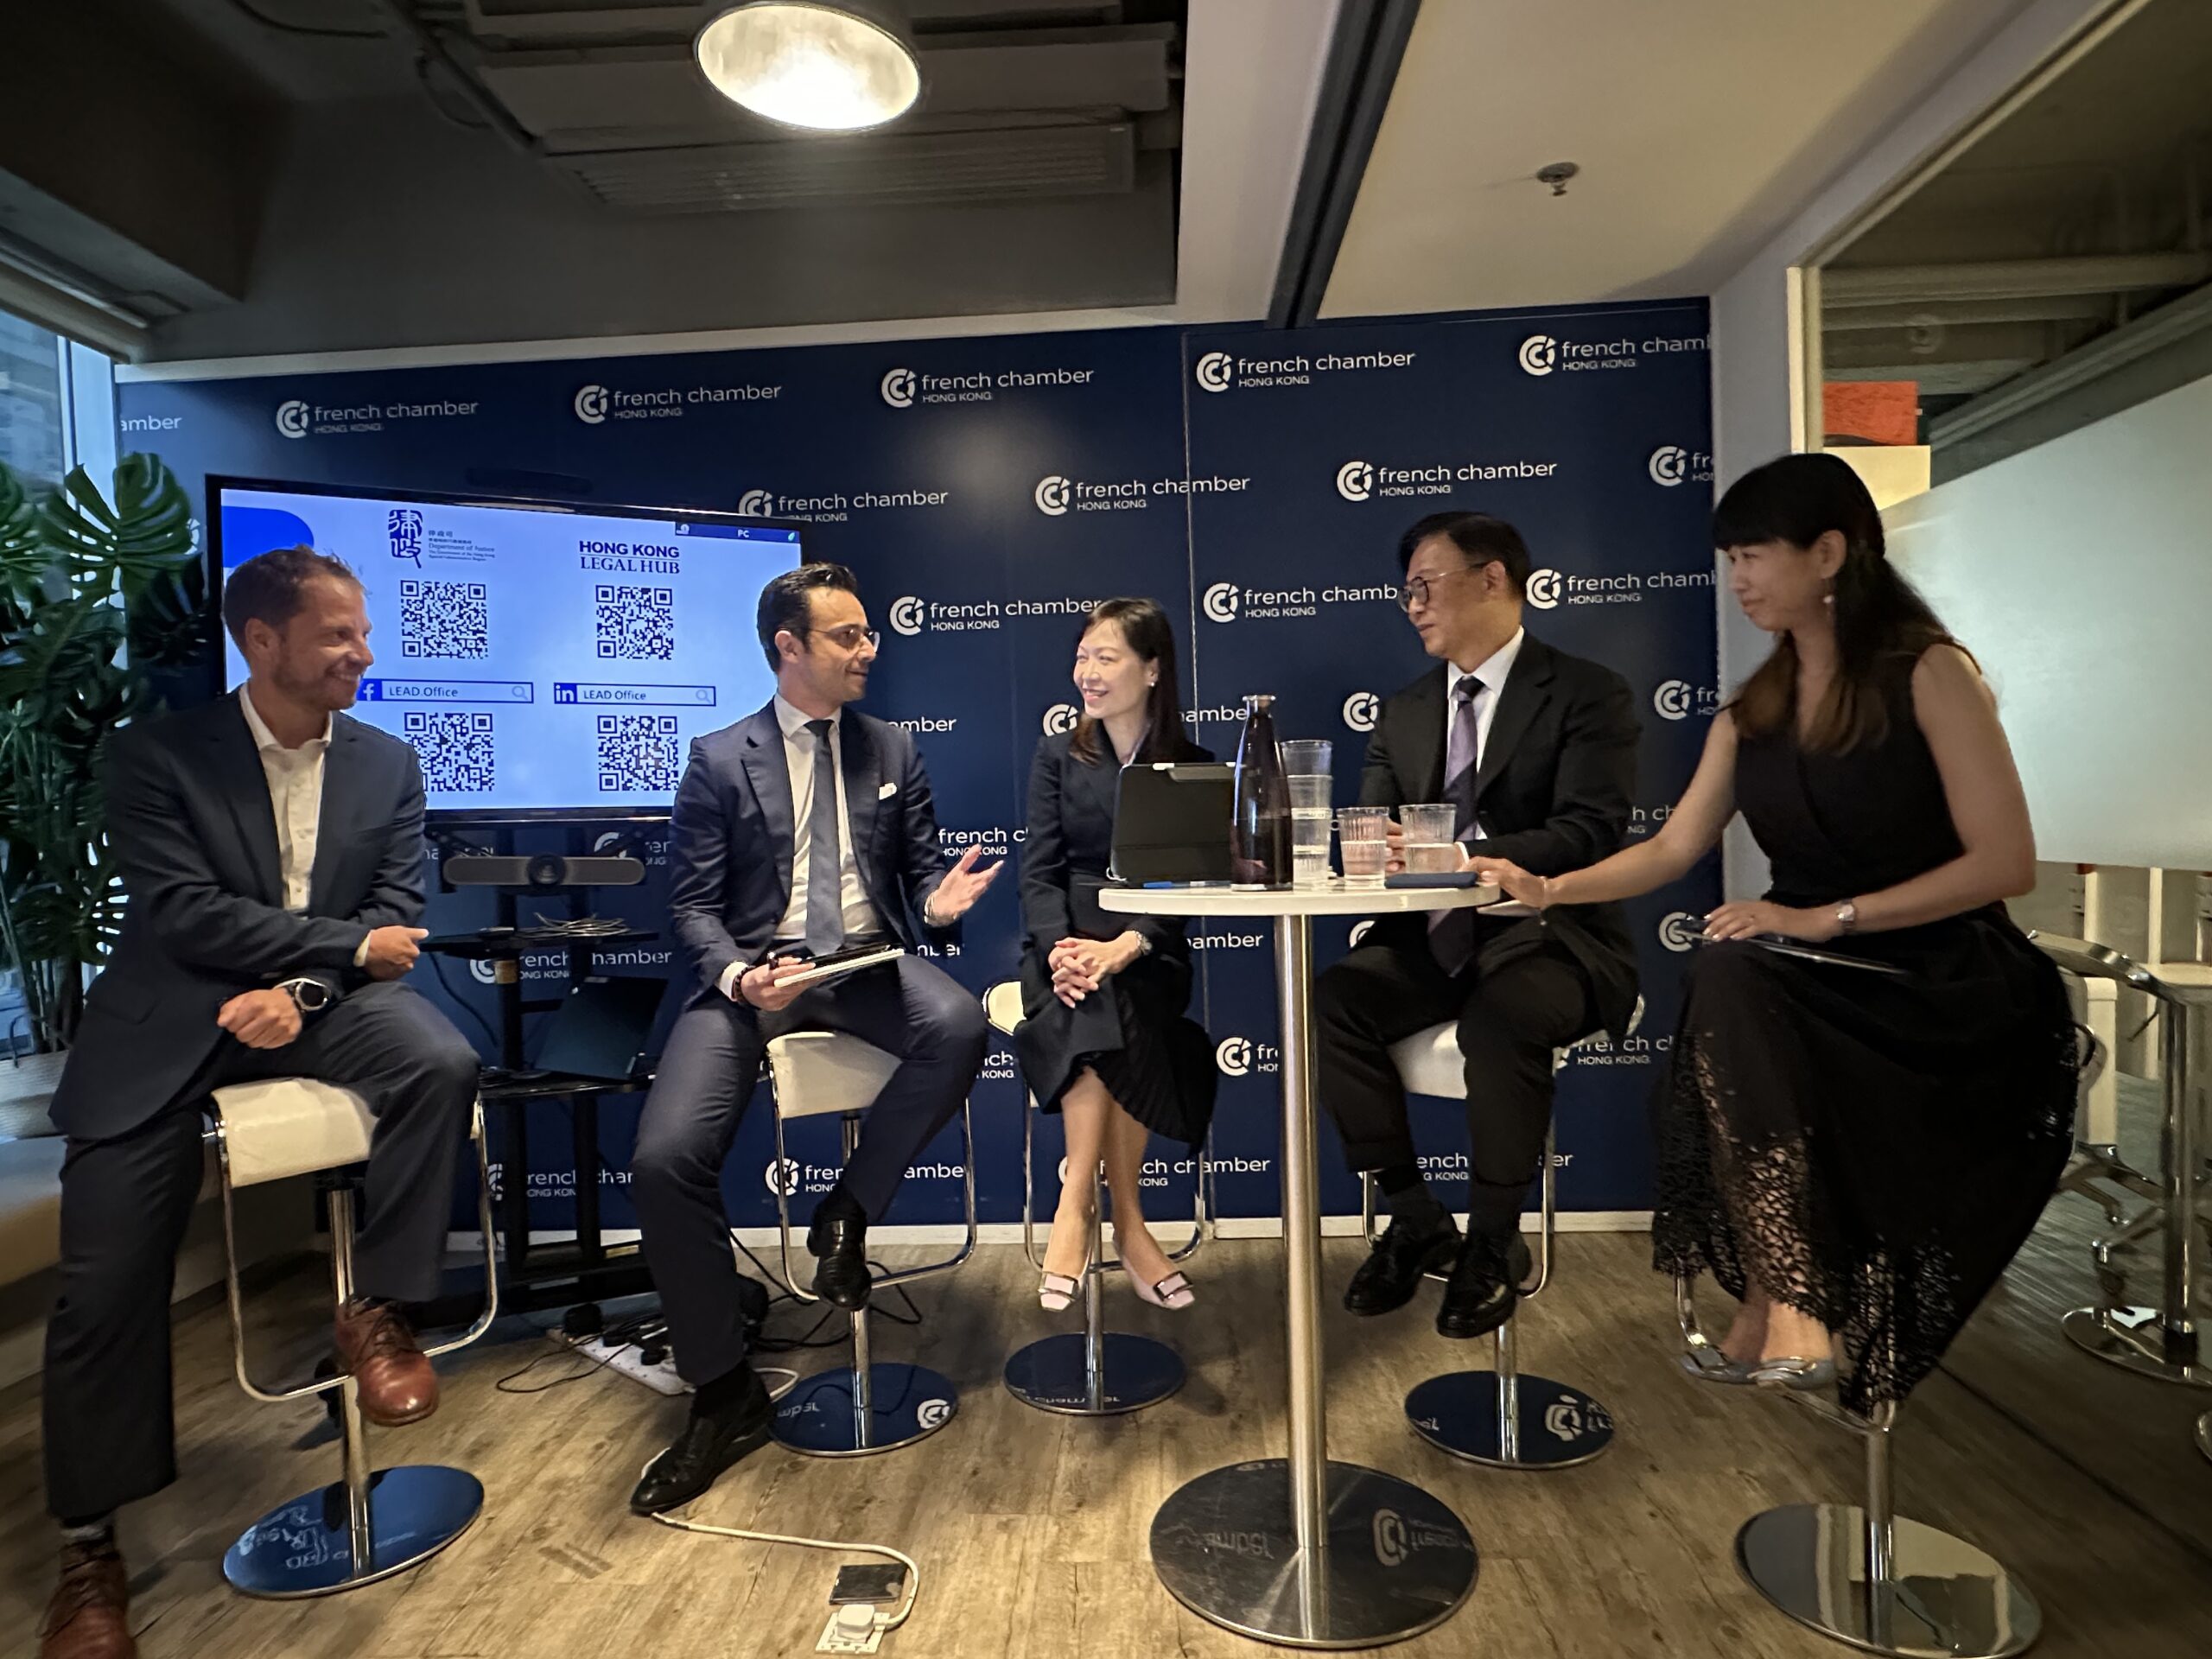
From the left: Professor Giuliano G. Castellano, Associate Professor of Law at the University of Hong Kong; our Partner Heidi Chui; Dr Cheung Kwok-kwan, SBS, JP, Deputy Secretary for Justice; and Peggy Au-Yeung, Principal Government Counsel at the Department of Justice
The event served as a valuable platform for exploring the evolving legal landscape of Hong Kong and its growing importance as a trusted hub for international legal services. Ms Chui shared practical insights on conducting corporate operations in Hong Kong, highlighting how businesses can leverage the city’s unique legal and institutional strengths to navigate the global marketplace.
Please contact our Partner Heidi Chui for any inquiries or further information.