News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
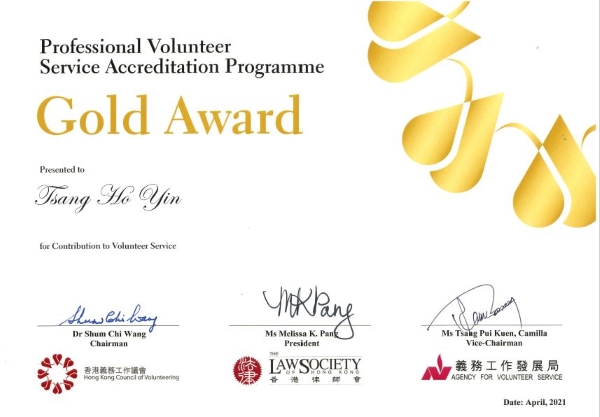
Our Partner Gordon Tsang has been awarded the Gold Award in the Professional Volunteer service Accreditation Programme (PVSA) 2019-2020 for his continuous contributions to volunteer services. Jointly organised by the Hong Kong Council of Volunteering, the Agency for Volunteer Service, and the Law Society of Hong Kong, PVSA aims to promote and commend professionals and senior executives for contributing their professional knowledge and skills in serving the community.
For any enquiries, please contact our Partner Mr. Gordon Tsang.
(中文) 简介
近几年来,越来越多的企业在制定交易合同时会考虑采用多层次争议解决条款 (multitiered dispute resolution clauses)。多层次争议解决条款的特色在于其要求各当事方在发生争议后需先进行友好协商 (negotiation in good faith) 或调解 (mediation),并只有在协商或调解无法解决争议的情况下,才能诉诸诉讼 (litigation) 或仲裁 (arbitration)。虽然多层次争议解决条款在商业合同中被广泛采用,但若一当事方在开展仲裁前并没有依据多层次争议解决条款设定的机制进行协商或调解,仲裁庭的管辖权以及其作出的仲裁裁决的效力就存在不确定性,另一当事方可能会向管辖法院提出异议或撤裁。
在最近的C v D [2021] HKCFI 1474 一案中,香港法院对这一问题进行了澄清,确认当事方有否依据协议中的前置争议解决程序进行协商或调解是仲裁申请可否受理的问题 (issue of admissibility),而不是仲裁庭管辖权的问题 (jurisdiction of the tribunal)。
事实背景
本案的申请人和被申请人皆为经营人造卫星生意的公司,双方签署了一项共同合作开发建造人造卫星的协议 (下称“该协议”)。该协议的第14条是一条多层次争议解决条款 (下称“该条款”),该条款约定,当事方在争议发生时应先真诚地尝试以协商的方式解决争议 (“the Parties shall attempt in good faith promptly to resolve such dispute by negotiation”),且任何一方可以以书面通知的形式将争议交由双方的行政总裁进行解决 (“Either Party may, by written notice to the other, have such dispute referred to the Chief Executive Officers of the Parties for resolution…”)。该条款进一步约定,如果在六十个工作日或双方认同的时限内,争议未能通过协商解决,任何一方可以将争议提交只香港国际仲裁中心并根据当时现行的《贸易法委员会仲裁规则》进行仲裁 (“If any dispute cannot be resolved amicably within sixty (60) business days of the date of a Party’s request in writing for such negotiation, or such other time period as may be agreed, then such dispute shall be referred by either Party for settlement exclusively and finally by arbitration in Hong Kong at the Hong Kong International Arbitration Centrein accordance with the UNCITRAL Arbitration Rules in force at the time of commencement of the arbitration…”)。
合作期间,被申请人的行政总裁去信申请人的董事会主 (并抄送其他董事)(下称“该信函”),告知他们申请人与被申请人之间产生了争议,并邀请申请人的管理层进行改正。被申请人在该信函中亦提出其愿意根据该条款提交该争议交由双方的管理层解决。但被申请人之后并未有将该争议提交至申请人的行政总裁。
随后,被申请人发出仲裁通知,针对申请人展开仲裁程序。申请人认为因为被申请人没有根据该条款发出协商要求,因此仲裁庭并没有管辖权,并提出了管辖权异议。仲裁庭认为该条款要求双方在仲裁前真诚地尝试以协商方式解决争议是强制的 (mandatory),但将争议交由双方的行政总裁解决则是选择性的 (optional),而该信函满足了该条款的协商要求。基于此,仲裁庭驳回了申请人的管辖权异议并作出了被申请人胜诉的管辖权及责任的部分裁决 (Partial Award on Jurisdiction and Liability)(下称“该裁决”)。
法庭判决:仲裁申请可否受理 vs 仲裁庭管辖权
申请人认为仲裁庭并不具备管辖权,进而向香港法院申请撤销该裁决。根据香港《仲裁条例》(第609章) 第81条的规定,如仲裁裁决处理的争议不是提交仲裁意图裁定的事项或不在提交仲裁的范围之列 (第81(2)(a)(iii) 条) 或者仲裁庭的组成或仲裁程序与当事方的约定不一致 (第81(2)(a)(iv) 条),则该仲裁裁决可以被香港法院撤销。
香港原讼法院在分析了一系列的学术著作及之前英国、美国及新加坡的案例后,认为国际上普遍的观点是当事方有否依据协议约定进行前置争议解决程序是仲裁申请可否受理的问题,而不是仲裁庭管辖权的问题。法庭作出此认定的其中一个主要原因是争议解决程序决定的不是争议应否交由仲裁庭裁决,而是争议于何时交由仲裁庭裁决。因此,除非当事方在协议中明确约定未遵循约定的前置争议解决程序将导致仲裁庭不具备管辖权,否则仲裁庭的管辖权未必会受到影响,其中包括就当事方有否遵循前置争议解决程序的问题作出裁定。基于以上理由,法庭驳回了申请人的撤裁申请。
评论及要点
此判决对于香港仲裁法律的发展而言是非常重要的判例。在此之前,未能依据协议约定的前置争议解决程序进行协商或调解可能会导致仲裁庭不具备管辖权,增加仲裁裁决被撤销的风险。在本案中,香港法庭为这一问题提供了确切的指导,确认了当事方未能遵循多层次争议解决条款中约定的前置程序应当作为仲裁申请是否可受理的问题,而并不必然导致仲裁庭的管辖权产生问题,亦未必会构成法庭撤销仲裁裁决的基础。基于此判例,日后仅基于未遵循约定的仲裁前置争议解决程序的撤裁申请极有可能会被法庭驳回。
虽然如此,若想要稳妥开展仲裁程序,当事方仍然需要谨慎制定及严格履行多层次争议解决条款。若当事方没有遵循协议约定的前置争议解决程序,仲裁庭可能会搁置仲裁程序甚至拒绝受理仲裁申请。
本文由本所合伙人,诉讼及争议解决部主管徐凯怡律师、卢家俊高级律师和黄晊晄律师撰写。若阁下想了解更多详情,请联络本所徐凯怡律师 (heidi.chui@sw-hk.com)。
于本文中提供的一切资料仅供参考,不构成任何法律意见,资料亦受制于适用规定及法例不时的更新与修改。若需取得相关法律意见,须咨询法律顾问。
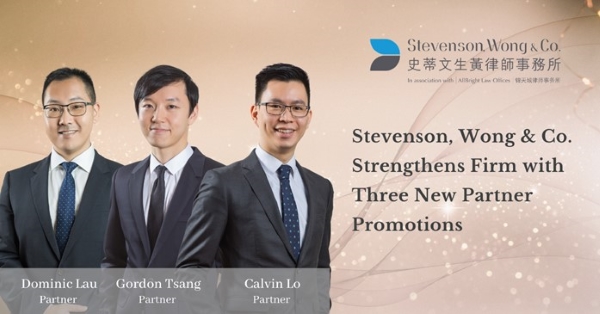
We are delighted to announce the promotions of Mr. Calvin Lo, Mr. Gordon Tsang, and Mr. Dominic Lau from senior associates to the firm’s partnership, effective from 1 July 2021.
Mr. Calvin Lo | Partner, SW Private Client
Mr. Lo joined the firm in 2015. He has a wide range of experience in private client work, including family and matrimonial matters, trust advisory work, estate and succession planning, often with cross-border elements, jurisdiction and forum disputes. He also specialises in handling MIP Committee and guardianship applications as well as for personal injury and fatal accident claims. He is also a HKMAAL accredited family mediator.
Mr. Lo is a Full Member (TEP) of the Society of Trust and Estate Practitioners (STEP). He recently won a STEP Excellence Award for being the top scorer worldwide at distinction level in the exam of STEP Diploma in International Trust Management.
Mr. Gordon Tsang | Partner, Corporate Finance
Mr. Tsang was admitted to practise as a solicitor in Australia in 2012 and in Hong Kong in 2013. He joined the firm in 2015. Mr. Tsang has extensive experience in handling a wide range of corporate and commercial matters, including pre-IPO restructuring and financing, Hong Kong and U.S. IPOs, mergers and acquisitions, loan and financing transactions, corporate governance and general compliance for listed companies as well as private enterprises.
Mr. Tsang is also the Non-Executive Director of China Regenerative Medicine International Ltd (Stock Code: 8158); the Company Secretary of Sunshine 100 China Holdings Ltd (Stock Code: 2608), Mabpharm Limited-B (Stock Code: 2181) and Sundy Service Group Co. Ltd (Stock Code: 9608).
Mr. Dominic Lau | Partner, Regulatory Enforcement & Compliance
Mr. Lau is dual-qualified in New York (USA) and Hong Kong. He joined the firm in 2019.
He is experienced in a broad range of commercial litigation including shareholders’ disputes, international arbitration, and land and property disputes.
In September 2018, Mr. Lau gained higher rights of audience in the high court.
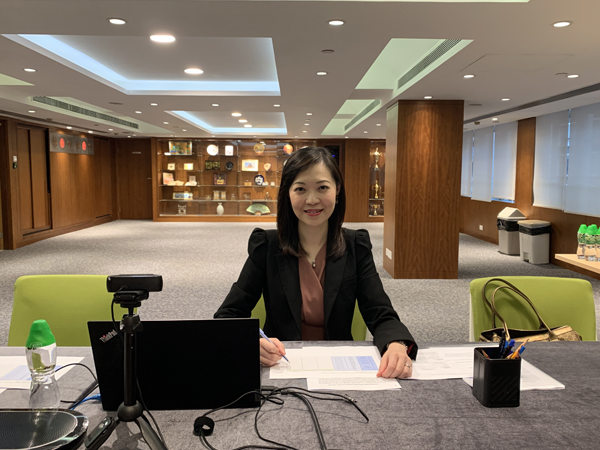
On 5 June 2021, our Partner and Head of Litigation and Dispute Resolution department, Ms. Heidi Chui, was invited by the Peking University Law School (PKU Law School) to be the guest lecturer of “An Introduction to Legal Services and Risk Management for Cross-border Transactions”, a mock arbitration course for the undergraduate and postgraduate of PKU Law School.
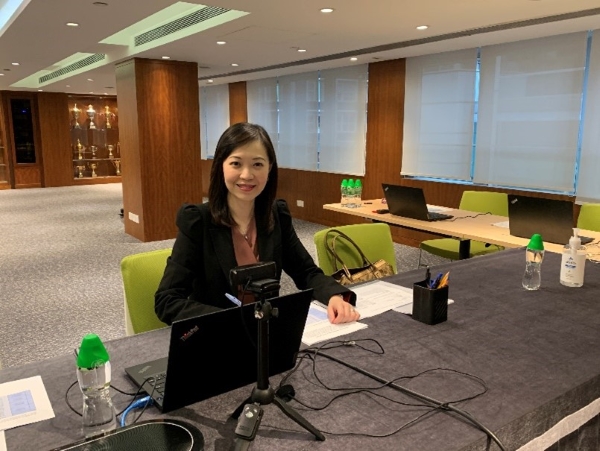
Co-organised by The Law Society of Hong Kong and PKU Law School, the course aims to enrich students’ understanding and practical experience in cross-border arbitration. Ms. Chui shared her experiences in arbitration with the students and offered detailed, constructive feedback on their performances in the moot arbitration. The course was well-received by the students, and they think it will greatly benefit their future studies and careers.
For more information, please contact our partner Ms. Heidi Chui (heidichui.office@sw-hk.com).
Background
Following the consultation paper (the “Consultation Paper”) published by the The Stock Exchange of Hong Kong Limited (the “Exchange”) in November 2020 on the proposed increase in the Main Board profit requirement (the “Profit Requirement”), the Exchange published the highly anticipated Consultation Conclusion on “The Main Board Profit Requirement” (the “Consultation Conclusions”) on 20 May 2021.
Summary
After careful consideration of stakeholder feedback about the quantum and timing of the proposed increase as set out in the Consultation Paper, the Exchange modified its proposal as follows:
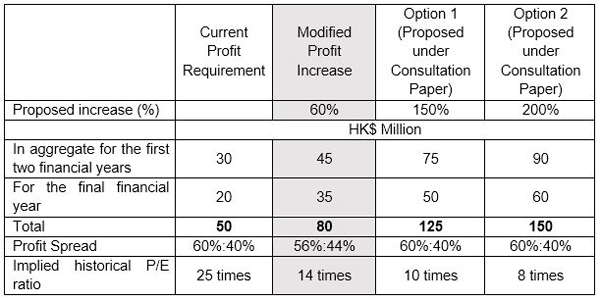
(a) Smaller increase in the Profit Requirement (the “Modified Profit Increase”)
(i) the Profit Requirement shall be increased by 60% (rather than the proposed 150% and 200%), resulting in a three-year aggregate profit threshold of HK$80 million (the “Aggregate Profit Threshold”), up from the current HK$50 million aggregate profit threshold requirement.
(ii) the profit spread is amended to a 56%:44% split (as compared to current 60%:40% split), such that the minimum aggregate profit required for the first two years of the track record period will be HK$45 million (from the current HK$30 million) and the final financial year of HK$35 million (from as the current HK$20 million) (the “Profit Spread”).
The Modified Profit Increase translates into an implied historical P/E ratio of approximately 14 times (as oppose to current 25 times), a change that is in line with the average P/E ratio of the Heng Sang Index between 1994 and 2020; and
(b) Implementation Date – the Modified Profit Increase will become effective on 1 January 2022.
(c) More flexible relief from the Profit Spread – the Exchange will also be prepared to grant a relief from the profit Spread on case-specific circumstances.
The table below sets out a comparison of the Modified Profit Increase with the proposals in the Consultation Paper:
Implementation of the Proposal
The Modified Profit Increase with the relevant consequential amendments to the Main Board Listing Rules, will take effect on 1 January 2022 (the “Effective Date”). Any Main Board listing applications submitted on or after the Effective Date will be assessed under the Modified Profit Increase.
This Effective Date would also be applicable to any renewals of previously submitted applications or GEM transfer applications. A listing applicant will not be permitted to withdraw its listing application before it lapses and resubmit the listing application shortly thereafter before the Effective Date such that the application will be assessed in accordance with the current profit requirement.
Temporary Relief
If the listing applicant meets an increased Aggregate Profit Threshold of HK$80 million, the Exchange will be prepared to grant relief from the Profit Spread on case-specific circumstances rather than through a set of fixed conditions. In this regard, the Exchange will ordinarily, among other things, evaluate the applicant’s business nature and evaluate any underlying reasons for its inability to meet the Profit Spread.
The Exchange will also impose conditions where appropriate. When considering an application for a waiver from the revised Profit Spread, the Exchange will critically assess the need to include a mandatory disclosure of the listing applicant’s profit forecast in the listing document and may also enquire on how the issuer’s IPO price was determined with reference to the book-building process.
Listing of SMEs
The Exchange stated in the Consultation Conclusions that the increase of profit requirement would not deprive suitable SMEs of the opportunities to list in Hong Kong as the Exchange saw GEM as a viable alternative. The Exchange further reassured that pre-revenue and pre-profit companies do not rely on the Profit Requirement to list. Such companies will also continue to be eligible for listing if they can demonstrate compliance with alternative eligibility and suitability requirements under the relevant Listing Rules and related guidance materials.
Pre-revenue biotech company could continue to rely on industry-specific pre-conditions as set out in Guidance Letter HKEX-GL92-18, and attain a market capitalisation of HK$1.5 billion and a public float of HK$375 million under Listing Rules 18A.03 and 18A.07. Similar requirements also continue to be applicable for mining companies under Chapter 18 of the Listing Rules.
Impact on GEM Listings
The Exchange taken note that there has recently been a significant decrease in the number of new GEM listings (from 75 in 2018 to 8 in 2020). The Exchange has attributed this observation to the lack of interest in “shell companies” due to the regulatory actions taken by the Exchange and the SFC as well as the removal of the streamline transfer process from GEM to the Main Board in 2018. The Exchange viewed these new regulations as designed to curb “shell” manufacturing and not to prohibit suitable companies from listing on GEM.
The Exchange further reiterated that GEM remains a viable alternative listing venue for companies and will consider a review of GEM in terms of its positioning and market perception. A consultation paper to seek market feedback on appropriate reforms may be forthcoming when necessary.
Competitiveness of the Exchange
The Exchange considers that the Modified Profit Increase will not compromise the Exchange’s competitiveness against other overseas exchanges. In particular, the HK$80 million profit requirement is still lower than that of SGX (approximately pre-tax profit of HK$170 million) and NYSE (approximately pre-tax profit of HK$194 million). Furthermore, the US markets typically also requires a higher public free float of approximately HK$310 million as compared to HKEX’s minimum of HK$125 million for Main Board applicants.
The market capitalisation requirement of HK$500 million also remains competitive when compared against that of NASDAQ (approximately HK$1,242 million), NYSE (approximately HK$3,881 million), SGX (approximately HK$850 million), ChiNext and STAR Board (approximately HK$1,200 million). Certain listing applicants may be considered ineligible to list in view of industry specifications or other eligibility requirements imposed by such overseas market, such as “high tech, emerging or innovative’ as required by ChiNext and STAR Board.
The below table sets out a comparison of the profit requirements with the profit-related eligibility requirement of the selected overseas main markets, ChiNext and STAR Board:
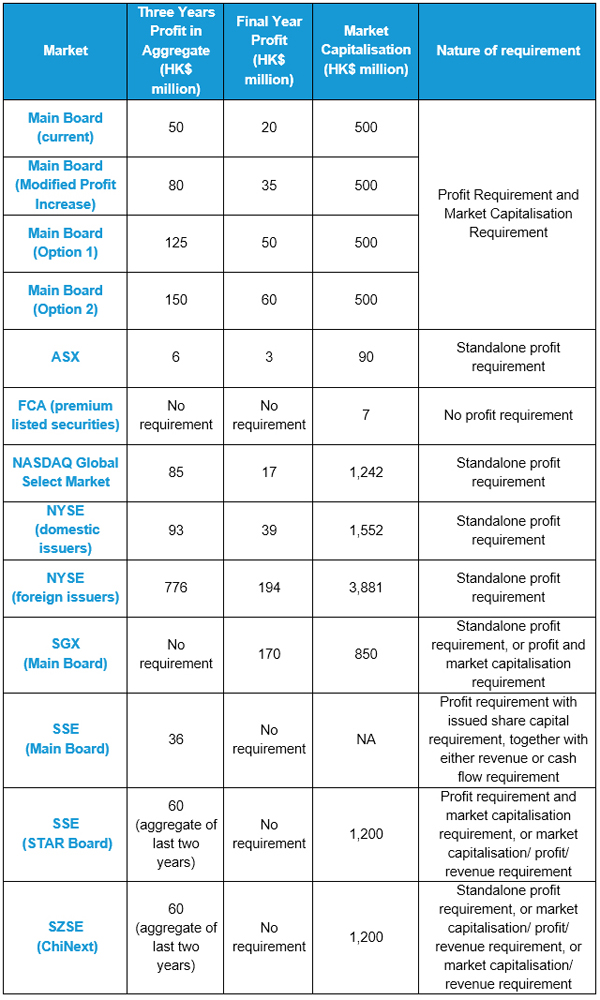
Source: Consultation Conclusions
Implications and Takeaways
A proposal involving an exchange’s listing requirements, especially its profit requirement, has always been a delicate balancing act of interests among various stakeholders. Against the backdrop of COVID-19, concepts of curtailing “shell” activities, protecting the interest of the investing public, while affording a fair chance for SMEs to list despite their size, as well as magnitude and timing of such implementation, are all valid considerations.
The jury is still out – as it how the Hong Kong future IPO scene eventually unfolds. Meanwhile, we suggest prospective listing applicants to seek appropriate advice and discussions on this topic, in order to formulate their listing plans that best suit their circumstances.
Please contact our Partners Mr. Hank Lo, Ms. Cornelia Chu or Mr. Rodney Teoh for any enquiries or further information.
This newsletter is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
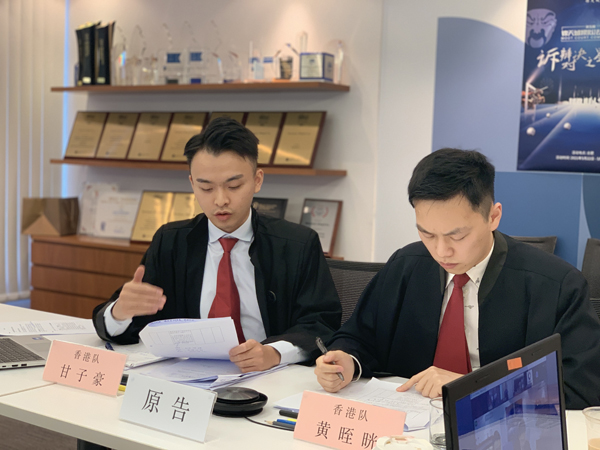
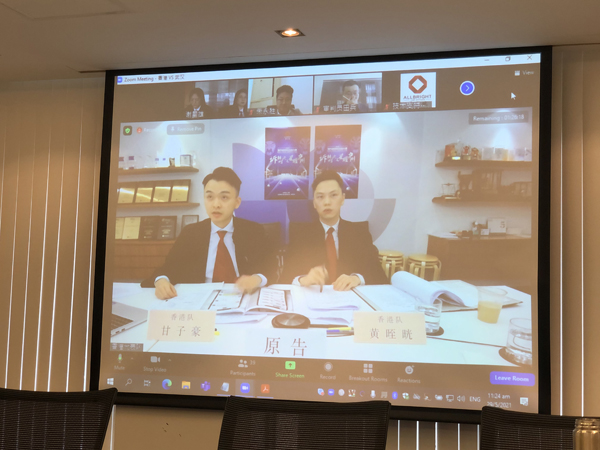
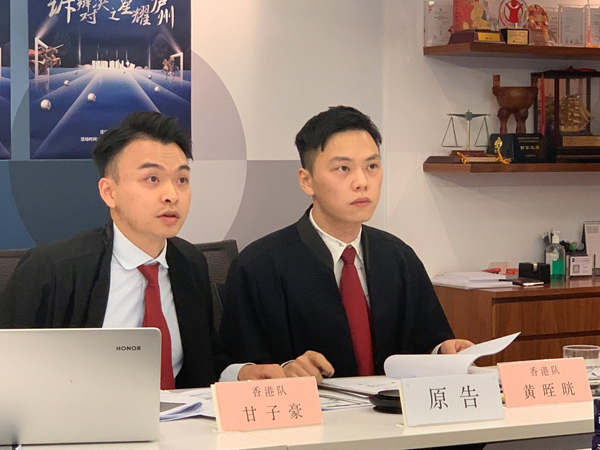
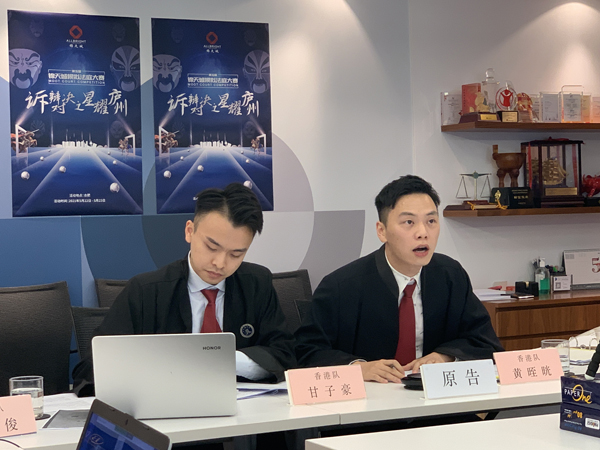
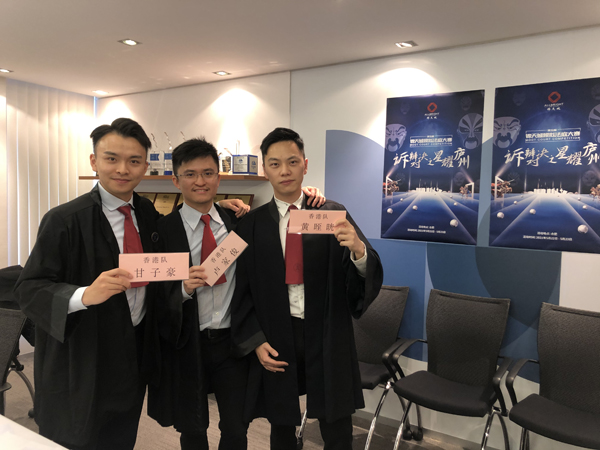
Between 29-30 May 2021, our firm’s Partner and Head of Litigation and Dispute Resolution department, Ms. Heidi Chui, and her team Senior Associate Mr. Kyle Lo, Associate Mr. Calvin Huang and Paralegal Mr. Harold Gan, participated in the 5th AllBright Law Offices Virtual Moot Court Competition (the “Competition”).
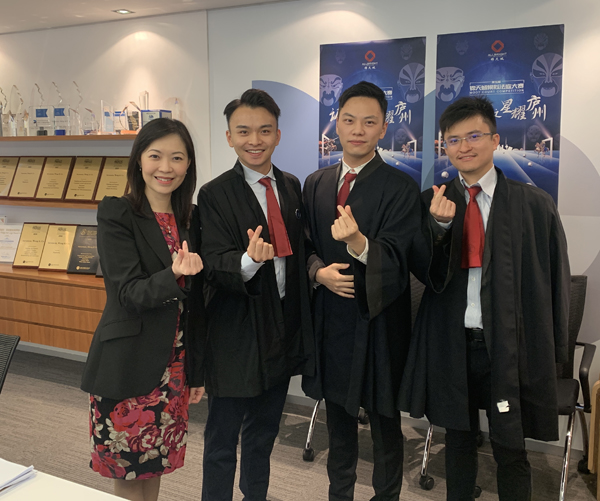
The Competition was organised by Shanghai AllBright Law Offices and co-organised by Shanghai AllBright (Hefei) Law Offices, AllBright Litigation and Arbitration Committee, and Anhui University. Due to the pandemic, the Competition was held online, and a total of 22 teams from all across China participated in the Competition.
The opening ceremony of the Competition was host by Mr. Guo Rui, Senior Partner of AllBright Law Offices, and Mr. Lawrence Zhu, Senior Partner of AllBright Law Offices delivered the opening address.
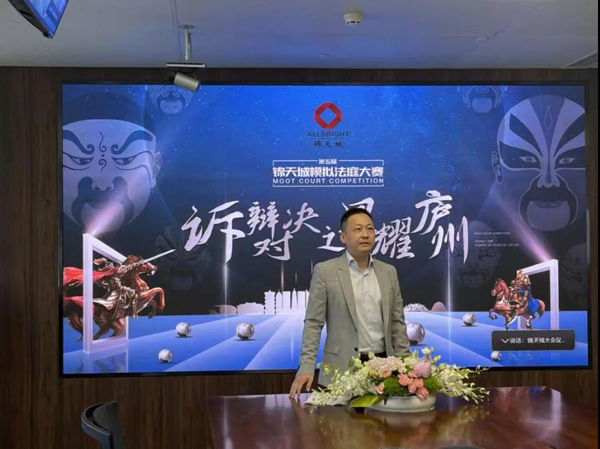
Senior Partner of AllBright Law Offices, Mr. Guo Rui
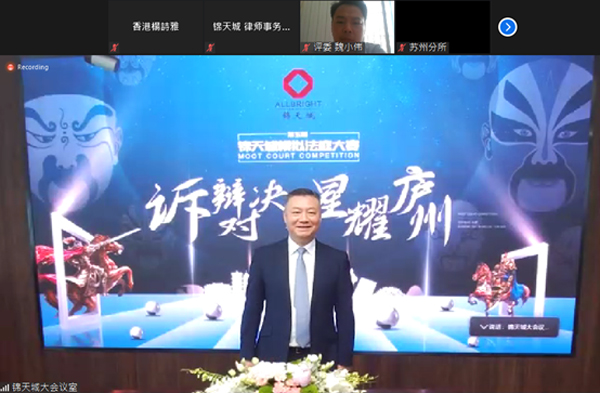
Senior Partner of AllBright Law Offices, Mr. Lawrence Zhu
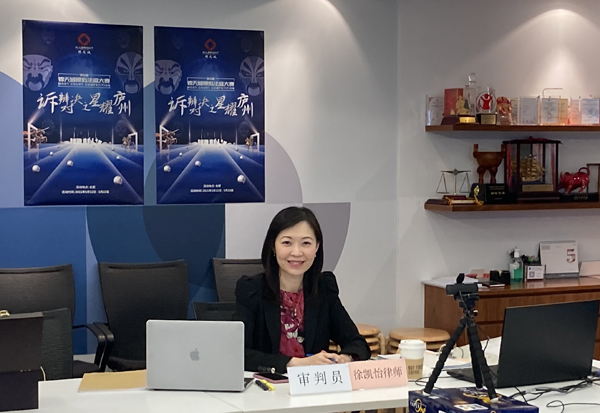
Our Partner Ms. Heidi Chui was invited to judge one of the moot competitions and gave her detailed views and comments on the performance of both plaintiff and defendant teams.
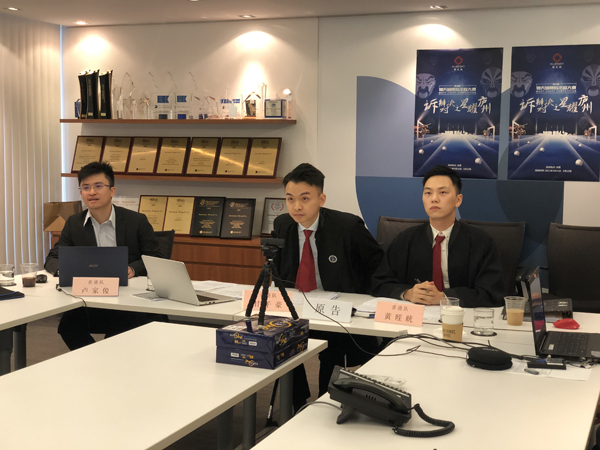
Our firm’s team led by our Senior Associate, Mr. Kyle Lo, consisted of Associate Mr. Calvin Huang, and Paralegal, Mr. Harold Gan. After a stiff challenge against the team from Wuhan, our firm’s team successfully won the first round in the competition.
The 5th AllBright Law Offices Virtual Moot Court Competition has been a great success. The Competition has fostered the mutual understanding of legal practice between the Mainland and Hong Kong and deepened the exchanges and cooperation
between the two firms.
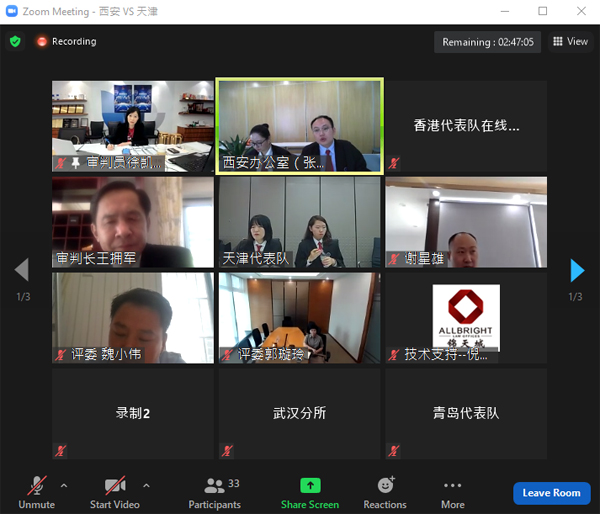
Please contact our Partner Ms. Heidi Chui (heidichui.office@sw-hk.com)for any enquiries or further information about this event.