
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
 …
We are delighted to announce that our firm has once again been recognised by IFLR1000 Asia Pacific Guide 2025/ 2026, a guide to the world’s leading financial and corporate law firms and lawyers in the following practice areas:
In addition, three of our Partners have received the following recognition for their outstanding work:
IFLR1000 evaluates law firms and lawyers based on transactional evidence and client feedback. The rankings recognize firms that have advised on some of the most complex and innovative transactions in their markets and received outstanding feedback from clients for their work.
For more details on our rankings, please click here.
Please contact our Partners Hank Lo, Cornelia Chu, Rodney Teoh, Osbert Hui, Erica Cheng, Gordon Tsang, Dominic Lau or Terence Lau for any inquiries or further information.
 …
In the latest Policy Address delivered on 17 September 2025, the Hong Kong Chief Executive John Lee Ka-chiu announced that Hong Kong will relax its rules for property purchases under the New Capital Investment Entrant Scheme (“New CIES Scheme”) to attract new investors.
The New CIES Scheme, which was re-introduced on 1 March 2024 after a suspension of approximately nine years, aims to attract high-net-worth individuals committed to investing not less than HK$30 million to settle in Hong Kong with their families and explore the city’s diverse investment opportunities.
When the New CIES Scheme was first relaunched in the market, the total investment amount in real estate (covering non-residential real estate and residential real estate) which was counted towards fulfilment of minimum investment threshold was subject to an aggregate cap of HK$10 million. In addition, only residential properties with transaction price of HK$50 million or above were eligible for inclusion.
The new arrangement will now raise the aggregate investment cap for real estate investment from HK$10 million to HK$15 million, among which the cap on residential real estate will remain at HK$10 million. Nonetheless, the threshold of transaction price of residential real estate for one single property will be reduced from HK$50 million to HK$30 million.
The new measure takes effect from 17 September 2025 and applies to real estate investments where the completion date of the purchase falls on or after 17 September 2025.
Our Immigration Team assists applicants who wish to settle in Hong Kong understand the requirements of different visa schemes and support them throughout the application process. Please contact our Partner Willy Cheng for any enquiries or further information.
This newsletter is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
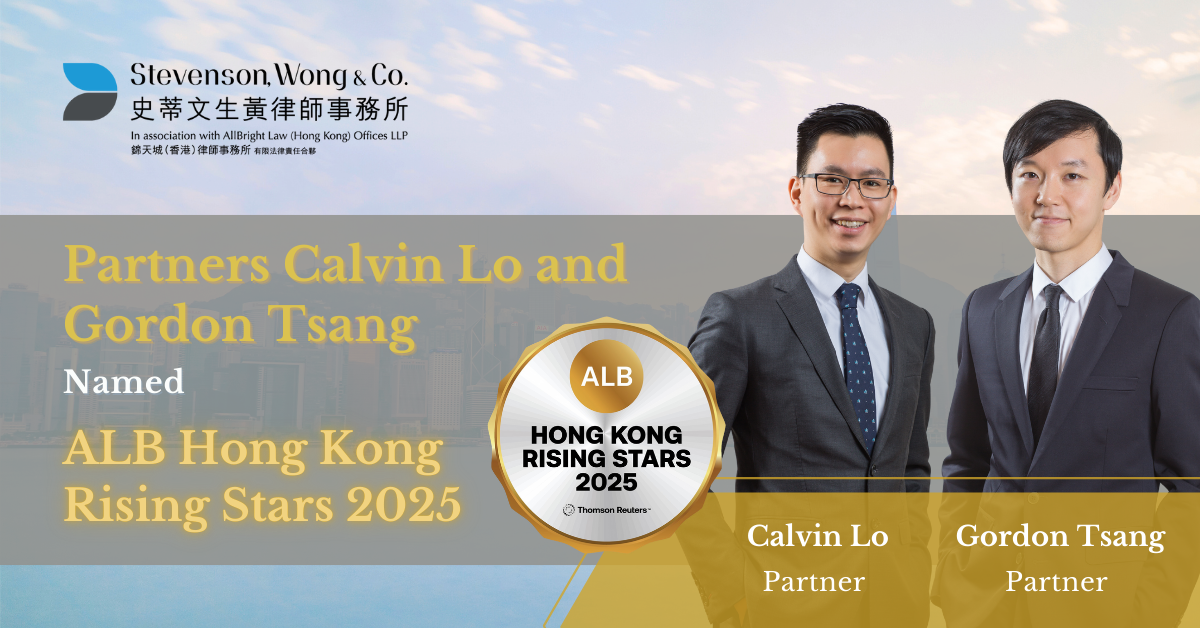 …
We are delighted to share that our partners, Calvin Lo and Gordon Tsang, have been named ALB Hong Kong Rising Stars for 2025, with Mr Tsang being recognized for the second year running. This accolade showcases their remarkable contribution and achievements in the legal profession.
ALB, a prominent legal publication under Thomson Reuters, is one of the most influential legal media outlets worldwide. The Rising Stars list highlights Hong Kong’s most promising next generation lawyers, showcasing those who have consistently demonstrated exceptional dedication, legal expertise, and innovative approaches to client service. This recognition solidifies Calvin and Gordon’s reputations as future leaders in the legal profession.
Calvin handles a wide range of private client work, including family and matrimonial matters such as divorce, children disputes, wardship, relocation, ancillary relief claims, often with cross-border elements, jurisdiction and forum disputes. He also handles trust advisory work, estate and succession planning, will drafting and probate applications. In the area of mental health law, Calvin advises clients in applications for the appointment of MIP Committee as well as guardianship orders. He has also been appointed by the Court as professional MIP Committee. He is also a Trust and Estate Practitioner of (STEP), a Certified Trust Practitioner of HKTA, and an accredited family mediator.
Gordon has extensive experience in handling a wide range of corporate and commercial matters, including pre-IPO restructuring and financing, Hong Kong and U.S. IPOs, mergers and acquisitions, loan and financing transactions, corporate governance and general compliance for listed companies as well as private enterprises. He has established a remarkable reputation for advising clients on complex capital market transactions and corporate acquisitions.
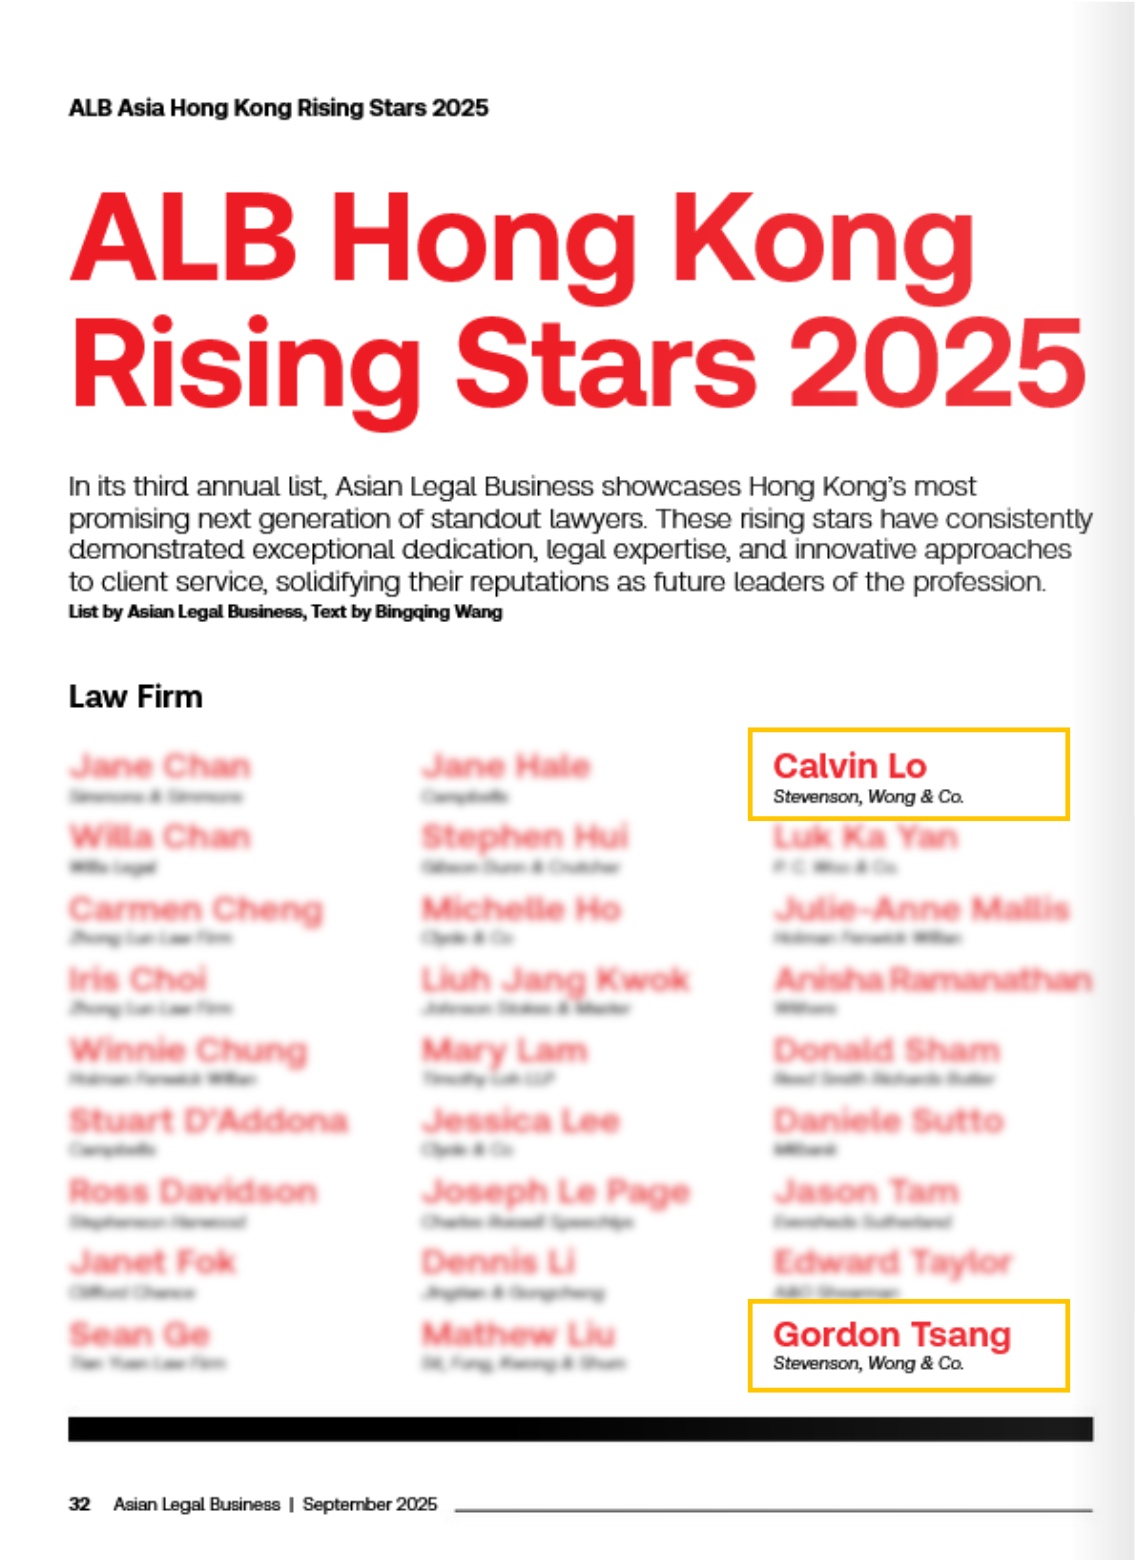
For more information, please contact our Partners Calvin Lo and Gordon Tsang, or click here to view ALB’s report.
 …
Stevenson, Wong & Co. acted as Hong Kong legal adviser to US Tiger Securities, Inc. (the “Underwriter”), the underwriter of ChowChow Cloud International Holdings Limited (NYSE American: CHOW) (“ChowChow Cloud”) in connection with its successful listing on NYSE American on 16 September 2025 (the “NYSE American Listing”). ChowChow Cloud offered a total of 2,600,000 Ordinary Shares, priced at US$4.00 per share , raising aggregate gross proceeds of approximately US$10.4 million.
ChowChow Cloud is a pioneer in providing one-stop cloud solutions supporting companies across the IT industry value chain throughout their cloud transformation journey, from consulting, deployment, and migration to cloud environment building and management.
ChowChow Cloud’s business primarily comprises (i) digital transformation consulting services consisting primarily of cloud suitability assessment, real-time resource management and strategic planning and advisory, (ii) professional IT services with a wide range of capabilities designed to facilitate seamless cloud integration and digital transformation, (iii) AI-powered proactive cloud managed services covering all aspects of day-to-day cloud maintenance and support, and (iv) IT infrastructure solutions covering on-premise private cloud setups and public cloud integrations, including infrastructure applications such as its Sereno Cloud App360 AI and Data Science Platform, which consists of several core components.

ChowChow Cloud primarily operates in the Asia-Pacific region, with a strong presence in Hong Kong and Singapore. Since 2019, it has expanded its geographical footprint to other jurisdictions in the Asia-Pacific region, including the Philippines, Taiwan, Indonesia, and Australia.
Our Partners, Hank Lo and Gordon Tsang, together with Senior Associate Gary Kwok, acted as Hong Kong legal counsel to the Underwriter in the NYSE American Listing.
Please contact Hank Lo or Gordon Tsang for any enquiries or further information about this transaction.

Our Partners Heidi Chui and Rodney Teoh.
…
We are proud to announce that our Partner, Head of Banking and Finance and Litigation and Dispute Resolution Department, Heidi Chui, has been honoured with the prestigious title of “Woman Lawyer of the Year” at The ALB Hong Kong Law Awards 2025. This recognition adds to her accolades as a two-time winner of the “Dispute Resolution Lawyer of the Year” in 2023 and 2024, making her a three-time recipient at The ALB Hong Kong Law Awards.
Additionally, our Partner and Deputy Head of Corporate Finance and Co-head of the FinTech Group, Rodney Teoh, has been named a finalist for “Dealmaker of the Year”.
The award ceremony, held on 12 September 2025 at the Conrad Hong Kong, gathered legal professionals from across the region to honor excellence in the legal field. Our Partners, Heidi Chui and Rodney Teoh, represented our firm at this distinguished gala.
The ALB Hong Kong Law Awards is one of the most prestigious and longest-running awards in Hong Kong’s legal community, recognizing the outstanding performance by private practitioners and in-house teams in the region.
We are also delighted to share that our firm received nominations in the following categories:
We extend our gratitude to ALB for hosting this exceptional event and congratulate all winners and finalists.

Our Partners (from the left) Katy Lai, Heidi Chui and Rodney Teoh.


For more information, please contact our Partners Heidi Chui and Rodney Teoh
 …
On 27 June 2025, the Financial Services and the Treasury Bureau (“FSTB”) and Securities and Futures Commission (“SFC”) released two consultation papers concerning the development of regulation surrounding virtual assets (“VA(s)”[1]). Specifically, the Consultation Papers propose new licensing regimes for (i) dealing in VAs (the “VA Dealing Consultation Paper”) and (ii) VA custodian services (the “VA Custodian Consultation Paper”, together with the VA Dealing Consultation Paper, the “Consultation Papers”). The consultation period for public comments on the Consultation Papers runs up until 29 August 2025.
The current proposals have the dual aims of strengthening Hong Kong’s Anti-Money Laundering (“AML”)/Counter-Terrorism Financing (“CTF”) compliance and creating an investor-friendly and secure VA regulatory framework in Hong Kong. This News Update summarises the key contours of the regulatory proposals made by the Consultation Papers, and offers our insights on the issue.
Key Definitions and Scope
“Dealing in VAs” – The VA Dealing Consultation Paper proposes to define “dealing in VAs” as the situation where, by way of business, any person makes or offers to make an agreement with another person, or induces or attempts to induce another person to enter into or to offer to enter into an agreement:
The legislative proposals would capture VA-to-VA and VA-to-fiat conversions, brokerage and block trades, via physical outlets or other platforms. Peer-to-peer trading of VAs between individuals without the involvement of any intermediaries are generally excluded from the above scope, but platforms facilitating such trading will be assessed on a case-by-case basis, as they may fall within the scope depending on factors such as their remuneration model. Additionally, advisers taking client orders for VA trades and asset managers placing orders for VA trades may fall within the above scope.
“Provision of VA Custodian Services” – The VA Custodian Consultation Paper proposes to define the “provision of VA Custodian Services” as, by way of business, the safekeeping of VAs or instruments enabling the transfer of VAs of clients (including but not limited to private keys or similar instruments, such as smartcards or authentication credentials for accessing the private keys) on behalf of clients. The holding of one’s own VAs and associated private keys are excluded from the above scope.
Further details regarding the scope of the legislative proposals can be found hereinbelow:
| VA Dealing | VA Custodians | |
| Licensing requirement | A SFC licence is required to carry on a business of dealing in VAs in Hong Kong. | A SFC licence is required for businesses providing VA custodian services in Hong Kong. |
| In-scope entities | Existing SFC intermediaries offering VA dealing; SFC-licensed VA trading platforms (“VATP”). | Associated entities of SFC-licensed VATPs; banks, subsidiaries of locally incorporated banks, stored value facility operators; SFC-licensed/registered fund managers to the extent they safekeep client VAs or private keys. |
| Exemptions from licensing requirements | Stablecoin issuers licensed by the Hong Kong Monetary Authority (“HKMA”) under the Stablecoins Ordinance for primary market offering or redemption of their own stablecoins. | SFC/HKMA-regulated entities which safekeep client VAs only incidentally to their principal activities and do not hold private keys.
Stablecoins issued by and in the custody of HKMA-licensed stablecoin issuers (regardless of private key custody arrangements). Bank security vaults or security companies storing encrypted or deactivated private key backups, and technical service providers that do not safekeep private keys.
|
Regulatory Proposals
Main aspects of the proposed regulatory framework are found in the table below:
| VA Dealing | VA Custodians | |
| Eligibility and “fit and proper” | A VA dealing or custodian licensee (“Licensee”) must be a locally incorporated company or a registered non-Hong Kong company.
The Licensee, its substantial shareholders and individuals carrying out the relevant regulated activities must satisfy the fit and proper requirements of the SFC. Custodian service applicants are additionally assessed on relevant experience, qualifications, and financial integrity. |
|
| Governance and personnel | At least two SFC-approved responsible officers (or two HKMA-approved executive officers, as applicable). These personnel will be responsible for ensuring compliance with regulatory requirements (including AML/CTF requirements).
Each executive director of the Licensee must be an approved responsible officer or executive officer. The Licensee should establish an appropriate corporate governance structure with personnel having the necessary knowledge and experience. Custodian services only: Licensed individuals are required for staff performing custody functions beyond clerical roles. |
|
| Financial resources | Share capital: at least HK$5 million (fully paid up).
Liquid capital: up to HK$3 million, plus an amount at least equivalent to 12 months’ operating expenses. Banks licensed by the HKMA are excluded from these tests. |
Share capital: at least HK$10 million (fully paid up).
Liquid capital: up to HK$3 million. Additional financial resources requirements proportionate to operating expenses and business scale are under consideration. Banks licensed by the HKMA are excluded from these tests. |
| Permitted activities | Activities within the definition of “dealing in VAs”; as well as deposits and withdrawals of client VAs to and from licensee wallet addresses. | Safekeeping of VAs and/or private keys (or similar instruments); as well as functions integral to VA services such as deposits, withdrawals, and settlement. |
| Types of VAs allowed | Requirements broadly follow those applicable to VATPs. In particular:
(a) Licensees should conduct prior reasonable due diligence on all VAs. (b) For retail clients, offerings limited to high liquidity tokens included in at least two independent market indices, plus stablecoins issued by HKMA-licensed issuers. |
No specific asset-type restrictions, subject to AML/CTF compliance.
For private key custodians, the Licensee’s technical custody infrastructure should be able to take custody of the specific token. |
| Risk management | Licensees must establish appropriate risk management policies for AML/CTF and other risks arising out of their business. Appropriate technological solutions, such as blockchain tools that enable the tracking of VAs and flagging of suspicious transactions, are required. | |
| Client asset protection | Client assets must be properly segregated; assets may be required to be kept with an SFC-licensed VA custodian in Hong Kong. | Aligned with VATPs, licensed custodians must meet rigid requirements relating to private key management, cybersecurity, and business continuity. |
| Investor protection and suitability | Safeguards should be put in place, including: assessing clients’ VA knowledge; providing adequate training; conducting client risk assessments and profiling; setting client exposure limits; and disclosing actual or potential conflicts of interest. | No specific investor suitability measures proposed beyond general obligations. |
| Record keeping and reporting | Proper record-keeping; providing information to the SFC/HKMA (e.g., wallet addresses, scope/nature of business, service types); financial reporting and disclosure (of audited accounts). However, financial reporting requirements do not apply to HKMA-licensed banks.
Custodian services only: Record keeping must specifically cover transactions and fund flows. |
|
| Additional Services and Integration | Services beyond dealing (advisory, asset management, staking, borrowing, lending, margin trading) require separate SFC or HKMA approvals. | Ancillary services like staking may be permitted subject to case-by-case SFC or HKMA approval.
|
| Multi-jurisdictional considerations | Authorities may allow licensed VA dealers to acquire or dispose of VAs for clients via non-SFC-licensed VATPs regulated in other jurisdictions or other liquidity providers, subject to certain safeguards (enhanced counterparty/AML due diligence, robust risk disclosures, and custody with SFC-licensed/registered VA custodians in Hong Kong). | N/A. |
| Penalties and enforcement | Unlicensed dealing: up to HK$5 million fine and 7 years imprisonment.
Conscious advertisement of unlicensed services: fine at level 5 (currently at HK$50,000) and 6 months imprisonment. Non-compliance with AML/CTF requirements: up to HK$1 million fine and 2 years imprisonment. Fraudulent behavior: up to HK$10 million fine and 10 years imprisonment. Fraudulent or reckless misrepresentation inducing others to engage in VA transactions: fine of HK$1 million and 7 years imprisonment. Administrative sanctions include licence suspension, revocation, reprimand, and pecuniary penalties up to HK$10 million. |
|
| Transitional arrangements | No transitional arrangements have been proposed, with the regime to become fully effective upon commencement. Market participants are encouraged to engage SFC/HKMA early to initiate pre-application processes. | |
Analysis and Takeaways
Regulatory Framework for Virtual Asset Services in Hong Kong
Hong Kong is taking the necessary next step by extending supervision beyond VATPs to capture over-the-counter dealing and custodianship activities. This expansion addresses regulatory vulnerabilities and raises baseline standards across AML/CTF and investor protection measures. If implemented with appropriate proportionality, the reforms can strengthen market integrity without constraining growth. Successful execution will depend on addressing several key considerations:
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
Note
[1] “VAs” are given the same meaning as set out in section 53ZRA of the AMLO.