News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
 Stevenson, Wong & Co.
News Updates
Find out all about our firm’s latest news updates below. To learn more about any individual item, please contact us here.
Background
On 2 September 2021, the Singapore Exchange (the “SGX”) has released the “Responses to Comments on Consultation Paper (the “Consultation Paper”) on SPACs” (the “Responses”) in relation to its proposed listing framework for SPACs. It allows SPACs to be listed on the Mainboard (“Mainboard”) of Singapore Exchange Securities Trading Limited (“SGX-ST”) with effect from 3 September 2021, making it the very first Exchange to allow SPAC listings in Asia.
This article follows up with our news update in May 2021 on the Consultation Paper. In particular, we discuss about the main commercial features introduced by the Singapore Exchange in their SPACs framework, as summarised in the Responses.
Key features of SGX SPACs
Relaxation of Original Proposals
In the Responses, SGX agreed to relax some of the original proposals in the Consultation Paper in relation to the SPAC’s listing framework. The below table sets out a comparison between the two:
| Original Proposals | Conclusions | |
| Minimum market capitalisation requirement | S$300 million | S$150 million (equivalent to approximately US$111 million or approximately HK$864 million) |
| Timeframe for completing the business combination | Proposed a maximum timeframe of 36 months for a SPAC to complete the business combination from the date of listing | Imposed a limit of 24 months from the date of listing for the SPAC to complete the business combination, but it may be extended for up to 12 months through (a) automatic extension or (b) extension with approvals from SGX and shareholders |
| Redemption rights of all independent shareholders | To allow shareholders which voted against the business combination to redeem their shares | All shareholders, whether voted for or against the business combination, will be entitled to redeem their shares |
| Independent valuation | Independent valuation of the target is necessary | Independent valuation of the target is necessary if (a) a PIPE (private investment in public equity) investment is absent or (b) the target is a mineral, oil or gas company or property investment / development targets |
| Public float requirement | 500 public shareholders | 300 public shareholders, in which 25% of the total number of issued shares of the SPAC must be held by the public shareholders |
| Choice of jurisdiction of incorporation of SPAC | Incorporation of SPAC must be in Singapore | Incorporation of SPAC need not be in Singapore |
| Issue price for SPAC units | Proposed S$10 per SPAC unit and any warrant issued must be non-detachable from the underlying ordinary shares of the SPAC for trading on SGX | S$5 per SPAC unit and any warrant issued will be detachable from the SPAC’s underlying ordinary shares which permits the warrants to trade separately on the SGX |
SPAC Sponsors have “More Skin in the Game”
Moratorium
Unlike the traditional IPO, there is a moratorium (akin to a lock-up undertaking) on the 100% of shares of the sponsor from IPO to the completion of the business combination, and a further 6-month moratorium on 50% of their shareholdings after the completion of business combination. The aim is to align the interests of the key persons and other shareholders that involved in the IPO and ensure the commitment of the key persons towards the long-term success after the business combination.
Minimum Equity Participation
In response to the market feedback, SGX also imposed a minimum equity participation on the SPAC’s sponsor and management team as to ensure they have “skin-in-the-game”. They are required to subscribe the shares and/or warrants, as the case may be, in accordance with the following requirements:
| Market capitalisation of the SPAC (S$ million) |
Proportion of subscription |
| 150 ≤ M ≤ 300 | 3.5% |
| 300 ≤ M ≤ 500 | 3.0% |
| M ≥ 500 | 2.5% |
Limit on Sponsor’s Promote
When the sponsors form a new SPAC, it shall have an opportunity to invest in a SPAC at nominal or without consideration for sponsoring the SPAC (i.e. sponsor’s promote). SGX has limited the sponsoring to 20% of the issued share capital of the SPAC immediately after the IPO.
Measures pending and in relation to Business Combination
Gross Proceeds in Escrow Account
In addition, SGX also required the SPAC to allocate at least 90% of the gross proceeds raised from its IPO in an escrow account immediately upon the IPO. Except for business combination, liquidation or other specified circumstances, the escrow account shall not be drawn down, and the account shall be operated by an independent escrow agent.
Approvals of Business Combination by Independent Directors and Shareholders
After listing, in addition to the permitted timeframe as discussed above to complete the business combination, SGX further required the business combination to be approved by a simple majority of independent directors and an ordinary resolution passed by the shareholders at a general meeting.
Liquidation Distribution Right
The SPAC will be liquidated if it: (a) fails to complete a business combination within the permitted time frame as discussed above; or (b) fails to obtain specific shareholders’ approval for an event of material change regarding the profile of the founding shareholders and/or the management team before the completion of the business combination. The pre-IPO investors are entitled to participate in the liquidation distribution while the sponsor and the management team must waive their liquidation distribution rights under the SGX’s SPACs framework.
Analysis and Takeaways
The SPAC listings on SGX is the first Exchange that allows “blank check” companies to list in Asia. We note that the usual features for SPAC listings are present in SGX SPACs, such as minimum market capitalisation, the focus on the management’s profile, 24-month de-SPAC time limit, 90% use of proceeds on business combination, 90% IPO proceeds escrow and shareholders’ approval of the business combination. In overall, the SGX’s SPAC listing requirements are relatively less stringent.
The introduction of SPACs by SGX makes Singapore stay one step ahead of Hong Kong in implementing its SPAC regime. In this regard, the Hong Kong Stock Exchange has also just released its SPAC conclusion paper on 17 September 2021. Such development can be seen as an increasing confluence of promoters and investors in facilitating IPOs and listings.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This newsletter is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
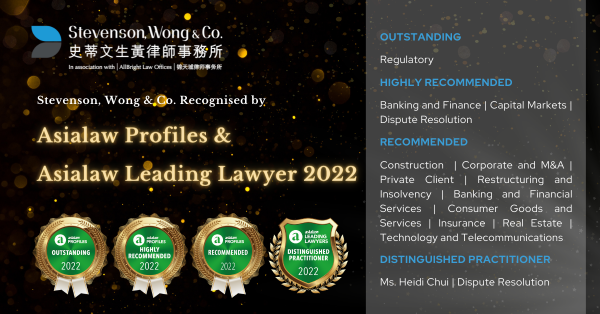
We are pleased to announce that our firm has been recognised as an Outstanding firm and is ranked across 13 practice areas/ sectors in Asialaw Profiles 2022. In addition, our Partner and Head of Litigation and Dispute Resolution department, Ms. Heidi Chui, has been recognised by Asialaw Leading Lawyers 2022 as Distinguished Practitioner in Dispute Resolution.
About Stevenson, Wong & Co.
Founded in 1978, Stevenson, Wong & Co. is a forward-looking, full-service law firm with over 170 experienced lawyers and staff. As the associated firm with one of the nation’s largest full-service law firms, AllBright Law Offices, and one of the founding members of INTERLAW, Stevenson, Wong & Co. connects China to the world and supports clients facing a variety of business and legal issues with effective solutions.
About Ms. Heidi Chui
Ms. Chui is the firm’s head of Litigation and Dispute Resolution Department and Banking and Finance Department. She has served as the internal legal advisor of several Chinese banks.
Ms. Chui specializes in commercial litigation, arbitration, insolvency, restructuring, banking and finance, employment law and regulatory enforcement. She has extensive international and cross-border experiences in advising liquidators, receivers, official receivers, creditors and other professionals in charge of insolvency and bankruptcy matters in relation to debt restructuring and cross-border asset tracing. She also acts for banks, borrowers, insurance companies, property management companies, funds, listed companies and financial institutions.
Please contact Mr. Willy Cheng or Ms. Heidi Chui for any enquiries or further information.
We are delighted to announce that our Partner and Head of Corporate Finance, Mr. Hank Lo, has been recognised by IFLR1000’s Asia Pacific 2021-22 edition as Highly Regarded Leading Lawyer in Capital Markets: Equity.
IFLR1000 evaluates 5,000+ law firms and lawyers based on transactional evidence and client feedbacks. Lawyers are recognized for advising on some of the most complex or innovative transactions in their markets and receiving excellent feedback for their work.
About Mr. Hank Lo
Hank heads the Corporate Finance Practice in the firm. He specializes in capital markets, corporate finance, mergers and acquisitions and representative matters. Hank has significant experience advising issuers, sponsors and underwriters on initial public offerings on both the main and GEM boards of The Stock Exchange of Hong Kong Limited; advising publicly listed companies on a broad range of corporate finance transactions; advising private equity funds, venture capital funds and Hong Kong listed companies on their investments in and exits from companies with an emphasis on China; and providing advice to companies in Greater China on representative matters including property transactions, foreign investment and initial public offerings.
About IFLR1000
The IFLR1000 is an international legal market’s guide focusing on financial and corporate law firms. Since 1990, IFLR1000 has published over 750 practice area rankings across 235 jurisdictions globally.
For any enquiries, please contact our Partner Mr. Hank Lo or click here to see the ranking.
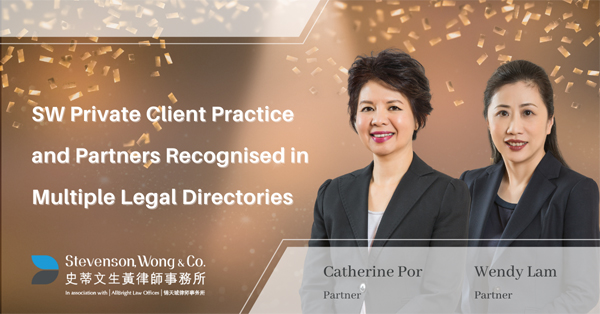
We are pleased to announce that our SW Private Client Practice and Partners, Ms. Catherine Por and Ms. Wendy Lam, have recently received the following awards:
About SW Private Client:
Our award-winning SW Private Client team is recognised as one of the leading matrimonial and family law practices in Hong Kong. Our reputation is based on our expertise in the following areas:
• Family Practice
We are experienced in dealing with all aspects of contentious and non-contentious family matters including the preparation of pre-nuptial and post-nuptial agreements, conducting cases concerning custody and maintenance of children, financial disputes between divorcing couples and third parties, cross border and jurisdiction and forum disputes, and abduction of children. Additionally, three of the family court judges in Hong Kong, one of whom is a judge of the Court of First Instance, are former members of this firm.
• Wills, Probate and Succession Planning, Trust Advisory and Wealth Planning
Our specialized team on family wealth and succession planning has expertise and extensive experience in providing practical advice and solutions to private clients of different backgrounds, including entrepreneurs, executives, expatriates and high net worth individuals in their wealth succession, asset preservation, trust and estate planning. The team also handles applications for grant of representation for estates involving assets in Hong Kong and multiple jurisdictions.
• Committee Work for MIPs
With the aging population in Hong Kong, and with the increase in rates of dementia and special needs persons, we have gained specialized in-depth experience in preparing complicated Enduring Powers of Attorney and handling cases of Committee work for mentally incapacitated persons. We assist applicants in making applications to the Court for the appointment of Committees as well as advising Committees on different aspects under the Mental Health Ordinance, Cap 136 of the Laws of Hong Kong.
We also have a team of accredited family and general mediators who regularly conduct mediations for a variety of family issues with notable success rates. We are also dedicated to the use of alternative dispute resolution, providing a timely and flexible means to resolve a variety of disputes by helping parties to reach a mutually agreed settlement.
Please contact Ms. Catherine Por or Ms. Wendy Lam for any enquiries or further information.
We are pleased to announce that we have been nominated in 11 categories at the Asian Legal Business (ALB) Hong Kong Awards 2021:
1. Civil Litigation Law Firm of the Year
2. Criminal Litigation Law Firm of the Year
3. Dispute Resolution Boutique Law Firm of the Year
4. Matrimonial and Family Law Firm of the Year
5. Real Estate Law Firm of the Year
6. Regulation and Investigations Law Firm of the Year
7. Transactional Boutique Law Firm of the Year
8. Hong Kong Law Firm of the Year
9. Dealmaker of the Year- Mr. Hank Lo
10. Managing Partner of the Year- Mr. Hank Lo
11. Woman Lawyer of the Year (Law Firm)- Ms. Heidi Chui
The Hong Kong Law Awards is the most significant and longest-running award presented by ALB. The awards aim to recognize the outstanding achievements of private practitioners and in-house teams from Hong Kong and the region. Results will be announced at the virtual awards ceremony on 10 September 2021.
To view the full list of finalists, please click here.
For further information, please contact our Partners Mr. Willy Cheng.
Background
On 7 August 2020, The Stock Exchange of Hong Kong Limited (the “Exchange”) published a consultation paper as to its proposal to review the Rules Governnig the Listing of Securities on the Exchange (the “Listing Rules”) relating to disciplinary powers and sanctions (the “Disciplinary Regime”). On 20 May 2021, the Exchange issued the Consultation Conclusions to the consultation exercise (the “Consultation Conclusions”). The new amendments aim at augmenting the range of reputational sanctions available and ensuring that disciplinary action can be brought against a broader range of individuals, including members of senior management, if they cause or knowingly participate in a contravention of the Listing Rules. The revised Listing Rules have taken effect from 3 July 2021. Set out below are some of the major changes to the Listing Rules.
Identifying New Relevant Parties and Defining Senior Management
The Exchange has added new classes of the relevant parties who may be subject to disciplinary actions and sanctions under Rule 2A.09 of the Listing Rules and Rule 3.10 of the GEM Listing Rules (the “Relevant Parties”). A definition of “Senior Management” has also been added to bring clarity.
| New Classes of
“Relevant Parties” |
The following new classes have been included as Relevant Parties:
(a) employees of professional advisers of listed issuers and their subsidiaries as a Relevant Party under the Listing Rules; (b) guarantors of structured products; (c) guarantors for an issue of debt securities; and (d) parties who give an undertaking to, or enter into an agreement with, the Exchange as Relevant Parties under the Listing Rules. |
| Definition of “Senior Management” | The new Rule 2A.09(2)(c) of the Listing Rules (Rule 3.10(2)(b) for GEM Listing Rules) defines “senior management” to include any person:
(a) occupying the position of chief executive, supervisor, company secretary, chief operating officer or chief financial officer, by whatever name called; (b) performing managerial functions under the directors’ immediate authority; or (c) referred to as senior management in the listed issuer’s corporate communication or any other publications on the Exchange’s website or on the listed issuer’s website. |
Amendments relating to a PII Statement
One of the existing sanctions under the previous Listing Rules is to issue a public statement that the retention of office by the director is prejudicial to the interests of investors (a “PII Statement”).
The new amendments extend the Exchange’s power to issue PII Statements by abolishing the high threshold of establishing “wilful” or “persistent” failure by a director to discharge his responsibilities under the Listing Rules. Under the new Listing Rules, a PII Statement can be made where the Exchange is satisfied that the individual’s occupying of office “may cause prejudice” to the interests of investors. With the removal of the “wilful” or “persistent” threshold, the Exchange is afforded greater flexibility to attach appropriate sanction to the misconduct.
PII Statement can now be issued against wider classes of individuals. With the new amendments, not only the directors of a listed issuer but also the senior management of the relevant listed issuer and even the director or senior management of any of its subsidiaries can be the subjects of a PII Statement. Further, the Exchange clarifies that a PII Statement can be made whether or not the individual continues in office at the time the PII Statement is made.
Enhancingfollow-on actions after making of a PII Statement
In case of more serious misconduct, the Exchange may direct follow-on actions at the same time a PII Statement is made. To further the effectiveness of a PII Statement, where an individual continues to be a director or senior management of the named listed issuer after a PII Statement has been made against him, the Exchange can order denial of facilities of the market to that listed issuer for a specified period. If there are significant problems in a listed issuer’s internal controls, this sanction may be imposed until the completion of an internal control review from a external professional adviser and the implementation of adequate and effective internal controls to ensure the compliance of the Listing Rules. The “wilful” or “persistent” threshold for ordering the denial of facilities of the market is also removed.
In addition, the Exchange requires named listed issuer to include a reference to the PII Statement in all its announcements and corporate communications unless and until the individual subject to a PII Statement with follow-on action is no longer its director or senior management member.
Extending Disclosure in Listing Documents and Annual Reports
The scope of disclosure on public sanctions towards senior management and directors is extended to the listing applicants’ listing documents and listed issuers’ annual reports to include full particulars of any public sanctions made against their directors or members of senior management (current and/or proposed) by statutory or regulatory authorities. The new scope of disclosure increases market transparency and makes the information more readily available to the public.
Introducing the Director Unsuitability Statement
Director Unsuitability Statement is introduced for the most egregious or severe cases of misconduct. Where a director fails to discharge his responsibility under the Listing Rules in a serious manner or repeatedly, the Exchange has the power to publicly state that the director is unsuitable to occupy a position as director or within senior management of a named listed issuer or its subsidiaries. The rules on follow-on actions, disclosure, and publication requirements apply equally to the Director Unsuitability Statement.
Imposing Secondary Liability
The rule changes allow the Exchange to impose sanctions on the Relevant Parties which have caused by action or omission or knowingly participated in a contravention of the Listing Rules. In particular, company secretaries, who are considered members of senior management, as well as professional advisers to the listed issuers, are also subject to secondary liability. The Exchange, however, made a note to clarify two matters. First, the imposition of secondary liability on solicitors and certified public accountants in private practice only covers circumstances that are agreed between the Exchange and the professional regulatory bodies. Second, the Exchange will take into account whether the party has knowingly or recklessly facilitated or participated in a breach of the Listing Rules or any undertaking given or any agreement with the Exchange when determining the secondary liability of the “Relevant Parties”.
Obligation to provide complete, accurate and up-to-date information
The rule binds a party which is providing information to the Exchange regarding a matter or interacting with the Exchange, whether proactively or in response to an enquiry. It obligates the party to provide information that is as complete, accurate and up-to-date as possible.
Minor Rule Amendments
Other minor rule amendments have also been introduced:
1. Extending the ban on professional advisers to cover banning of representation of any or a specified party;
2. Placing an obligation on professional advisers to use all reasonable efforts to ensure that their clients understand and are advised as to the scope of and their obligations under the Listing Rules when acting in connection with Listing Rules matters on which they are instructed to advise. Professional advisers should also refrain from knowingly provide information to the Exchange which is false or misleading in a material particular;
3. Using “business day” as the benchmark for counting the periods for filing review applications, and for requesting or providing written reasons for decisions;
4. Requiring all review applications to be served on the Secretary to the Listing Committee or the Secretary to the Listing Review Committee;
5. Counting the period for filing review applications from the date of issue of the decision or the written reasons;
6. Counting the period for requesting written reasons from the date of issue of the decision; and
7. Counting the period for providing written reasons from the date of receipt of the request.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This newsletter is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.