News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.

News
Find out all about our firm’s latest news and activities below. To learn more about any individual item, please contact us here.
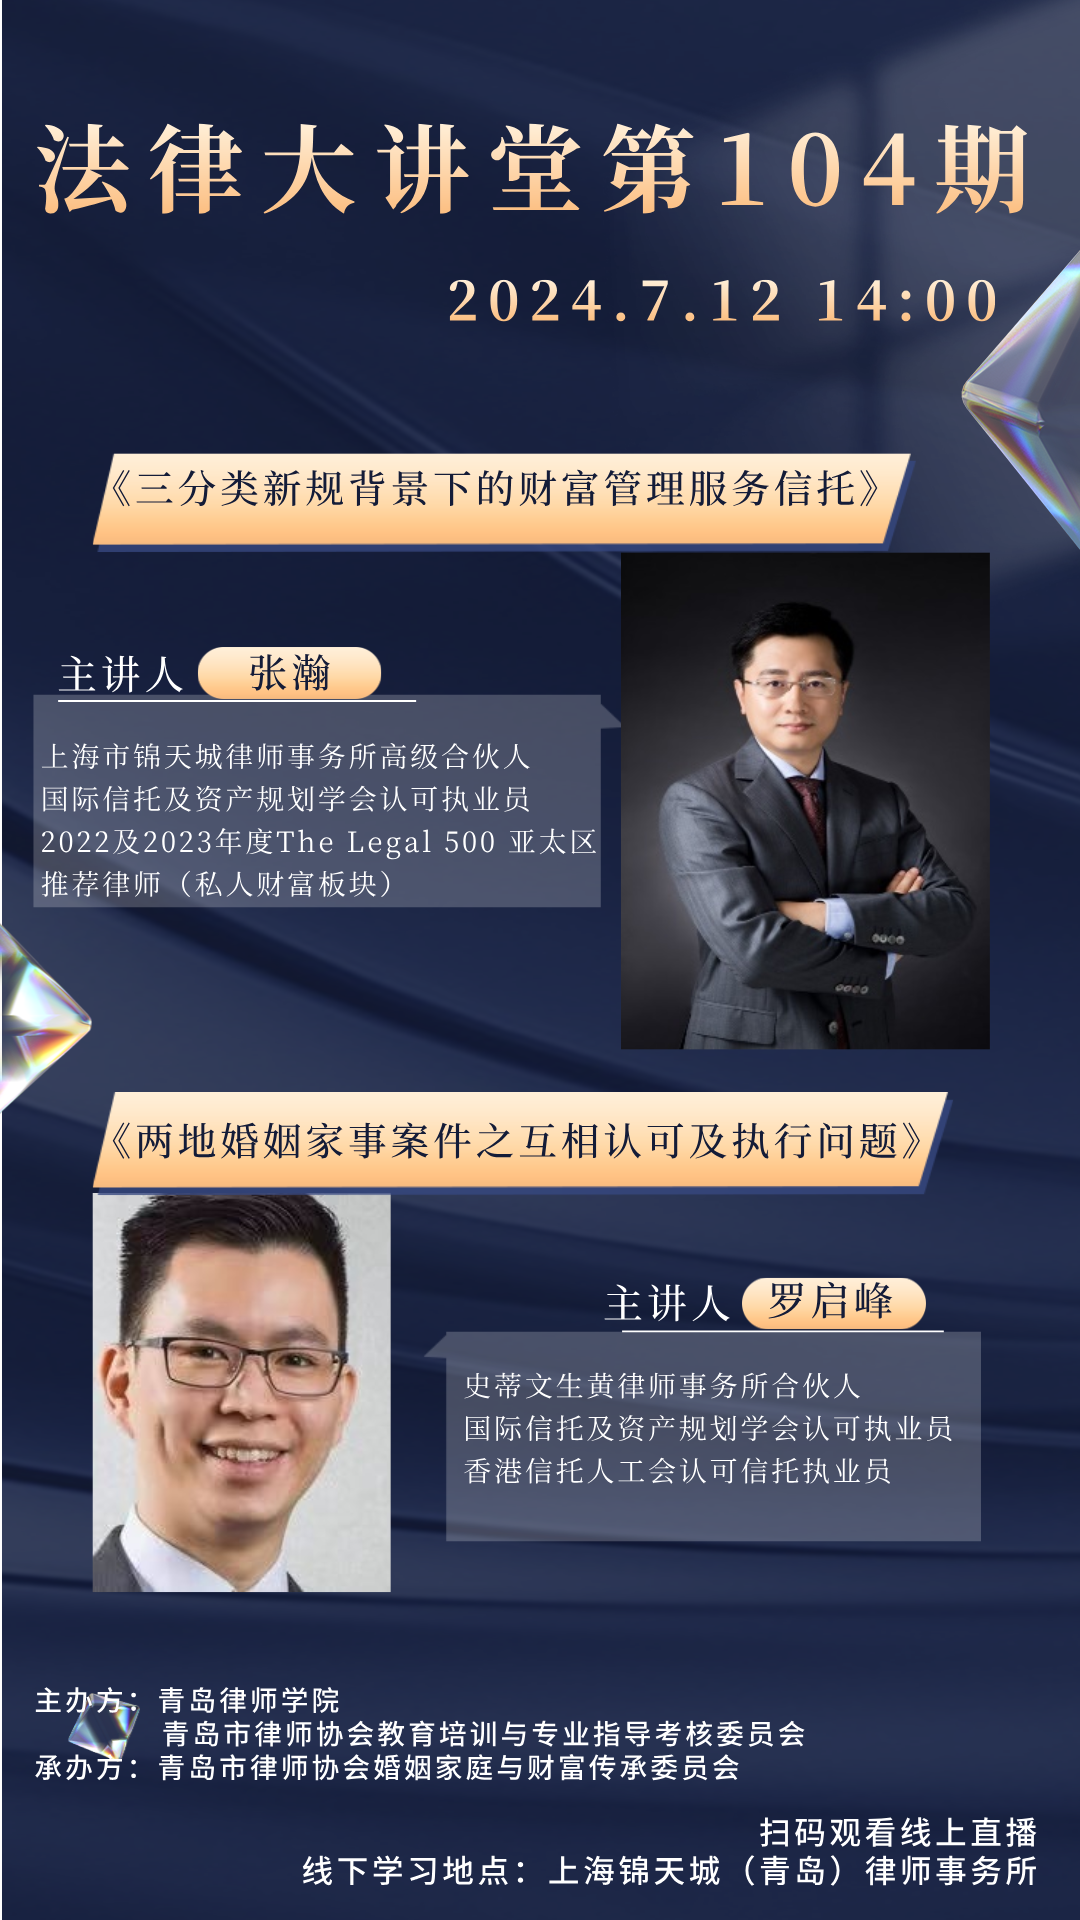
On 12 July 2024, our Partner, Calvin Lo, was a speaker at the Qingdao Lawyers Association’s 104th seminar titled “Marriage and Trusts”. The event, moderated by Xiao Xuejing, Director of the Marriage, Family, and Wealth Inheritance Committee of the Municipal Lawyers Association, attracted over 300 legal professionals
…
Calvin, alongside Zhang Han, Senior Partner at AllBright Law Offices discussed the new regulatory framework for wealth management services’ trusts and the mutual recognition and enforcement of family law cases across jurisdictions.
Calvin’s topic on “Mutual Recognition and Enforcement Issues of Family Law Cases Across Regions” addressed the complexities surrounding the mutual recognition and enforcement of family law cases between different regions. He provided a comprehensive overview of the legal frameworks and fundamental principles governing marriage and family law cases, detailing the factors that determine which court has jurisdiction over a case. Furthermore, he discussed how courts in different jurisdictions can recognize and enforce each other’s judgments, including those related to divorce, custody, and asset division.

For further information about the event, please contact our Partner Calvin Lo.
On 28 March 2024, The Securities and Futures Commission of Hong Kong (the “SFC”) published a consultation paper (the “Consultation Paper”) inviting public feedback on its proposals to (i) introduce a statutory scheme of arrangement and compulsory acquisition mechanism for real estate investment trusts (“REITs”), and (ii) enhance the Securities and Futures Ordinance (the “SFO”) market conduct regime (“Market Conduct Regime”) for listed collective investment schemes (“CIS”). The consultation period concluded on 27 May 2024, with the SFC expected to issue consultation conclusive papers soon, aiming to finalize the legislative process by December 2025.
…
Currently, REITs are not subject to the statutory procedures outlined in the Companies Ordinance (“CO”). Recognizing the industry’s need for a more direct exit strategy akin to the CO, the SFC proposes the addition of a new section in the SFO to establish a fair and equitable statutory framework for schemes of arrangement and compulsory acquisitions to facilitate the corporate restructuring and privatization of REITs. This proposal draws reference from Part 13 of the CO with tailored adjustments to suit the nature and features of REITs, their management companies, trustees, and unitholders.
The proposed new sections under the SFO are broadly in line with the existing provisions in the CO, with similar requirements in respect of due disclosure, approval thresholds and court sanction, as outlined below:
| Proposals | Details |
| Steps to establish a REIT scheme | Step 1: Approval by unitholders or creditors at a meeting (“Meeting”), subject to the following voting thresholds:
i. For a scheme entered into with creditors – Requires a majority in number representing at least 75% in value of the creditors present and voting. ii.For a scheme entered into with unitholders – · For arrangements involving a takeover or general offer, requires: (1) at least 75% of the voting rights of the unitholders present and voting; and (2) the votes against the arrangement do not exceed 10% of the total voting rights attached to all disinterested unitholders. · For other arrangements, requires: (1) at least 75% of the voting rights of the unitholders present and voting; and (2) unless the court orders otherwise, a majority in number of the unitholders present and voting. Step 2: Upon obtaining the necessary approval, apply for a court sanction for the scheme. |
| Application to the court to convene a Meeting | The REIT’s management company, trustee, unitholders or creditors may apply to the court to convene a Meeting of the unitholders or creditors, or both, to deliberate on the proposed arrangement or compromise and to seek the court’s approval. |
| Disclosure of material interests to unitholders / creditors | The REIT’s management company, trustee. and each director must disclose any material interests related to the arrangement or compromise in an explanatory statement that will be distributed to the unitholders or creditors. |
| Legal binding effect | A court-sanctioned arrangement or compromise is legally binding on all relevant parties, including the REIT’s management company, trustee, unitholders and creditors. |
| SFC filing of court order | The effectiveness of the court-sanctioned arrangement or compromise is conditioned upon the delivery of a copy of the court order to the SFC for filing. |
The proposed compulsory acquisition provisions which apply to REITs closely resemble those in Part 13 of the CO, i.e. a takeover offer by an offeror (“offeror”) and a general offer to buy back shares by the repurchasing company (“repurchaser”) which may be completed by way of a “squeeze-out” or a “sell-out”, subject to modifications to allow a management company or trustee of an offeror or repurchaser to perform certain functions on behalf of the REIT during a compulsory acquisition.
| Proposals | Details | |
| “Squeeze-out” provisions | An offeror or repurchaser, having acquired or bought back at least 90% in number of the units in connection with the offer, is entitled to give notice to the minority unitholders of its intention to acquire or repurchase the remaining units. | |
| “Sell-out” provisions | Minority unitholders are entitled to require an offeror or repurchaser to acquire or buy back the remaining units if the offeror or repurchaser has acquired at least 90% in number of the units. | |
| REIT-specific modifications in relation to compulsory acquisition | Issuance of acquisition notice by the offeror or repurchaser of REIT | The management company or trustee of the offeror or repurchaser can perform the following functions on behalf of the REIT during a compulsory acquisition:
· Apply to the court for an order authorising the issuance of an acquisition notice to buy out the remaining units; and · Apply to the SFC for directions regarding the delivery of acquisition notice when a unitholder’s Hong Kong address is absent from the register of holders. The proposed manner and timing for an offeror or repurchaser to give an acquisition notice, set out below, aligns with the CO: · In a “squeeze-out”: · Notice to minority unitholders – The offeror or repurchaser must notify minority unitholders to buy out their units within the earlier of (i) 3 months beginning on the day after the end of the offer period of the takeover offer or general offer; or (ii) 6 months beginning on the date of the takeover offer or general offer. · Rights of dissenting unitholders – Dissenting unitholders can apply to the court to determine whether the offeror or repurchaser is entitled and bound to acquire or buy back the units. · In a “sell-out”: · Notice to minority unitholders – The offeror or repurchaser must give notice to the minority unitholders of their rights to be bought out within 1 month after the first day on which they are entitled to a sell-out. If the notice is given before the end of the offer period of the takeover offer or general offer, it must state that the offer is still open. · Minority unitholders in exercising their rights – Minority unitholders have 3 months to exercise their rights in a sell-out after the later of (i) the end of the offer period; or (ii) the notice date by the offeror or repurchaser. |
| Roles and responsibilities of a trustee in a compulsory acquisition | Due to the REIT’s lack of legal personality, the trustee is responsible for the following:
· Holding and handling the consideration paid by the offeror or repurchaser on trust for the entitled unitholders; and · In a takeover offer and compulsory acquisition – Registering the offeror as the holder of the acquired units; or · In a general offer for a unit buy-back – Cancelling the relevant units |
|
Definitions and interpretations
It is proposed that the interpretation section should adopt the definitions used in the CO with appropriate modifications and include additional terms (e.g. “management company” and “REIT”) to cater to the operation of a scheme in the context of a REIT.
The concept of “responsible person” of a company under section 3 of the CO will be extended to cover those of the management company to ensure accountability for contravention of or failure to comply with the new Parts of the SFO.
Deeming provisions
The proposed deeming provisions aim to empower a REIT, lacking a legal personality, to act through its trustee and/or management company (or its directors). This includes attributing actions, powers, voting rights, property, undertakings, liabilities, associated rights, and creditor relationships of the trustee and/or management company (or its directors) to the REIT.
The SFC’s proposed amendments seek to enhance market integrity and investor protection, with a focus on the obligations of the management company of the listed CIS (and CIS directors for corporate CIS), while streamlining the regulatory framework by not extending certain provisions in Part XV of the SFO to listed CIS and not including trustees and custodians of listed CIS into the various definitions in Parts XIII to XV of the SFO.
With reference to previous consultations, the SFC proposes expanding the scope of the following Parts of the SFO to explicitly cover only listed CIS and their management companies:
Additional changes will be implemented to support the aforementioned scope of various Parts of the SFO. These further revisions aim to clarify that all listed CIS (including those structured in corporate form) are subject to the Market Conduct Regime specific to listed CIS, as distinct from those for listed corporations, in order to avoid confusion and regulatory overlap. Moreover, adjustments will be made to the existing definitions under Part 1 of Schedule 1 to the SFO to cater for the unique nature of CIS.
As reflected in the Consultation Paper, the SFC has embarked on a major initiative to enhance the regulatory framework for REITs and CIS. The proposed reforms represent a comprehensive effort by the SFC to bring about an overall improvement in market conduct, integrity, and investor protection in the financial sector in Hong Kong.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
The Securities and Futures Commission (the “SFC”) issued a statement reminding the public that the non-contravention period for virtual asset trading platforms (VATPs) operating under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance (Cap 615) (“AMLO”) will come to an end on 1 June 2024. Operating a VATP in Hong Kong in breach of the AMLO would be a criminal offence and the SFC will take all appropriate actions against such breach.
…
Background
The SFC introduced a new licensing regime under the AMLO, effective from 1 June 2023. This regime mandates that all VATPs operating in Hong Kong must either obtain a license or be deemed-to-be-licensed during a non-contravention period under the transitional arrangements. The non-contravention period was established to provide pre-existing VATPs sufficient time to align their operations with the new regulatory standards without breaching the law. During this period, pre-existing VATPs could continue their activities while working towards full compliance with the SFC’s licensing requirements. The transitional arrangements aimed to balance the need for stringent regulatory oversight with the practicalities of transitioning existing market players to the new framework. Please see our news update on the circular on transitional arrangements of the new licensing regime for VATPs by the SFC on 31 May 2023 here.
Reminder for Investors
As the non-contravention period will come to an end on 1 June 2024, the SFC urges investors to conduct virtual asset transactions exclusively on the SFC-licensed VATPs only. Investors should verify the licensing status of VATPs via the “List of licensed virtual asset trading platforms” on the SFC’s website. It is crucial to note that deemed-to-be-licensed VATP applicants are not licensed by the SFC and may not eventually be granted formal licenses. If an application is returned or refused, the VATPs concerned will be required to close down their businesses in Hong Kong. The public can check the “List of applicants whose licence applications have been returned, refused or withdrawn” and the “List of closing-down virtual asset trading platforms” for updated information.
Reminder for Deemed-to-be-Licensed VATP Applicants
Deemed-to-be-licensed VATP applicants and their ultimate owners must fully meet the SFC’s regulatory requirements and licensing conditions. The SFC advises these applicants not to actively market their services or onboard new retail clients until they have demonstrated effective implementation of their policies, procedures, systems, and controls, which should be assessed by sufficiently qualified external assessor(s), to the SFC’s satisfaction and have been formally licensed. All VATPs and their ultimate owners must also adhere to relevant laws and regulations, including preventing Mainland Chinese residents from using their virtual asset services.
Deemed-to-be-licensed VATP applicants are subject to SFC’s supervisory, disciplinary, intervention and other applicable powers. In the coming months, the SFC will conduct on-site inspections of deemed-to-be-licensed VATP applicants to ascertain their compliance, with a focus on client assets safeguarding measures and know-your-client processes. Any non-compliance observed will result in swift refusal of their license applications and other regulatory actions as necessary.
Analysis and Takeaways
The SFC reminds the public that the non-contravention period for VATPs will end on 1 June 2024 and investors shall use only the SFC-licensed platforms. Investors should verify the licensing status of VATPs via the SFC’s website to avoid the risks associated with deemed-to-be-licensed applicants, who may not secure formal licenses and could be forced to close down their businesses. The SFC also stresses strict compliance with the regulatory requirements and licensing conditions for deemed-to-be-licensed VATP applicants.
Please contact our Partner Mr. Rodney Teoh for any enquiries or further information.
This news update is for information purposes only. Its content does not constitute legal advice and should not be treated as such. Stevenson, Wong & Co. will not be liable to you in respect of any special, indirect or consequential loss or damage arising from or in connection with any decision made, action or inaction taken in reliance on the information set out herein.
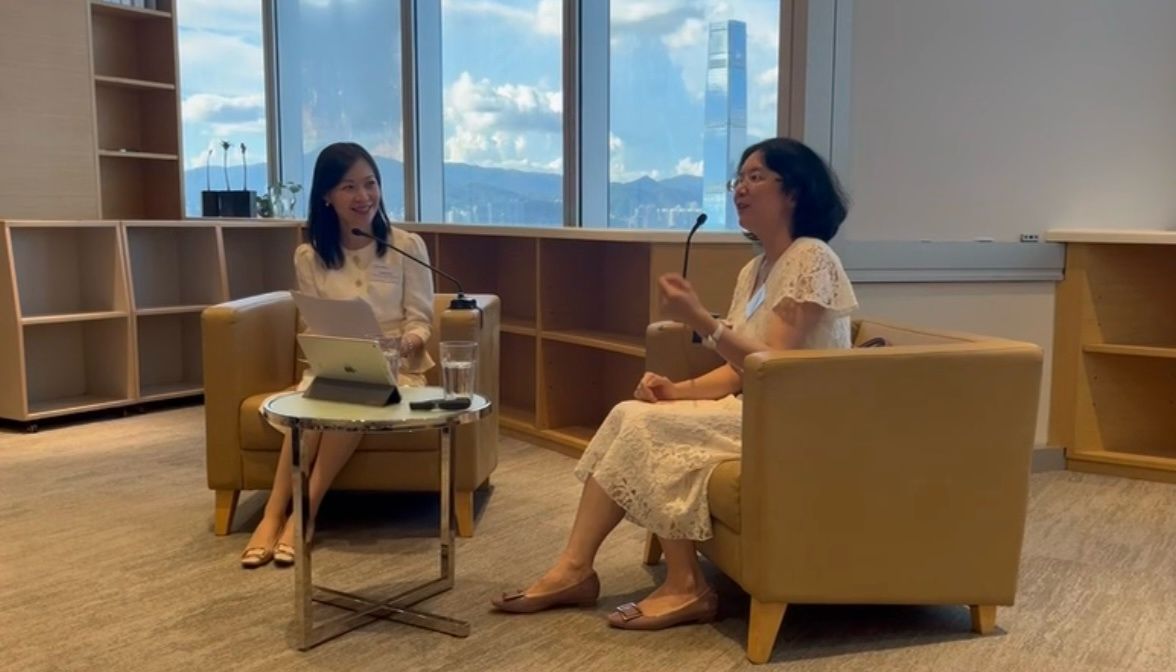
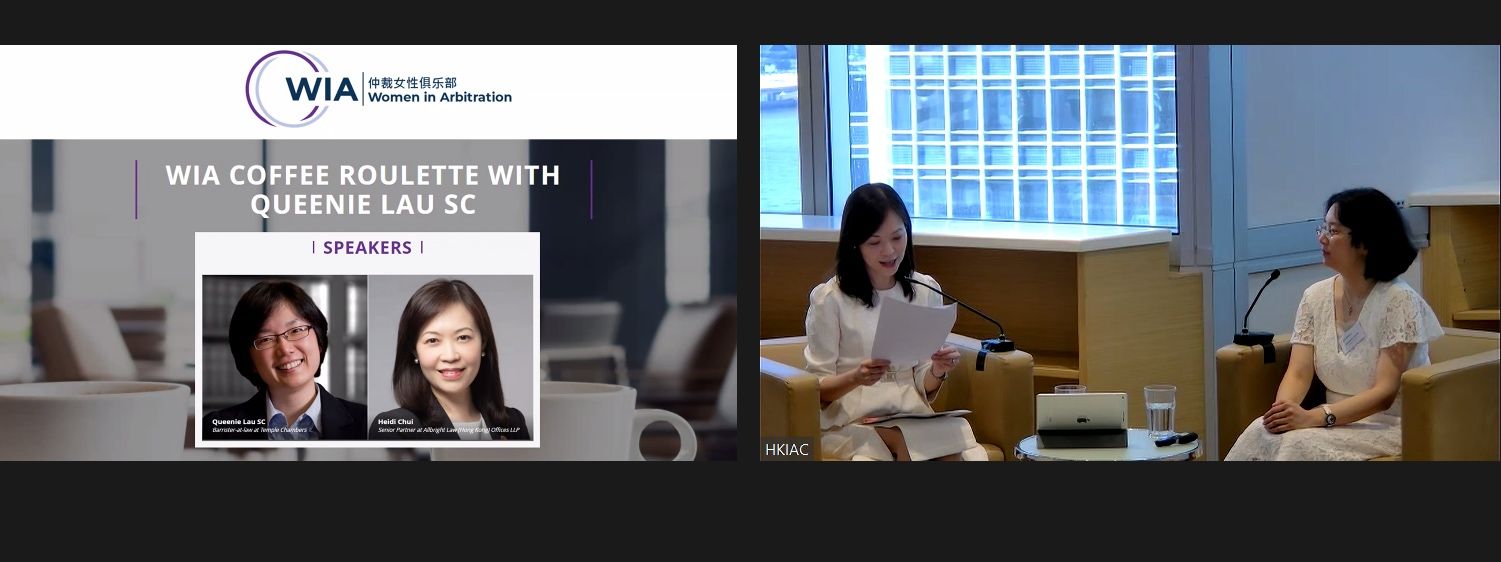
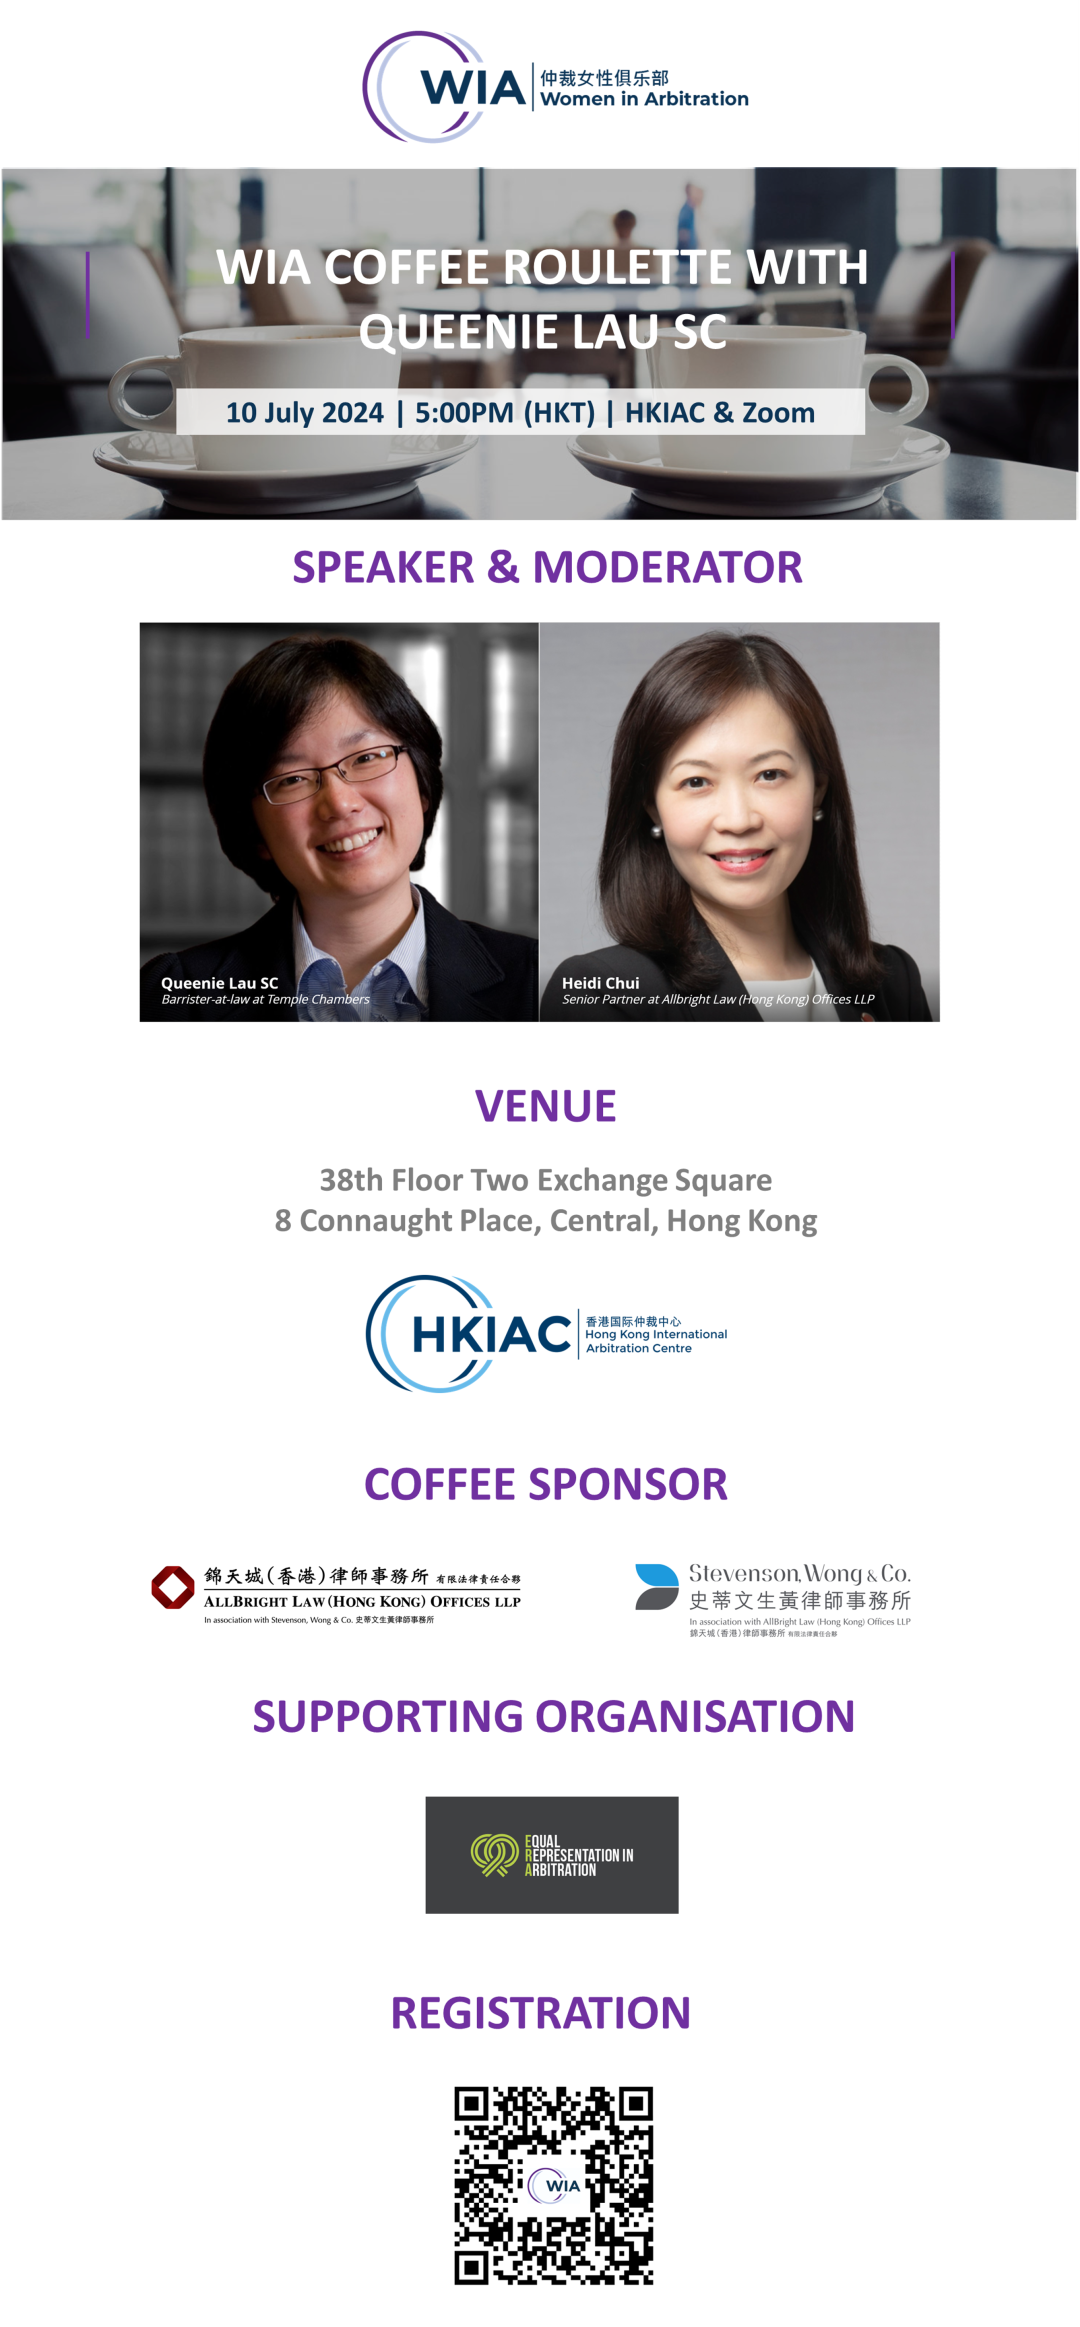
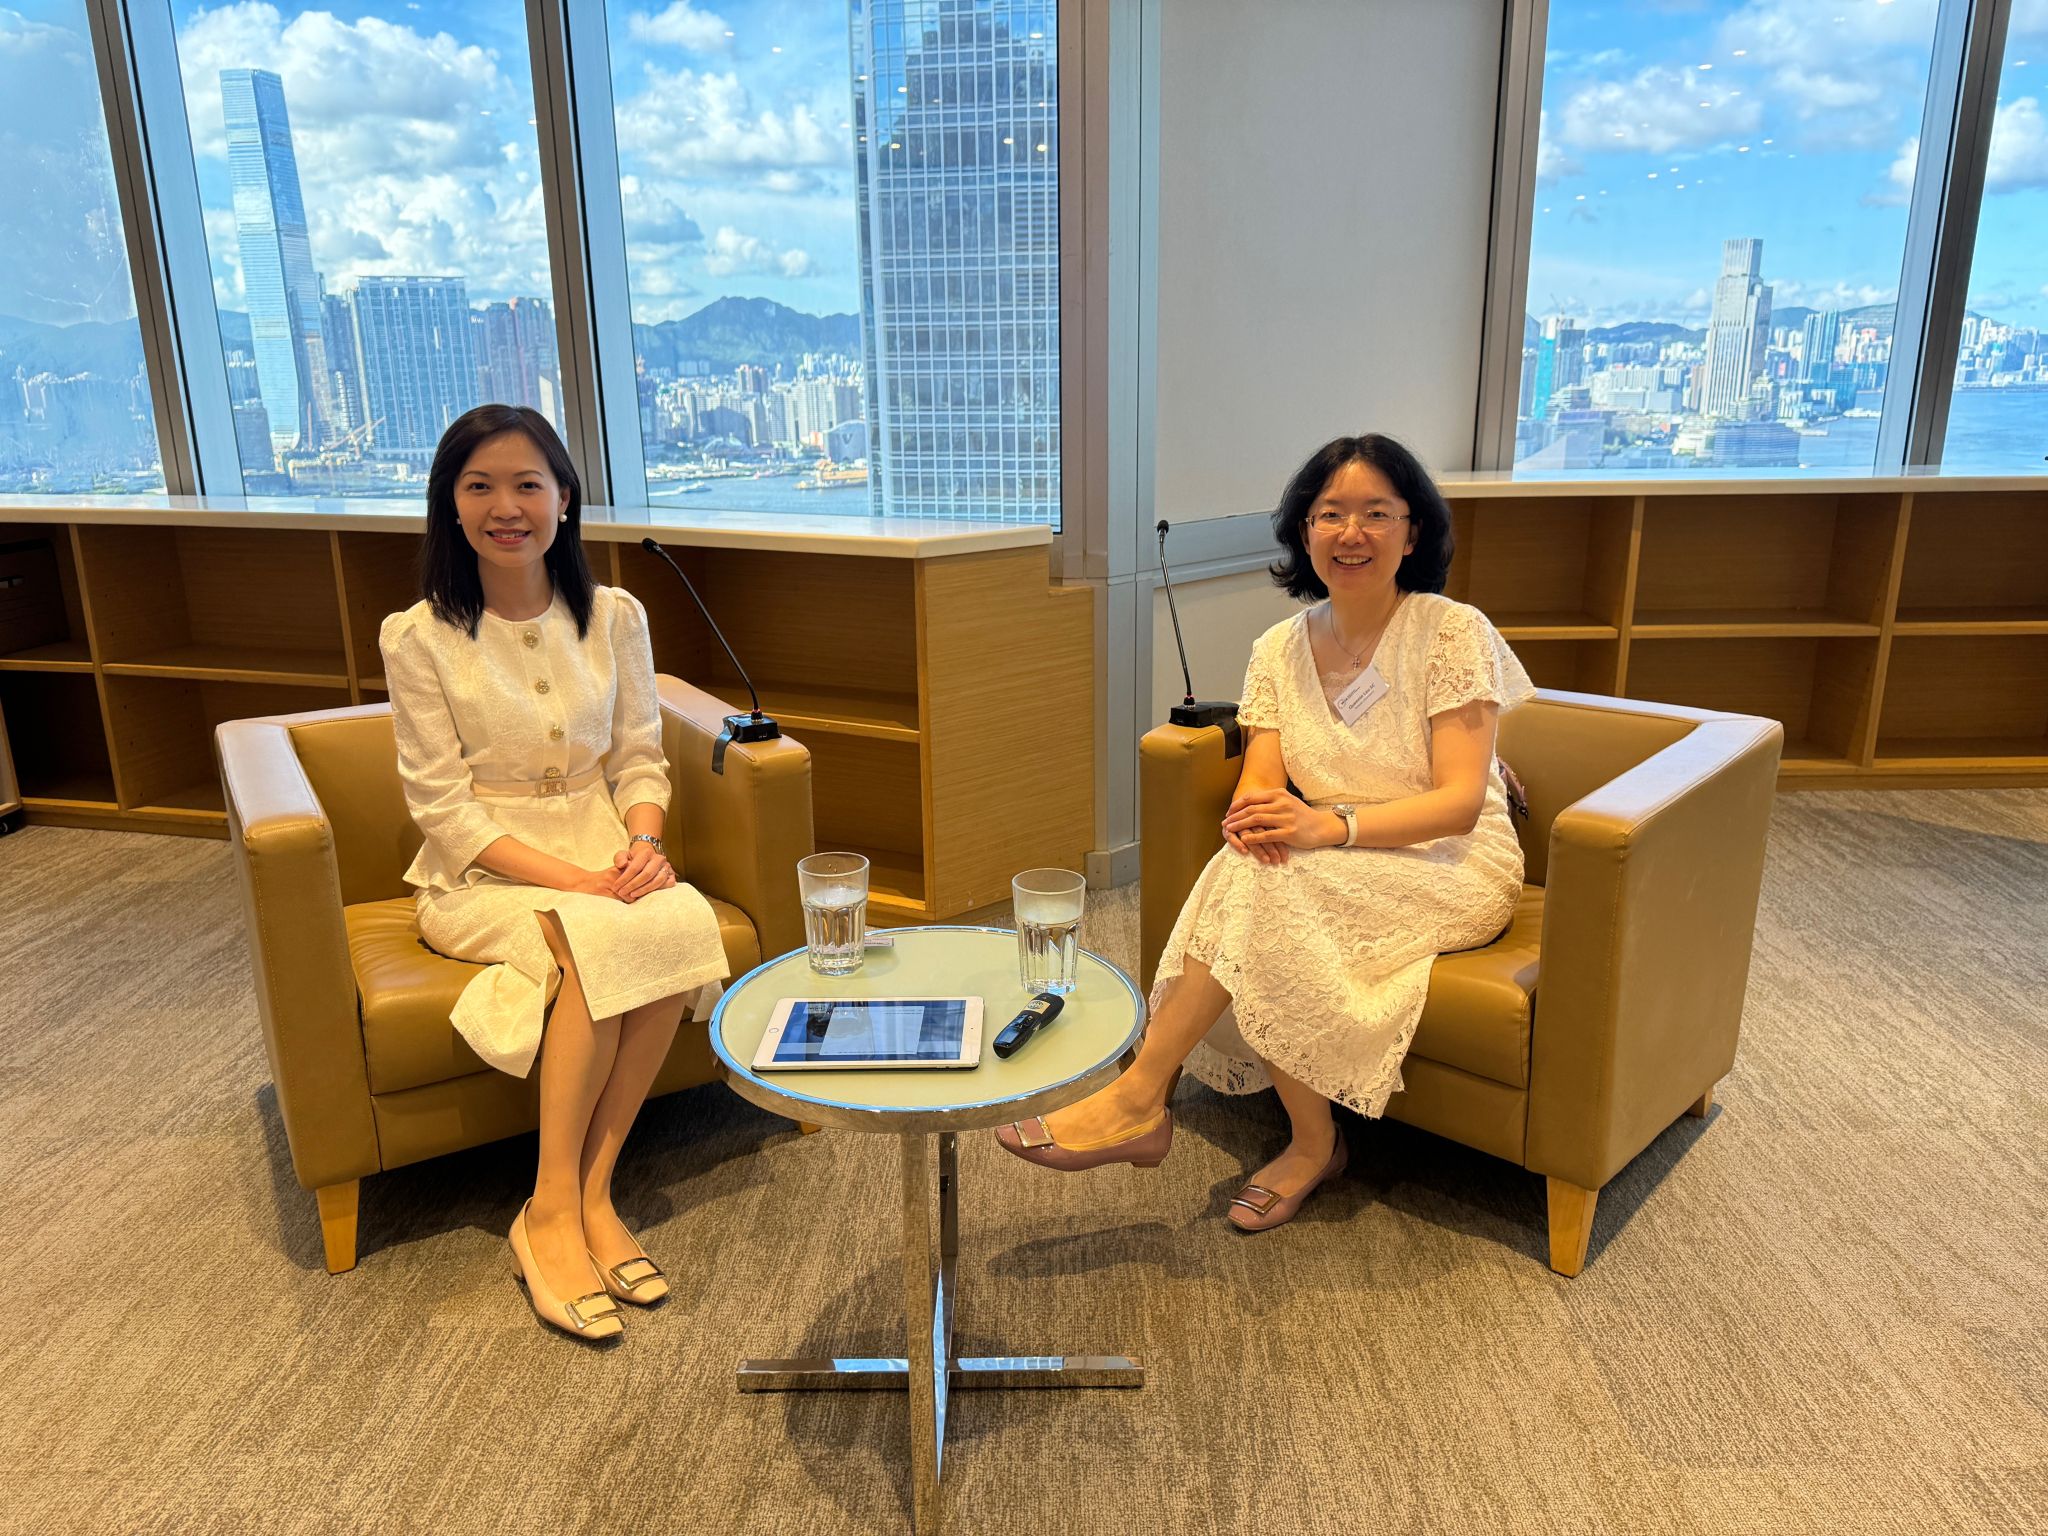
On 10 July 2024, Heidi Chui moderated the inaugural hybrid event, “WIA Coffee Roulette”. Heidi is our Senior Partner and a Committee Member of the Hong Kong International Arbitration Centre (HKIAC) Women in Arbitration (WIA) initiative. This event, sponsored by Stevenson, Wong & Co. and AllBright Law (Hong Kong) Offices, featured an engaging and insightful interview with the esteemed Queenie Lau SC.
…

Heidi led a dynamic discussion exploring the myriad accomplishments and challenges that have shaped Queenie’s career. A childhood love for Enid Blyton’s Malory Towers series inspired her to go to boarding school in the UK. Queenie shared her remarkable journey from studying at the Cambridge University to becoming a solicitor in Hong Kong and then joining Temple Chambers as a barrister. Beyond her legal career, Queenie also shared her passion for music, including playing in the college orchestra while Eddie Redmayne played a lead role on stage!

Queenie’s candid discussion covered her transition to arbitration, her first experiences as counsel in arbitration, and later as a mediator and arbitrator. She emphasised the importance of being open to new opportunities. She shared how she managed to overcome the challenges of running her own “mini business” as a barrister, compared to working in large teams as a solicitor. Her anecdotes about balancing a demanding career with diverse interests, such as photography and stress relief techniques, were fun and inspiring.

Queenie also discussed arbitration’s innovative nature, highlighting the increasing use of bilingual proceedings (especially Mandarin and English together) and the flexibility arbitration offers. She shared her experiences with virtual and hybrid hearings and gave practical tips for conducting effective online arbitrations.

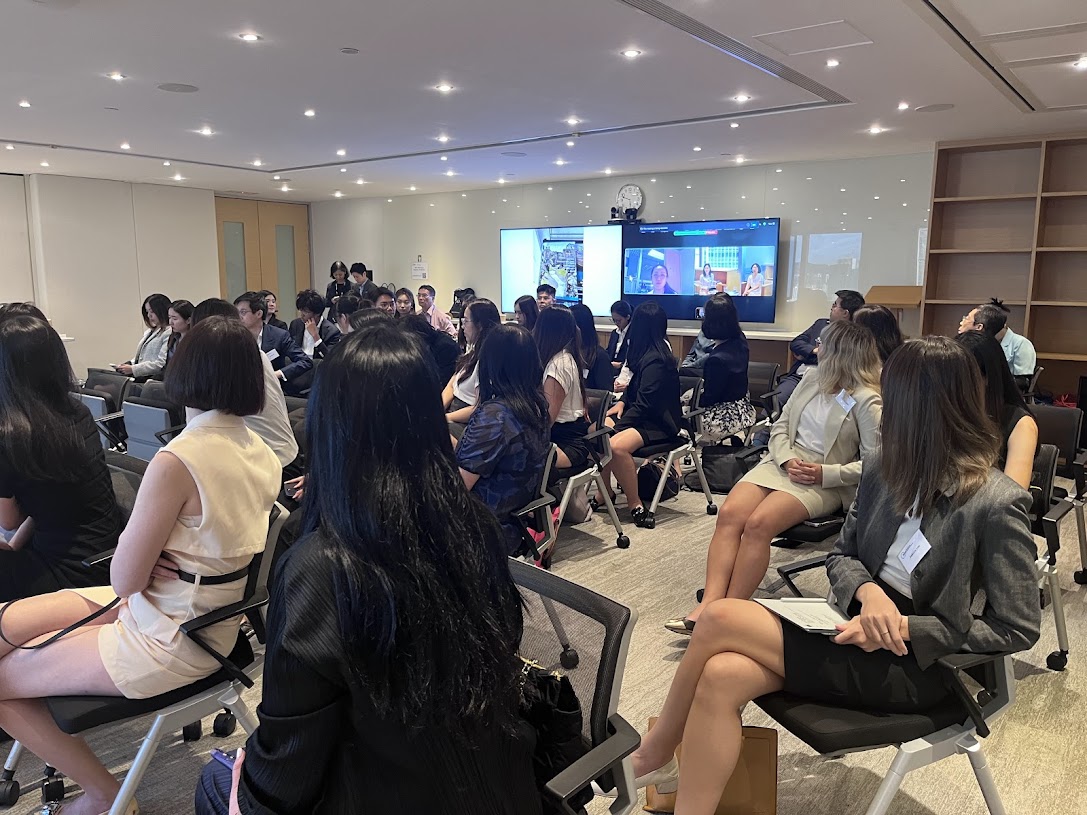
Following the interview, participants engaged in a vibrant networking session, which facilitated meaningful connections and insightful exchanges within the arbitration community. With over 50 attendees joining both in-person and online, the event successfully fostered a collaborative environment.

For any enquiries, please contact Heidi Chui.
Stevenson, Wong & Co. is pleased to share that Sundy Service Group Co. Ltd (the “Company”) (Stock Code: 9608) has successfully resumed trading of its shares on the Main Board of The Stock Exchange of Hong Kong Limited (the “Stock Exchange”) on 4 July 2024, following a suspension that began on 28 March 2024.
…
Stevenson, Wong & Co. has acted as the Company’s Hong Kong legal advisers as to its successful listing on the Stock Exchange on 18 January 2021, and has continued to serve as its advisers as to Hong Kong laws since then. We are delighted to see that the Company has now resumed trading after a relatively short suspension of only three months.
Our corporate finance team comprised Partners Hank Lo and Rodney Teoh, Associates Angela Lau and Audrey Ng, Trainee Solicitor Austin Kot, and Paralegal Jay Lee. Our regulatory and compliance team comprised Partner Osbert Hui, Senior Associates Rainbow Ip and Alex Tsang, and Associate Karlie Cheung.
Please contact our Partners Hank Lo, Rodney Teoh and Osbert Hui for any enquiries or further information.
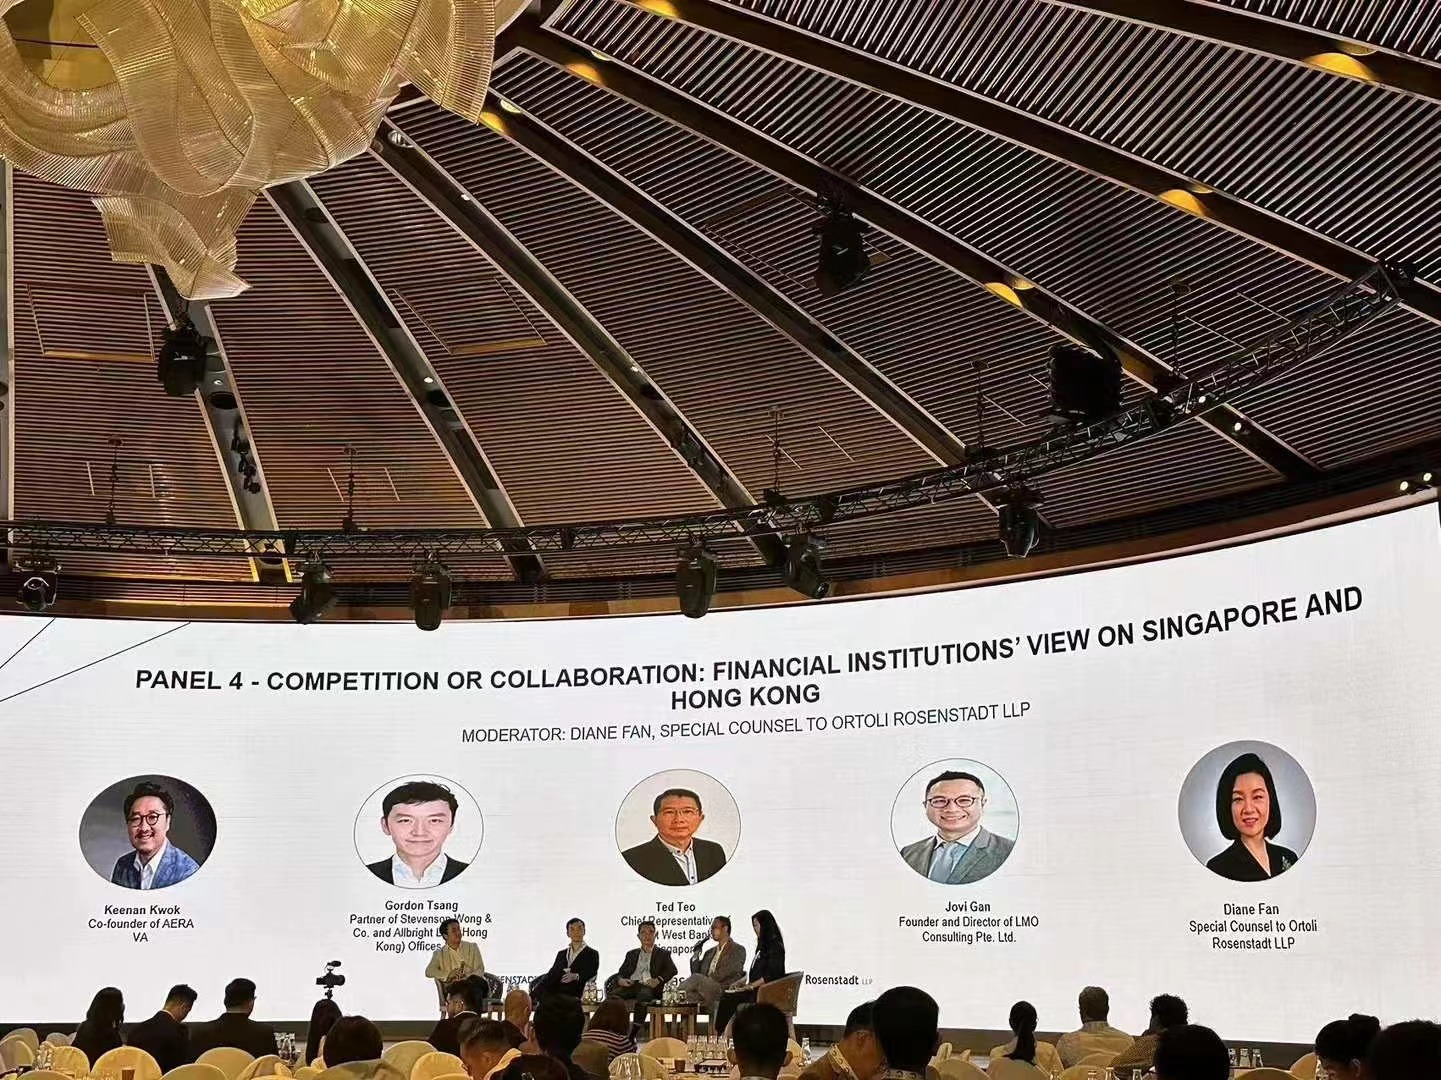
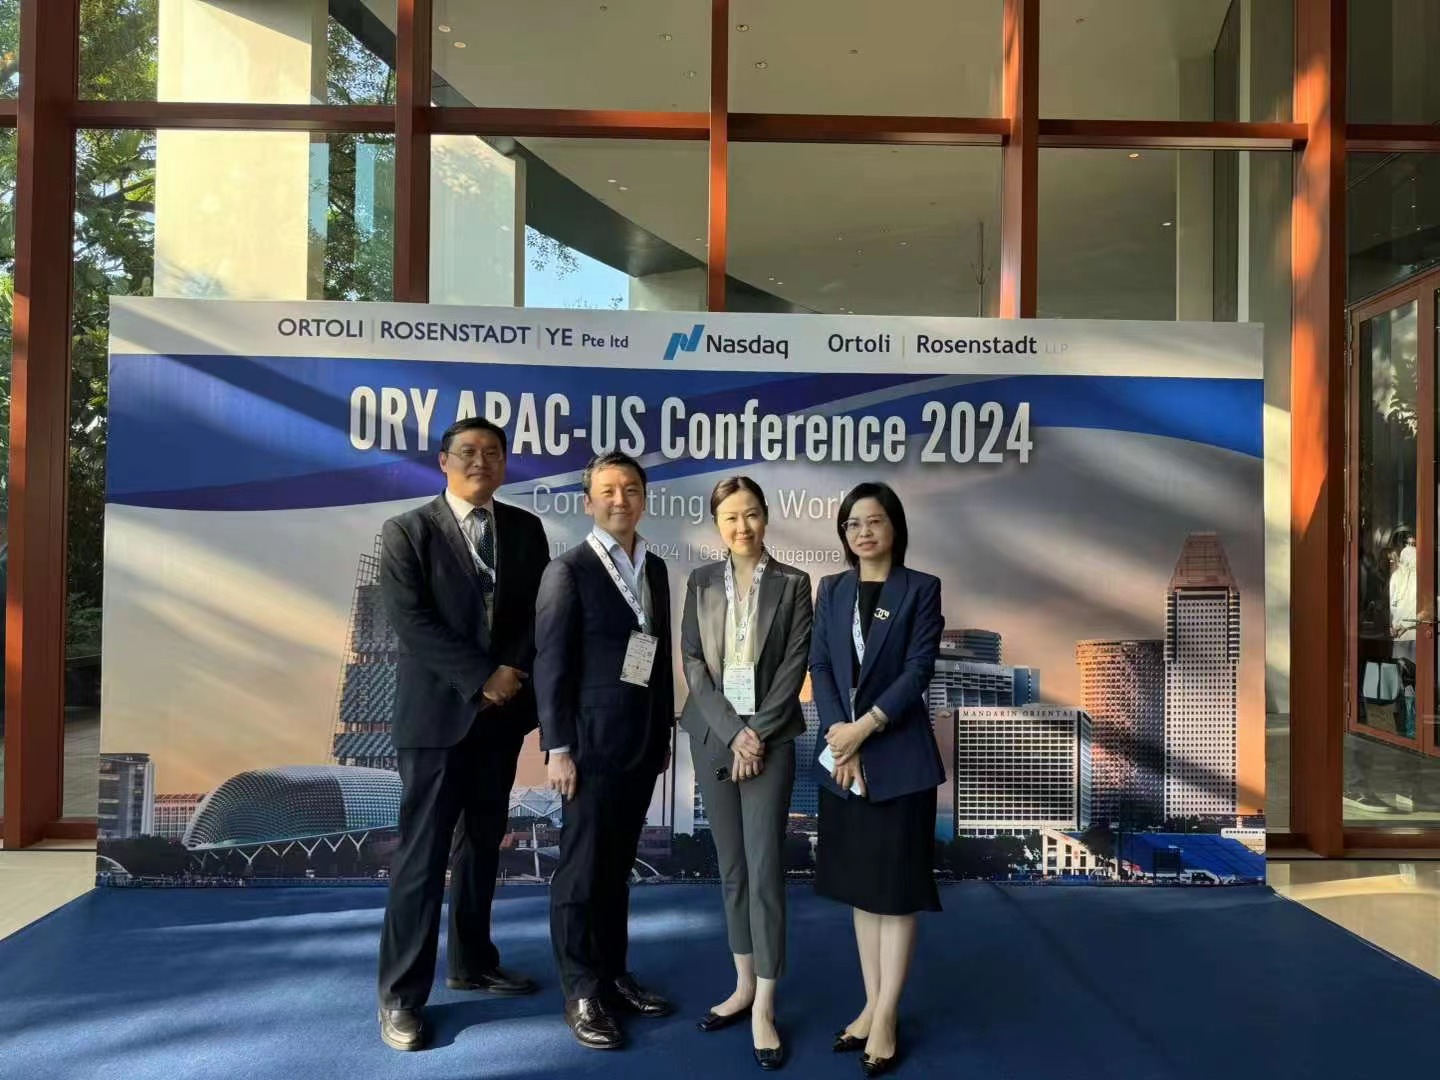
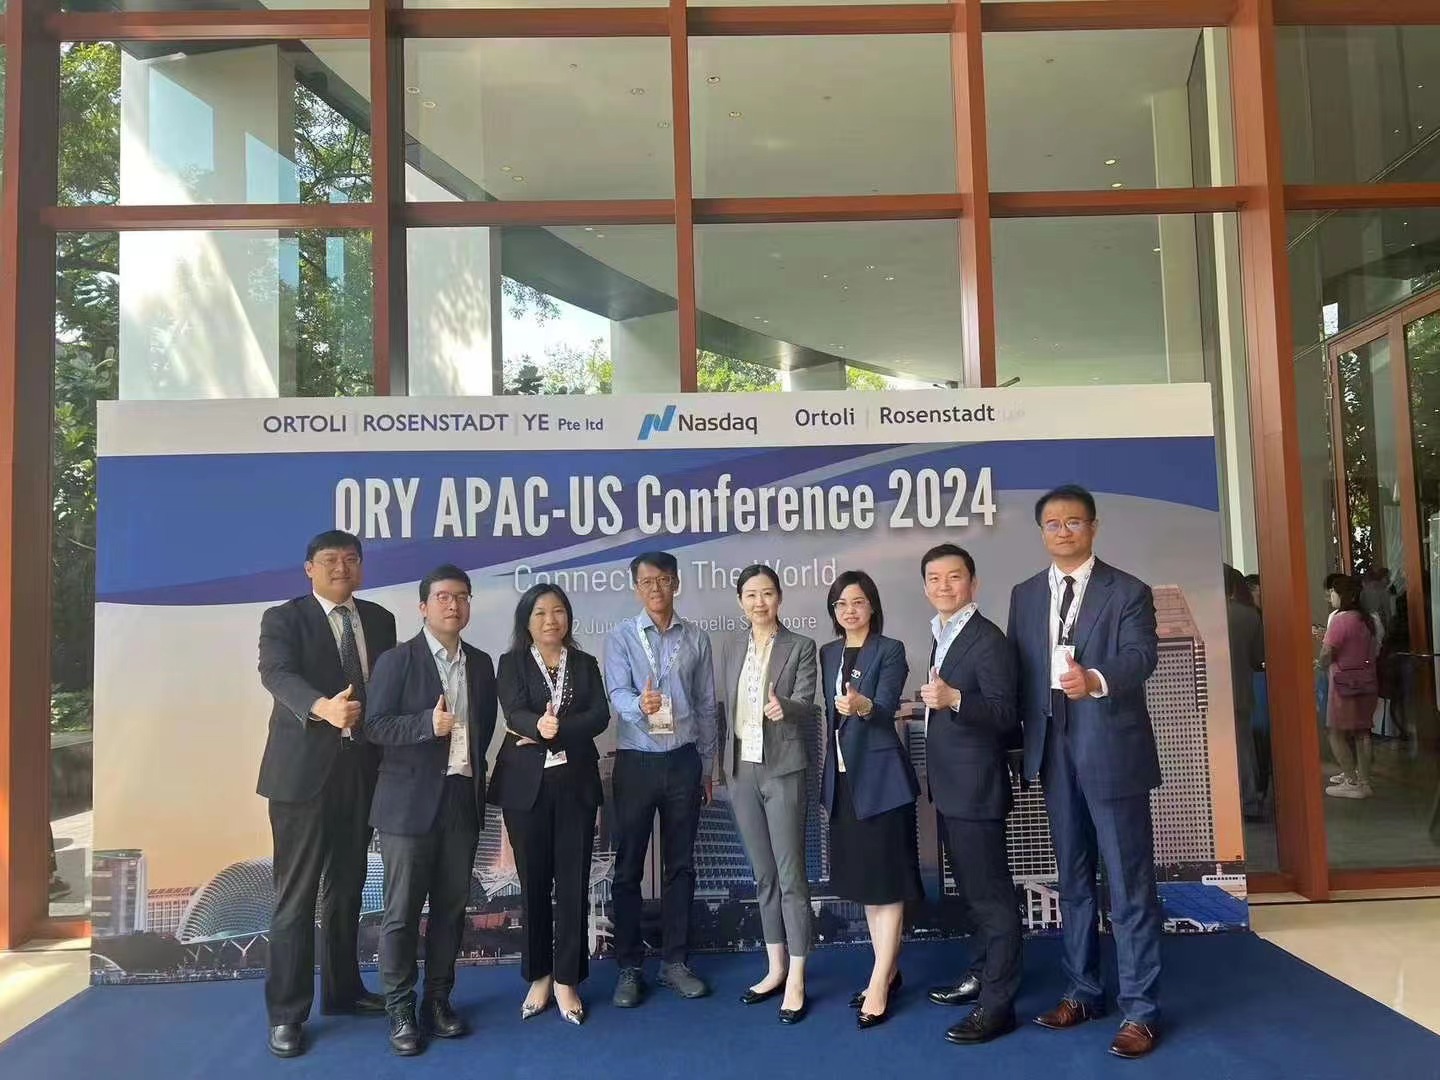
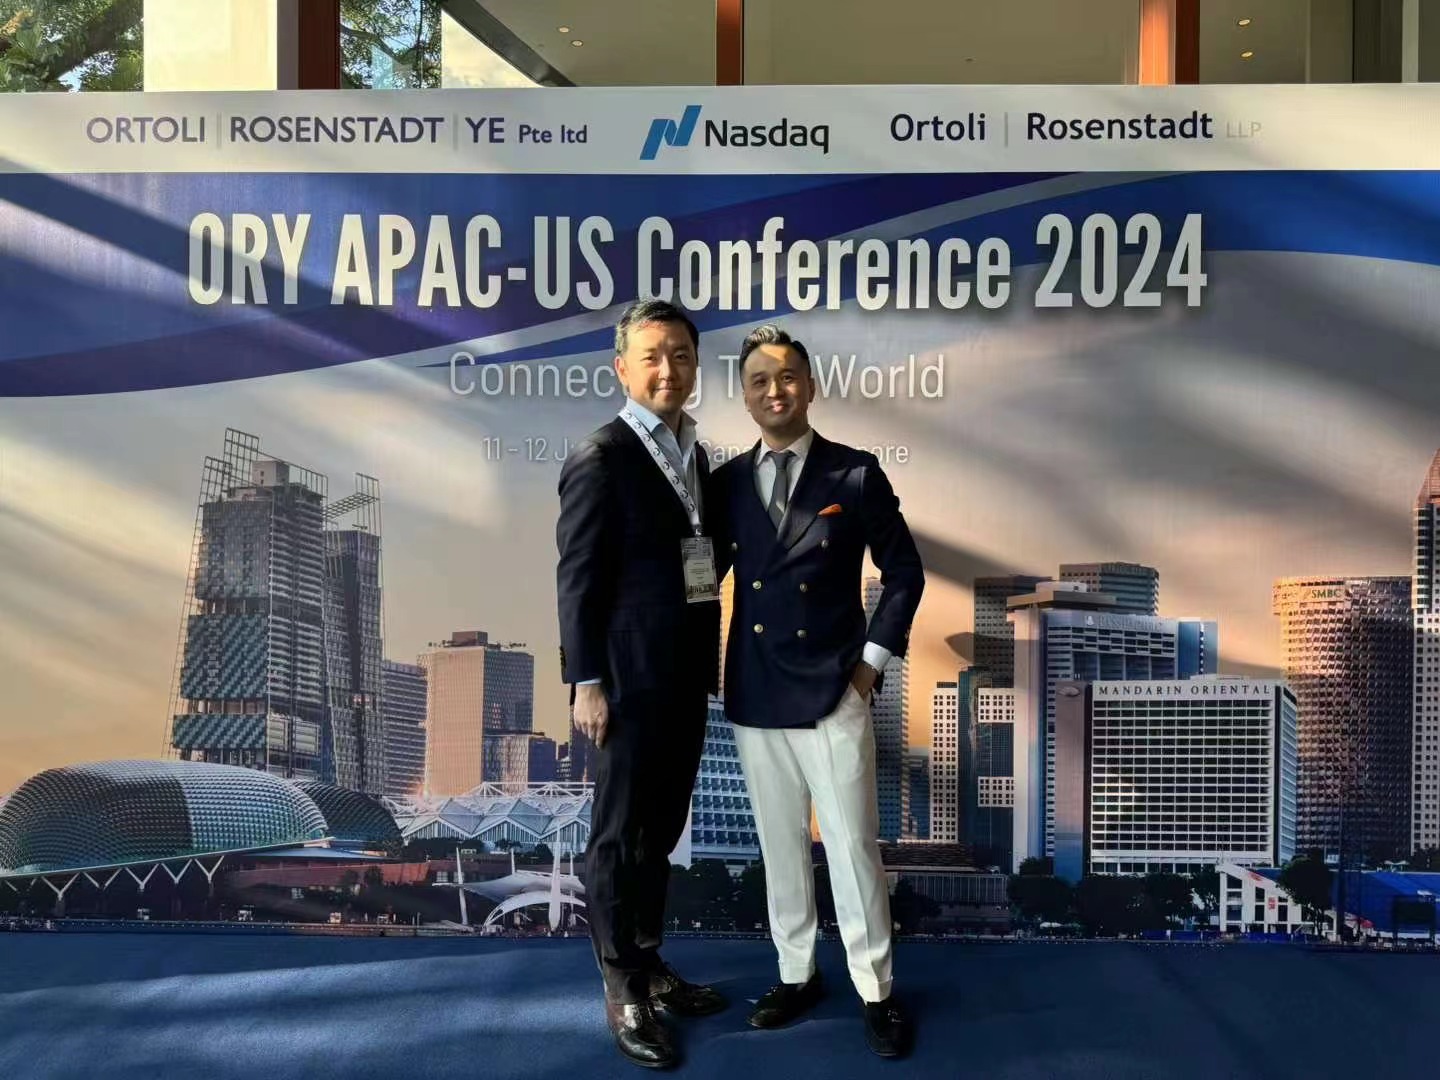
Our Partner Gordon Tsang was invited to attend the “ORY APAC-US Conference 2024” from 11 – 12 July 2024 in Singapore. The conference was co-organised by Ortoli Rosenstadt LLP (“OR Law”), Ortoli Rosenstadt Ye Pte. Ltd, and Nasdaq Stock Market (“Nasdaq”). The event was sponsored by our associated firm AllBright Law Offices.
…
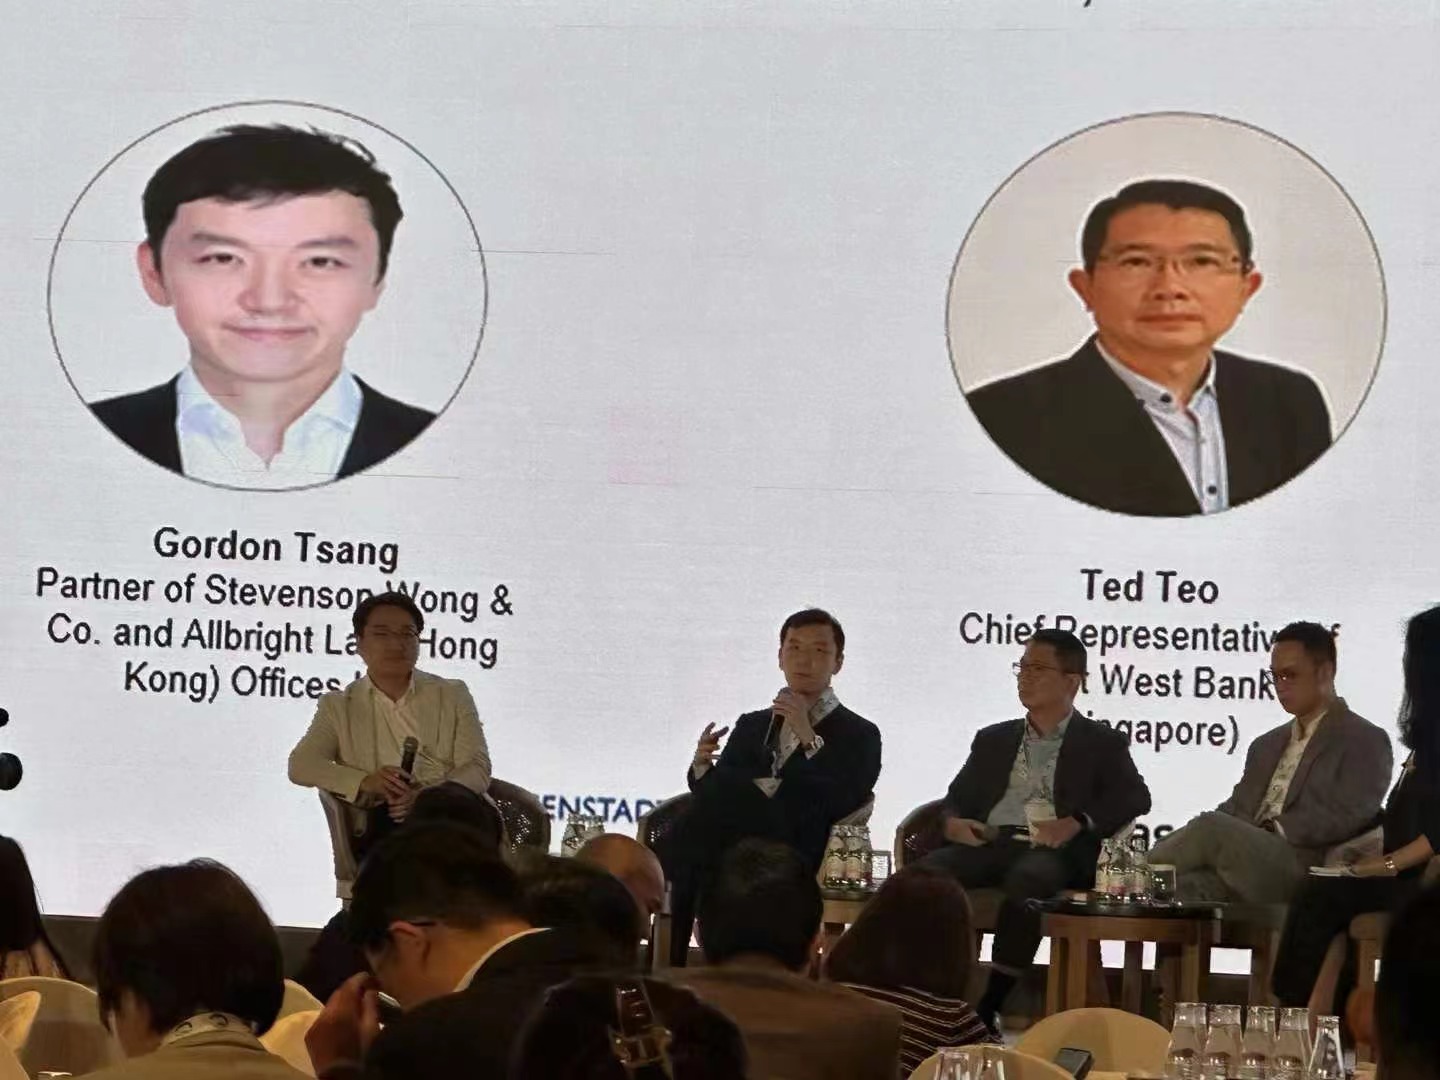
On the first day of the conference, Gordon was one of the panel speakers in the session “Competition or Collaboration: Financial Institutions’ view on Singapore and Hong Kong”. He joined other speakers in discussing various legal topics relating to Regulatory Environment and Business Climate, Market Opportunities and Growth Potential, Technological Innovation and FinTech Ecosystems and Geopolitical and Economic Factors.

Stevenson, Wong & Co. has a strong track record of advising companies on their successful listings on the Nasdaq Stock Marketing, including Junee Limited (NASDAQ: JUNE), Garden Stage Limited (NASDAQ: GSIW), Prestige Wealth Inc. (NASDAQ: PWM), Millennium Group International Holdings Limited (NASDAQ: MGIH), CBL International Limited (NASDAQ: BANL), Magic Empire Global Limited (NASDAQ: MEGL), Intelligent Living Application Group Inc. (NASDAQ: ILAG), Zhong Yang Financial Group Limited (NASDAQ: TOP), Hywin Holdings Ltd. (NASDAQ: HYW) and Oriental Culture Holding LTD (NASDAQ: OCG). In addition, Stevenson, Wong & Co. has advised more than 10 companies on their confidential filing and public filing for their Nasdaq listing applications.

As OR Law’s long-term business partner, we would like to take this opportunity to thank OR Law for their invitation and we look forward to assisting enterprises in the APAC region to resolve their legal problems and strengthen ties in Singapore, the United States and Hong Kong.

Gordon and AllBright Law Singapore Offices


For more information, please contact our Partner Gordon Tsang.